Date: October 28, 2026
Industry: Satellite Communications / Telecommunications
The landscape of global telecommunications underwent a seismic shift this Tuesday as the Federal Communications Commission (FCC) officially approved Amazon Leo’s $11.5 billion acquisition of satellite operator Globalstar. This landmark decision marks a pivotal chapter in the escalating competition between retail giant Amazon and Elon Musk’s SpaceX, as both companies race to dominate the final frontier of high-speed, low-latency satellite internet.
The acquisition is more than a simple corporate merger; it is a strategic maneuver designed to accelerate Amazon’s ambitious Project Kuiper—operating under its specialized satellite arm, Amazon Leo—into the lucrative "direct-to-device" market. By integrating Globalstar’s existing infrastructure, spectrum, and critical partnerships, Amazon is positioning itself to fundamentally alter how the world connects, from the most remote wilderness to the dense urban centers of the globe.
The Core Strategic Pillars of the Acquisition
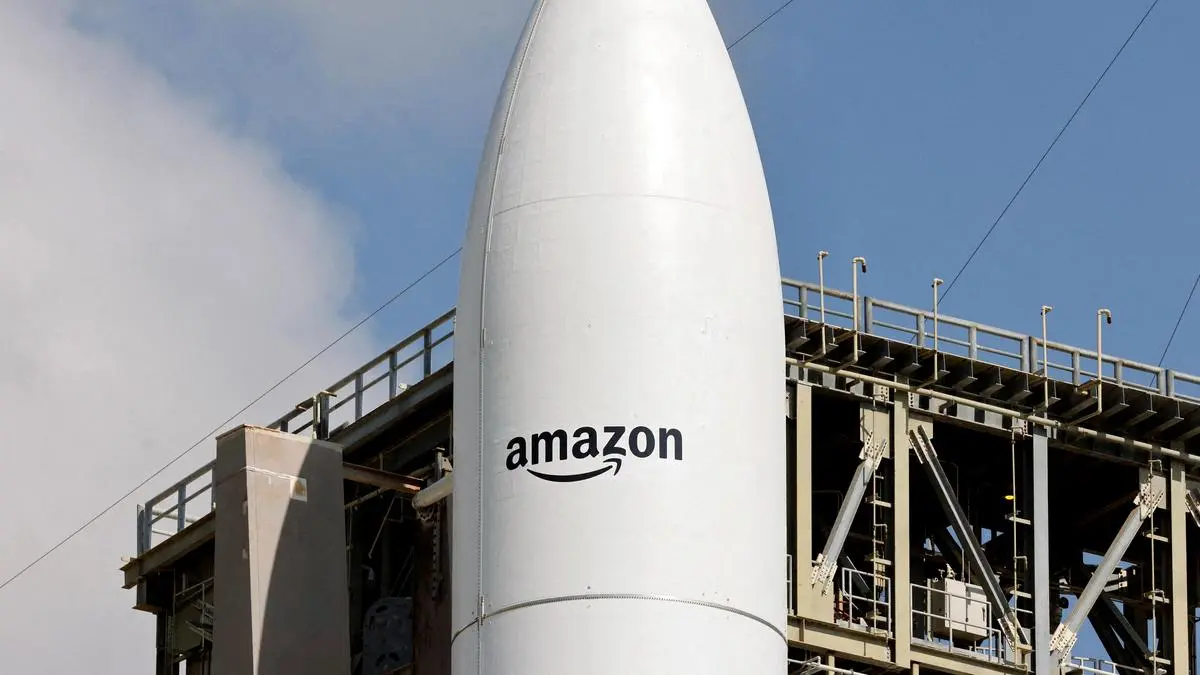
At the heart of this $11.5 billion deal is the consolidation of hardware and spectrum. Amazon Leo, which has been aggressively deploying satellites since April 2025, currently maintains a constellation of over 300 units. The company’s roadmap is staggering in its scale: the objective is to deploy approximately 3,200 satellites in low Earth orbit (LEO) by 2029.
By absorbing Globalstar, Amazon gains immediate access to:
- Existing Infrastructure: Two dozen operational satellites, providing an immediate boost to their current network of 200+ satellites.
- Spectrum Rights: Essential mobile-satellite spectrum that allows for the transmission of data directly to consumer smartphones, a capability that was previously a major hurdle for Amazon.
- Strategic Partnerships: The inclusion of Globalstar’s existing agreements, most notably its deep-rooted relationship with Apple.
Amazon has committed to investing over $10 billion into the Leo project, signaling to Wall Street and competitors alike that it has the deep capital reserves necessary to sustain a long-term infrastructure war. The company is currently on track to roll out its full-scale commercial satellite services by the end of 2026.
A Chronology of the Satellite Expansion
The journey to this approval was marked by rapid technological milestones and complex regulatory negotiations.
- Early 2024: Apple invests $1.5 billion into Globalstar, securing a 20% equity stake to fund the expansion of iPhone safety services. This move established the "direct-to-device" market as a major growth sector.
- April 2025: Amazon Leo initiates its aggressive launch cadence, surpassing 300 satellites in orbit and signaling the beginning of its operational phase.
- Late 2025: Globalstar announces that an Apple-backed network expansion is underway, with plans to grow its constellation to 54 satellites.
- Early 2026: Amazon enters formal acquisition talks with Globalstar, seeking to bypass the multi-year process of building a direct-to-device infrastructure from scratch.
- October 2026: The FCC grants official approval for the $11.5 billion merger, allowing Amazon to acquire the Apple equity stake and consolidate Globalstar’s assets.
This timeline reflects the urgency of the "New Space Race." While Amazon was initially late to the LEO market compared to SpaceX’s Starlink, the acquisition of Globalstar effectively closes the technological gap by years.
Supporting Data: The Scale of the Challenge
To understand the magnitude of this move, one must look at the dominance of SpaceX. Currently, the Starlink network consists of over 11,000 satellites. This massive constellation allows for near-ubiquitous coverage, but Amazon’s strategy is built on a different premise: high-efficiency, targeted bandwidth that utilizes both fixed-terminal and direct-to-device technology.
Financial and Technical Metrics:

- Globalstar Revenue dependency: In 2025, Apple accounted for approximately 63% of Globalstar’s total revenue, underscoring the critical nature of the Apple-Globalstar partnership.
- The 2029 Goal: Amazon’s goal of 3,200 satellites is designed to provide high-density coverage for regions that currently suffer from "digital deserts."
- Spectrum Auctions: The FCC’s upcoming vote to advance a new auction of wireless spectrum will be the next major hurdle, intended to facilitate further development of direct-to-device services across the United States.
Official Responses and Regulatory Outlook
The FCC has framed the approval as a pro-competition move. FCC Chair Brendan Carr released a statement following the vote, highlighting the broader societal benefits of the merger.
"The FCC has empowered Amazon Leo to deliver fast, next-gen satellite broadband services, increase competition, and help communities stay connected all across the country," Carr stated. The regulator emphasized that the consolidation of assets will lower the barrier to entry for mobile-satellite services, theoretically lowering costs for consumers.
From the corporate side, Amazon has moved to reassure stakeholders—specifically Apple—that the transition will be seamless. Amazon confirmed that it has signed a new agreement with Apple to continue providing the Emergency SOS and "Find My" features that millions of iPhone and Apple Watch users rely on globally. By acquiring Apple’s 20% stake in Globalstar, Amazon is effectively stepping into the role of Apple’s primary connectivity partner, ensuring the continuity of these life-saving services.
The Broader Implications: A Future Connected
The ramifications of this merger extend well beyond the stock market. We are witnessing the birth of an era where "dead zones" in cellular coverage become a relic of the past.
1. The Death of Connectivity Gaps
The most immediate impact for the average consumer will be the expansion of emergency connectivity. As smartphones become inherently linked to satellite constellations, the ability to send messages or trigger distress signals from the middle of the ocean or remote mountain ranges will become a standard feature rather than a luxury.
2. Market Competition
The competition between Amazon and SpaceX is expected to drive down prices for satellite internet hardware. Currently, the cost of terminals and service subscriptions remains high. As the FCC pushes for more spectrum auctions, the increased supply of connectivity is likely to force both Amazon and SpaceX to offer more competitive pricing models to capture the enterprise and residential markets.
3. Geopolitical and National Security Implications
Satellite communications are increasingly viewed through the lens of national security. Having a US-based, Amazon-owned network provides a reliable alternative to other international providers, ensuring that domestic communications infrastructure remains robust in the face of potential terrestrial network failures or natural disasters.
4. The "Direct-to-Device" Revolution
The "direct-to-device" market is the new "Gold Rush." By acquiring Globalstar, Amazon has leapfrogged competitors who are still struggling to navigate the regulatory and technical hurdles of sending high-frequency data directly to handheld devices. This capability is expected to be a major selling point for future smartphone generations, as users demand devices that remain connected regardless of their location on the planet.
Conclusion
As we look toward the end of 2026 and into 2027, the approval of the Amazon-Globalstar merger stands as a watershed moment in the history of telecommunications. While the path to deploying 3,200 satellites remains fraught with engineering and logistical challenges, Amazon’s move provides the necessary infrastructure to compete head-to-head with the world’s most advanced satellite operators.
The synergy between Amazon’s massive cloud computing capabilities (AWS) and this newly expanded satellite network suggests a future where cloud services and global connectivity are inextricably linked. For the consumer, the promise is clear: faster, more reliable, and ubiquitous internet access is on the horizon, provided by an infrastructure that is growing more robust with every launch. As the FCC continues to oversee the evolution of the spectrum, the stage is set for a battle of titans that will ultimately define the infrastructure of the 21st century.