For twenty-nine-year-old Harsh, a professional working in the social sector, the path to adulthood was supposed to follow a familiar script. Like his parents, who purchased their South Delhi home in 2008, Harsh spent his early twenties imagining the security of a mortgage and the pride of property ownership. He has been diligent, saving 40% of his monthly salary—a sacrifice few of his peers can sustain—in hopes of securing a down payment. Yet, as he monitors the real estate market, the dream feels increasingly like a mirage.
"Of course, housing prices were rising for our parents’ generation," Harsh notes, reflecting on the widening chasm between his reality and theirs. "But they weren’t skyrocketing like they are today. Plus, our incomes are stagnating. The math simply doesn’t add up anymore."
Harsh is far from alone. As the oldest cohort of Gen Z enters their prime earning years, they are discovering that the traditional markers of success—specifically home ownership—are becoming structural impossibilities. They are navigating a perfect storm of macroeconomic volatility, stagnant wage growth, and an AI-driven labor market shift that threatens the very stability required to qualify for a home loan.
The Affordability Crisis: A Data-Driven Reality
The frustration felt by young professionals is backed by stark economic data. According to a 2023 paper by the Centre for Social and Economic Progress (CSEP), a Delhi-based public-policy think tank, the average Indian home now costs approximately 11 times the average annual household income. This is a dramatic departure from the global affordability benchmark of 5 times annual income.
The situation is most acute in India’s primary commercial hubs. Data from real-estate consultancy Knight Frank reveals that in Mumbai and Delhi, property prices have doubled between 2010 and 2025. In the satellite city of Gurugram, the surge has been even more aggressive, with prices jumping by 3.5 times during the same period.
For the middle-class aspirant, these figures represent a barrier to entry that no amount of personal discipline can overcome. While real estate remains the bedrock of Indian household wealth—comprising roughly 77% of total assets as of FY22—that wealth is increasingly concentrated in the hands of older generations who bought in during the 1990s and early 2000s, before the hyper-inflation of the property market.

Chronology of a Shift: From Ownership to Uncertainty
The trajectory of the Indian housing market has shifted significantly over the last three decades.
- The Pre-2010 Era: During this period, real estate was viewed as a relatively accessible investment. With modest interest rates and steady, though not exponential, price growth, middle-income families could realistically aim to own a home within five to seven years of starting their careers.
- The 2010–2020 Decade: This era marked the beginning of the "skyrocketing" phase. Rapid urbanization, combined with speculative investment, pushed property prices to levels that decoupled from local wage growth.
- The 2020–2025 Period: The post-pandemic landscape introduced new variables. Inflation spiraled, and the labor market faced unprecedented disruption. For Gen Z, this period has been defined by high-interest rates, which have made servicing a home loan a significantly more expensive endeavor, even as the base price of property continues to climb.
The Employment Paradox: Education vs. Earning Power
The crisis is exacerbated by a fundamental disconnect in the Indian labor market. According to an extensive study published by Azim Premji University, out of the 5 million students who graduated annually between 2005 and 2023, only about 2.8 million found employment.
The quality of these jobs is just as concerning as the quantity. Fewer graduates are finding stable, salaried employment, which is the primary credential required for mortgage approval. Data from Data for India indicates that real wages—income adjusted for inflation—actually fell by 4% between 2012 and 2024.
This creates a "trapped" generation. They are over-educated relative to the available job market, underpaid relative to the cost of living, and burdened by the societal expectation that they must own a home to be considered "settled." Furthermore, Gen Z is the first generation to face the existential threat of AI-driven mass layoffs. The IT sector, which served as the engine of India’s middle-class mobility, is currently under immense pressure, forcing young workers to prioritize short-term survival over long-term asset building.
The Inheritance Factor: The New Inequality
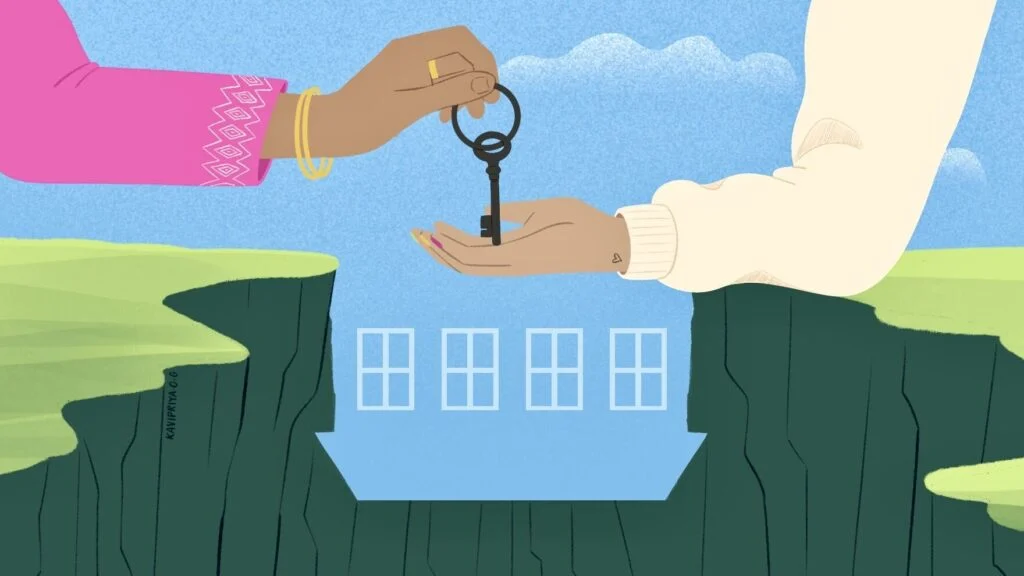
With the traditional path of "saving and buying" becoming blocked, the reliance on intergenerational wealth has shifted from a luxury to a necessity. For many Gen Z individuals, inheriting a family home is no longer just a bonus; it is the only viable path to property ownership.
This trend is creating a deep socioeconomic divide. Those whose parents own property are being insulated from the housing crisis, while those from families who do not own land or apartments are effectively priced out of the market for life. This concentration of property in the hands of a few families threatens to solidify a new form of inequality, where one’s housing status is determined more by lineage than by individual merit or career success.

Implications for the Future of Urban India
Despite the grim statistics, the aspiration remains. Knight Frank’s research indicates that seven out of 10 Gen Zers still express a strong preference for owning a home. This desire is rooted in the deep-seated cultural importance of land ownership in India, where a house is seen as the ultimate symbol of social security.
However, the implications of this persistent demand meeting a broken supply-side dynamic are profound:
- The Rise of Perpetual Renting: As home ownership becomes impossible for the majority, India may witness a permanent shift toward a renter-class society, particularly in cities like Bangalore, Mumbai, and Delhi. This will necessitate stronger rental laws and a shift in how the government approaches housing policy.
- Delayed Family Planning: The inability to secure a stable living environment is already influencing the social choices of Gen Z, including the decision to delay marriage and childbirth. The high cost of housing acts as a hidden tax on the demographic dividend.
- Migration and Brain Drain: If cities continue to become unaffordable, top-tier talent may seek opportunities in smaller, more affordable cities or emigrate entirely, undermining the growth potential of India’s major economic hubs.
- Policy Pressure: The government is under increasing pressure to address the affordability gap. Potential interventions—such as tax incentives for first-time buyers, stricter regulations on speculative real estate investment, and the development of affordable, high-density social housing—are becoming essential components of the national discourse.
Conclusion: A Call for Structural Reform
The struggle of individuals like Harsh is a symptom of a systemic failure to balance urbanization with affordability. The Indian dream, once predicated on the ability of the average worker to build a home through hard work and consistent saving, is being eroded by market forces that prioritize asset appreciation over accessibility.
For Gen Z, the future of housing is not just a personal challenge—it is a societal one. Without significant intervention to align property prices with local wage growth and to provide alternatives to the current speculative market, the "great Indian dream" may remain just that: a dream, unreachable for those who are currently building the country’s future. The task ahead for policymakers is to recognize that a country’s prosperity cannot be measured solely by the value of its real estate, but by the ability of its youngest generation to find a place to call their own.