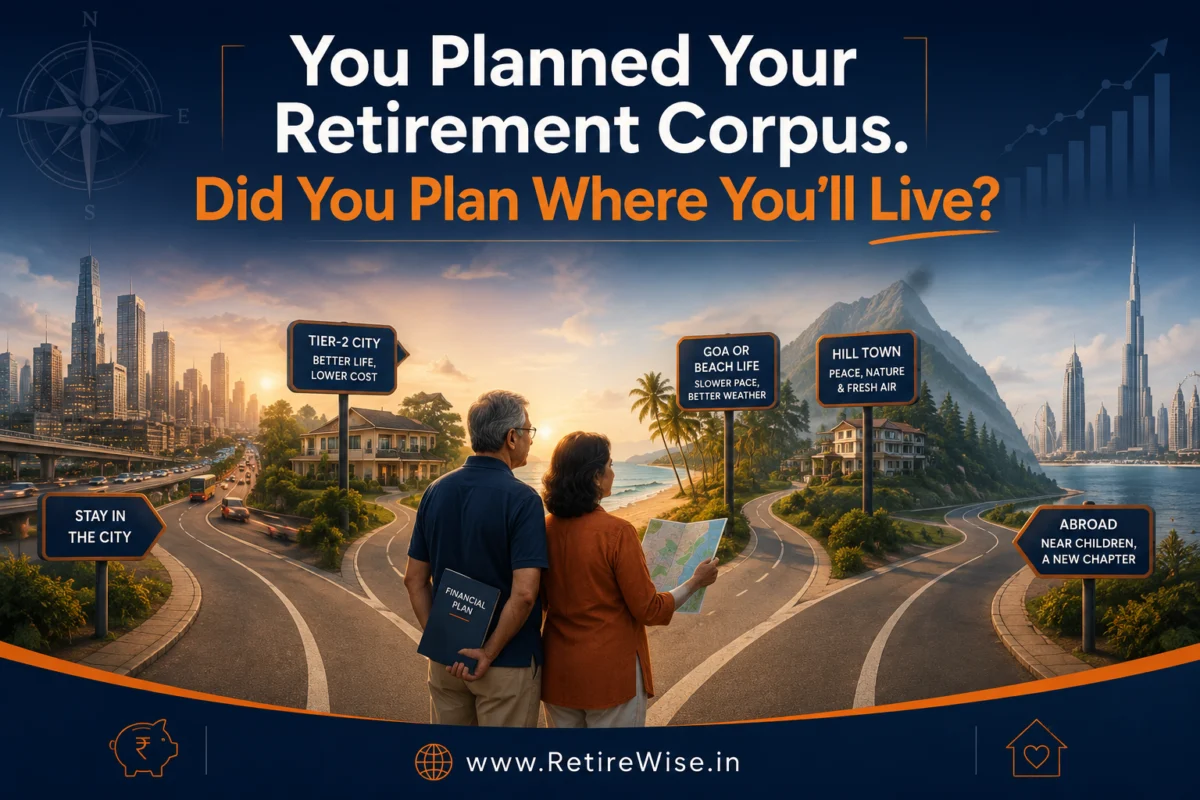
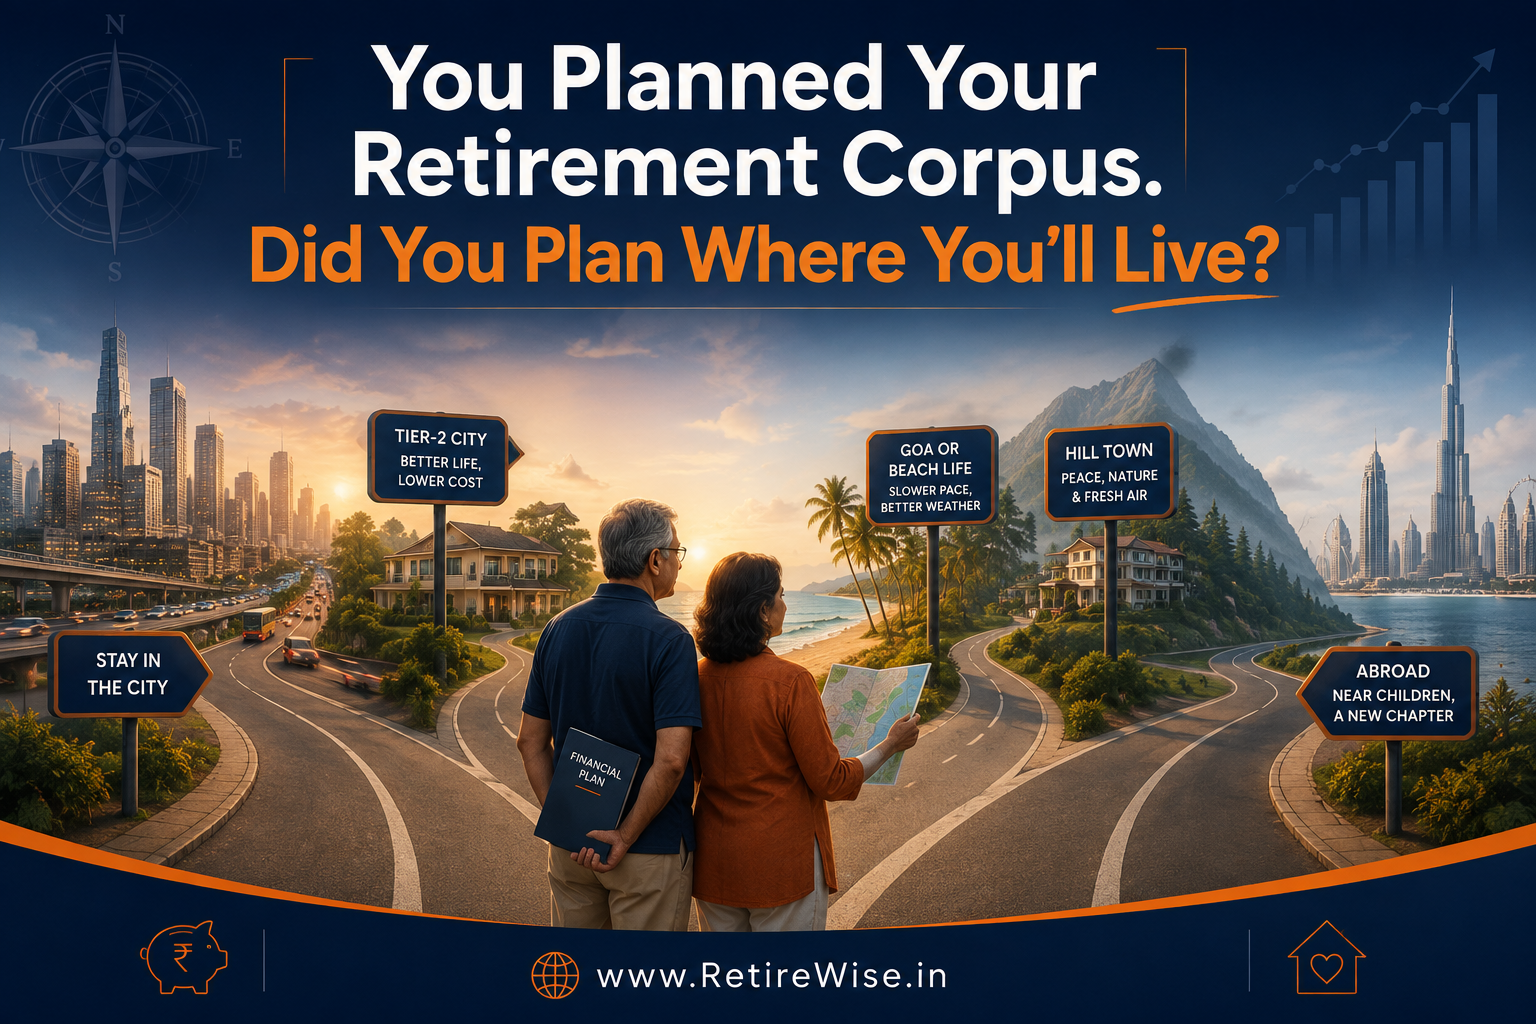
For decades, the discourse surrounding retirement in India and across the globe has been dominated by a single, obsessive metric: "The Number." Financial advisors, retirement calculators, and anxious professionals focus almost exclusively on the corpus—the total sum required to sustain a lifestyle without a monthly paycheck. However, a growing body of evidence and real-world case studies suggest that while the "how much" is vital, the "where" is the silent architect of retirement success or failure.
As life expectancy rises and the concept of "active retirement" takes hold, the geographic choice of where to spend one’s sunset years is emerging as a decision with profound implications for financial sustainability, physical health, and psychological well-being.
The Retirement Paradox: Planning the Math, Ignoring the Life
The fundamental paradox of modern retirement planning is that people spend thirty years stress-testing their investment portfolios but less than thirty minutes investigating the social and medical infrastructure of their intended destination.
"Most people live where their job dictates," says Hemant Beniwal, a veteran financial planner. "When that anchor is removed, they often drift by inertia, staying in high-cost, high-stress urban centers, or they make impulsive moves to ‘scenic’ locations without considering the logistical realities of aging."
The choice of location is not merely a lifestyle preference; it is a strategic financial decision. The same ₹5 crore corpus that feels abundant in a Tier-2 city like Nashik or Dehradun may feel precariously thin in the heart of Mumbai or Singapore. Yet, as many retirees are discovering, the "cheapest" location often carries hidden costs that no spreadsheet can fully capture.
A Chronology of Relocation: Case Studies in Trial and Error
The journey to finding the "perfect" retirement spot is rarely a straight line. Real-world experiences highlight a recurring pattern: the transition from romanticized escape to practical reality.
The Nashik Experiment: The Social Infrastructure Gap
A prominent case involves a professional from Mumbai who, exhausted by the city’s relentless pace and pollution, sought refuge in Nashik. On paper, the move was a financial masterstroke. Real estate was cheaper, the air was cleaner, and the pace was tranquil. He rented a property to "test the waters"—a move lauded by experts.
However, within two years, the experiment ended. The failure was not due to the city itself but the "social vacuum" it created. His family remained anchored in Mumbai’s ecosystem. The lesson learned was stark: A beautiful environment cannot compensate for the absence of a primary social circle. The "place" was perfect, but the "people" were missing.
The Dubai Returnee: The Tax vs. Belonging Trade-off
Another significant trend involves Non-Resident Indians (NRIs). A client who spent his career in Dubai returned to India during the COVID-19 pandemic. Faced with the choice of where to settle, he briefly considered returning to Dubai to maintain his NRI status and optimize tax liabilities.
He lived there for two years, treating it as a retirement haven. Ultimately, the lack of a familiar social fabric and the transient nature of expat life in the Middle East drove him back to India. For him, the financial benefits of tax-free living were outweighed by the emotional tax of isolation.
The Hybrid Model: The Rise of the "Split-Year" Retiree
In response to these challenges, a new chronology of retirement is emerging: the hybrid model. A couple from Bangalore, seeking the serenity of Kerala but unwilling to abandon the amenities of a Tier-1 city, opted for a seasonal rotation. By downsizing their Bangalore residence and renting in Kerala, they optimized their cost of living while maintaining access to high-end urban healthcare for part of the year.
Supporting Data: The Four Pillars of Geographic Suitability
When evaluating a retirement destination, four data-driven factors determine the long-term viability of the choice:
1. Healthcare Proximity and the "Golden Hour"
As retirees age, the proximity to tertiary care hospitals becomes the most critical variable. Data suggests that the "Golden Hour"—the period following a traumatic injury or cardiac event where medical intervention is most effective—is significantly compromised in remote "scenic" retreats. A location must be evaluated not just for its clinics, but for its access to specialists and emergency response infrastructure.
2. Geo-Arbitrage: Stretching the Corpus
"Geo-arbitrage" is the practice of earning in a high-cost economy and spending in a lower-cost one. Moving from a Tier-1 city (like Delhi or Bangalore) to a Tier-2 city (like Mysore, Jaipur, or Coimbatore) can reduce monthly recurring expenses by 25% to 40%. This effectively "increases" the retirement corpus without requiring additional investment returns.
3. The Loneliness Index
According to various psychological studies, social isolation is as detrimental to health as smoking 15 cigarettes a day. Retirement communities are increasingly popular because they provide built-in "social capital." When choosing a location, the availability of clubs, community centers, and peer groups is a leading indicator of life satisfaction.
4. The Maintenance Burden
Large, ancestral homes or isolated farmhouses often become "gilded cages." The physical and financial effort required to maintain a large property in old age can become a significant source of stress. Modern retirement planning favors "lock-and-leave" properties—apartments or managed villas that offer security and ease of maintenance.
Official Responses and Industry Trends: The Silver Economy
The real estate and financial sectors are beginning to respond to this shift in retirement thinking. We are seeing the birth of the "Silver Economy" in India.
Senior Living Projects: Major developers are shifting focus toward "Senior Living" communities. Unlike the "old age homes" of the past, these are premium townships designed with geriatric-friendly architecture, 24/7 medical assistance, and community-driven calendars. Industry experts suggest this sector is poised for a 15% CAGR (Compound Annual Growth Rate) over the next decade.
Financial Product Innovation: Banks and wealth management firms are starting to incorporate "Relocation Modeling" into their software. Instead of a static inflation rate, these models account for the different inflation trajectories of Tier-1 vs. Tier-2 cities, allowing clients to visualize how their money lasts in different geographies.
The "Trial Retirement" Movement: Financial planners are now officially recommending "Trial Retirements." Rather than selling the primary residence immediately, retirees are encouraged to rent in their "dream" location for 12 to 24 months. This "try before you buy" approach prevents the catastrophic financial loss of a failed relocation.
Implications: The Future of Aging
The implications of where one chooses to retire extend far beyond the individual. There are broader societal and economic shifts at play:
1. The De-urbanization of Wealth: As high-net-worth retirees move to Tier-2 cities, they bring purchasing power and demand for high-quality services, potentially stimulating local economies and improving regional healthcare standards.
2. The Psychological Shift: We are moving away from "Passive Retirement" (staying where you are because you have to) to "Intentional Retirement" (moving where you want to be because it serves your life goals). This agency is linked to higher cognitive function and better emotional health in seniors.
3. The Healthcare Infrastructure Pressure: As retirees cluster in specific "haven" cities (like Dehradun or Coimbatore), there will be immense pressure on those cities to upgrade their medical and transport infrastructure to accommodate an aging population.
Conclusion: Choosing the View, Planning the Reality
A retirement destination is not a postcard; it is the stage upon which the final third of one’s life will be performed. The most successful retirees are those who treat the "Where" with the same analytical rigor as the "How Much."
The author’s own strategy serves as a blueprint for this balance. By purchasing land within 45 minutes of a city, encouraging friends to buy nearby to ensure a community, and ensuring a hospital is within a 15-minute drive, he has built a "synthetic" retirement haven. It offers the quiet of the country with the safety net of the city.
In the final analysis, the "number" in your bank account provides the fuel, but the "place" provides the road. You have spent decades working for your money; it is only logical to spend a few years ensuring you wake up in a place that makes that work feel worth it.
The question remains for every professional: You have planned the number. Have you planned the morning?