In the modern financial landscape, a silent but profound shift is altering the trajectory of millions of families. For decades, the "Indian Dream" followed a predictable, linear sequence: education, career, marriage, parenthood, and finally, a graceful retirement. However, as social norms evolve and the age of marriage and parenthood climbs, these once-distinct milestones are colliding.
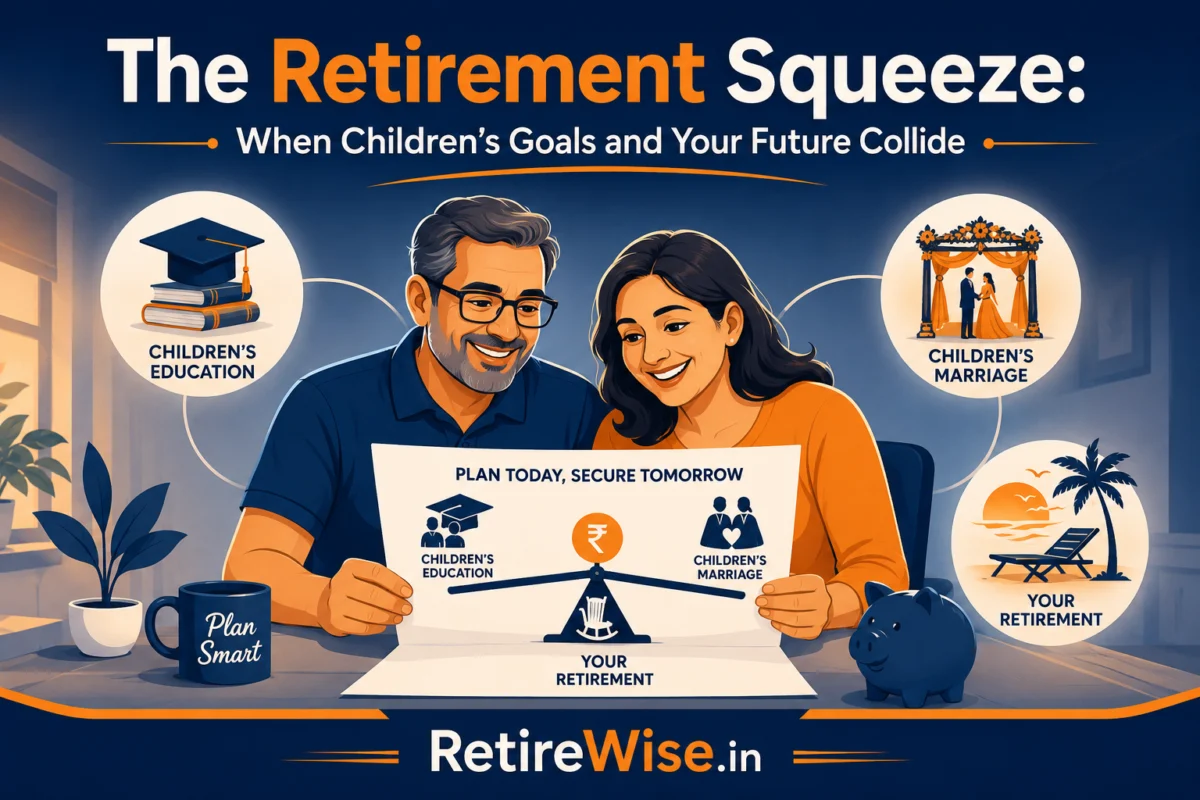
The "Retirement Squeeze"—a term gaining traction among financial planners—describes the precarious moment when the peak expenses of a child’s higher education and marriage overlap directly with the cessation of a parent’s primary income. This phenomenon is no longer an outlier; it is becoming the definitive financial challenge of the 21st-century middle class.
The Core Conflict: A Tale of Two Timelines
The fundamental issue is one of compressed timing. A generation ago, the financial lifecycle was a relay race where one goal finished before the next began. Today, it has become a simultaneous sprint across multiple tracks.
A reader, pseudonymously named Amit, recently articulated this struggle with poignant honesty. Faced with the daunting task of funding his child’s elite education and upcoming wedding while simultaneously securing his own retirement, Amit found himself contemplating a "downgrade" from a premium lifestyle to a "humble" one. His realization—that life is more than comforts and luxuries—is wise, yet it highlights a systemic pressure: the fear of outliving one’s assets because of obligations to the next generation.
The "Quick Answer" to why this is happening lies in the calendar. When marriages and children arrive later in life, the "clear decade" of the 50s—historically reserved for aggressive retirement saving—is now being cannibalized by undergraduate tuition fees and wedding planners. Retirement is no longer the "last" goal; it is a goal that must now compete for the same rupee that pays for a Master’s degree in a foreign university.
Chronology of the Shift: From Sequence to Collision
To understand the gravity of the current situation, one must examine the chronological shift in the Indian household structure over the last forty years.
The Traditional Timeline (Circa 1980–2000)
In the traditional model, the average age of marriage for the urban middle class was approximately 24 to 26 years. Children were typically born shortly thereafter. By the time the parents reached the age of 50, their children were 22 to 24—graduated, often employed, and perhaps approaching marriage. This left the parent with a crucial "golden window" between the ages of 50 and 60. With the children independent, the household’s largest expenses were settled, allowing for a decade of maximum contributions to Provident Funds, gratuities, and private investments.
The Modern Timeline (Circa 2010–Present)
Contrast this with the contemporary reality. Due to extended periods of education and the pursuit of career stability, the average age of marriage in urban centers has shifted toward the early to mid-30s. Consequently, many couples are having children in their mid-30s or even early 40s.
For a parent who has a child at 35, that child will be entering university when the parent is 53. If the child pursues a five-year medical degree or a post-graduate qualification abroad, the highest tuition costs will hit when the parent is between 58 and 62—the exact window when professional income typically plateaus or ceases entirely. The "golden window" has vanished, replaced by a "collision zone."
Supporting Data: The Rising Cost of Living and Giving
The squeeze is intensified by two diverging economic trends: the hyper-inflation of education and the increasing longevity of retirees.
1. Education Inflation
While general Consumer Price Index (CPI) inflation in India often hovers between 5% and 7%, education inflation is estimated to be significantly higher, often ranging between 10% and 12% annually. A professional degree that cost ₹10 lakhs a decade ago can now easily exceed ₹30 lakhs. For parents nearing retirement, the choice to fund these costs out-of-pocket can result in a massive "corpus drain" from which a retirement fund may never recover.
2. The Longevity Paradox
Advancements in healthcare mean that a 60-year-old today can reasonably expect to live another 25 to 30 years. This requires a retirement corpus that can withstand three decades of inflation. When parents divert ₹50 lakhs from their savings to fund a lavish wedding or an Ivy League degree, they aren’t just spending money; they are potentially shaving five to ten years off their "solvency" in their 80s.
3. The "Big Fat Wedding" Syndrome
Despite the financial pressure, social expectations regarding weddings remain high. In many cases, the cost of a single week of celebration can equal three to five years of a parent’s retirement expenses.
Official Responses and Financial Principles: The Hierarchy of Needs
Financial experts and veteran planners, such as Hemant Beniwal, emphasize a cold but necessary hierarchy in financial planning. The primary mantra is: "There is no loan for retirement."
The Education Loan as a Strategic Tool
One of the most effective strategies suggested by planners—even for wealthy clients—is the utilization of education loans. This is often met with resistance by Indian parents who view debt as a "failure" of their parental duty. However, professional financial advice suggests otherwise for two reasons:
- Corpus Protection: By taking a loan, the parent’s retirement investments remain compounded and untouched during the most critical years of growth.
- Character Building: When a child is responsible for a portion of their post-graduate loan, it fosters financial discipline and a sense of ownership over their career. It transforms the loan from a "burden" into a "tool" that serves two generations.
The Oxygen Mask Principle
In aviation, passengers are instructed to secure their own oxygen masks before assisting others. Financial planning operates on the same logic. A parent who exhausts their savings for their child’s wedding and subsequently becomes a financial burden on that same child in their old age has not performed an act of love; they have merely deferred a financial crisis. Securing one’s retirement is, in fact, a gift to one’s children, ensuring they are never saddled with the medical and living expenses of their aging parents.
Implications: Choice vs. Necessity
The philosophical takeaway from Amit’s story—the transition from a "premium" to a "humble" lifestyle—carries profound implications for how we define a successful life.
The Dignity of Choice
There is a stark difference between a "voluntary downgrade" and a "forced hardship." If an individual decides in their 50s to adopt a minimalist lifestyle, downsize their home, and reduce discretionary spending to ensure their retirement fund is robust, they are exercising agency. They are choosing a "humble" life from a position of strength. Conversely, those who ignore the "squeeze" and spend lavishly on their children often find themselves forced into a "humble" life in their 70s because the money has run out. That is not a lifestyle choice; it is a failure of planning.
The Societal Shift
As more families experience the retirement squeeze, we may see a shift in Indian social contracts. The expectation that parents will provide "everything" (education, house, wedding) is being challenged by the mathematical reality of the 21st century. We are likely to see:
- Smaller, Boutique Weddings: A move away from massive guest lists toward meaningful, sustainable celebrations.
- Merit-Based Education: A greater reliance on scholarships and student-led financing.
- Delayed Retirement: Professionals choosing to work until 65 or 70, not out of passion, but out of financial necessity to bridge the gap created by late-life parenthood.
Conclusion: The Path Forward
The "Retirement Squeeze" is an inevitable byproduct of our changing demographics and social evolution. While it presents a daunting challenge, it is not insurmountable. The solution requires a blend of rigorous mathematical planning and a shift in perspective.
Parents must recognize that their retirement is a non-negotiable goal. Unlike a wedding, which can be scaled down, or an education, which can be financed through loans and future earnings, retirement has no Plan B. By prioritizing their own financial independence, parents provide their children with the ultimate safety net: a family where the previous generation is self-sufficient.
As Amit wisely noted, a life measured by more than comforts and luxuries is a richer one. The goal for the modern earner is to arrive at that "humble life" as a free decision—a deliberate choice to value peace of mind over social optics—ensuring that the squeeze of the present does not become the crisis of the future.