By [Your Name/Agency]
Published: October 2026
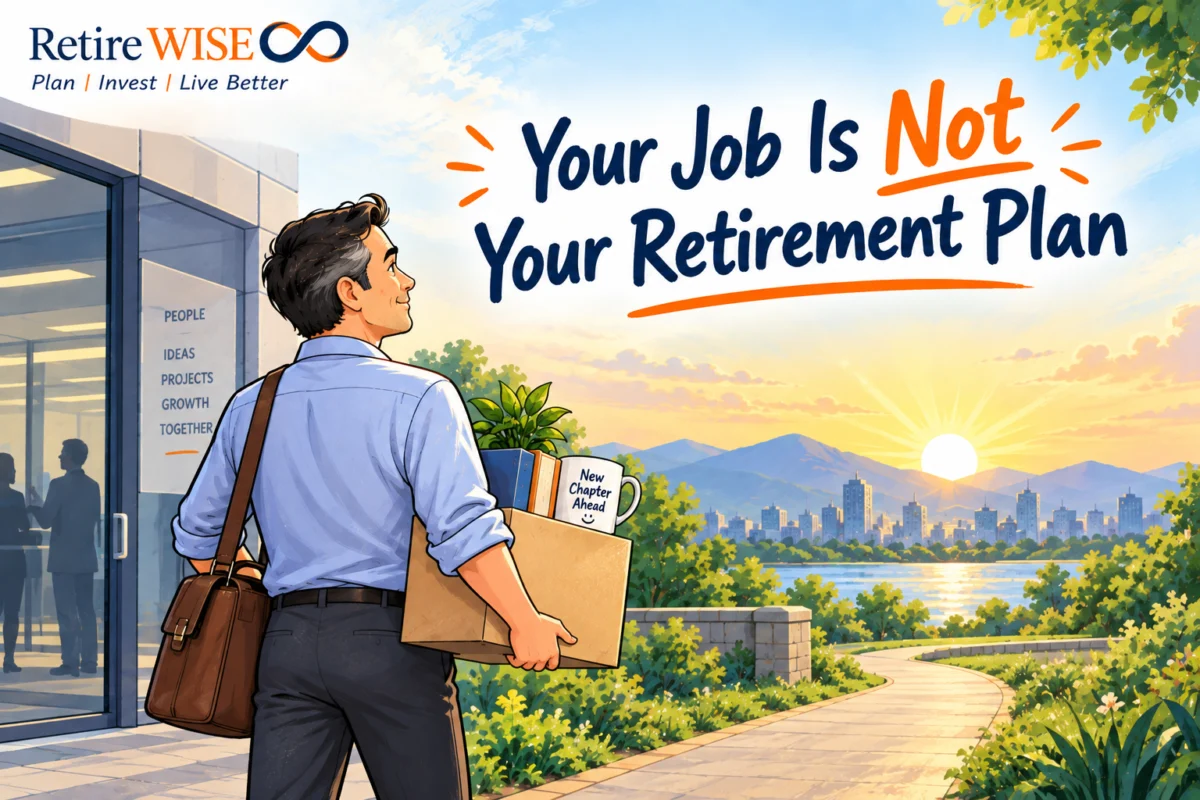
In the bustling corridors of India’s Silicon Valley, a quiet but profound shift is occurring. For decades, the narrative of the Indian middle class was built on a simple, linear progression: education, a stable corporate career, gradual wealth accumulation, and a graceful exit at age 60. However, as the global economy undergoes a period of radical restructuring, that timeline is being shattered.
A recent wave of layoffs in the technology sector—most notably within the Indian tech hubs of global sportswear giants and multinational conglomerates—has brought an uncomfortable truth to the surface. For many high-earning professionals, retirement is no longer a choice made in one’s sixties; it is a corporate decision made on their behalf in their late forties.
As Hemant Beniwal, a prominent financial planner, recently observed through an advertisement at an airport: "If you do not plan for your retirement, life will eventually plan it for you." This unsettling reality is the new frontier of financial planning in an era of involuntary career exits.
1. The Core Reality: The Rise of Involuntary Retirement
The fundamental fact facing the modern workforce is that a high salary and a prestigious job title do not equal financial security. Security is a measure of how long you can survive without that salary.
Recent market data suggests that the "danger zone" for corporate professionals begins at age 45. At this stage, salaries are typically at their peak, but so is "role redundancy" risk. When companies restructure, the most expensive middle and senior management layers are often the first to be thinned.
The primary issue is not just the immediate loss of income; it is the "Compounding Gap." When a professional is laid off at 47, they don’t just lose their current salary—they lose the 13 most critical years of wealth accumulation they had banked on. This phenomenon, termed "Involuntary Retirement," transforms a temporary career setback into a permanent financial crisis if the individual’s corpus is not job-independent.
2. Chronology of a Career Crisis: The Story of ‘Rahul’
To understand the mechanics of this shift, we look at the case of "Rahul" (a pseudonym), a 47-year-old senior IT professional based in Bengaluru. Rahul’s trajectory is representative of thousands of professionals in India’s Tier-1 cities.
- The Ascent (Age 25–40): Rahul built a stellar career, reaching a salary of ₹45 lakh per annum. Like many of his peers, his lifestyle expanded in tandem with his earnings. He acquired a high-value home loan, enrolled his children in premium international schools, and maintained a high-consumption lifestyle.
- The Plateau (Age 41–46): Rahul assumed he was in his "harvest years." He saved consistently, but his financial plan was built on the unshakeable assumption of a 60-year-old retirement. He viewed his job as the "security," rather than the "source."
- The Disruption (Age 47): During a global restructuring exercise, Rahul’s role was made redundant. In a single afternoon, the 13 years of planned income he expected to use to finish his home loan and fund his children’s higher education vanished.
Rahul’s situation highlights a critical chronological error in traditional planning: we assume the "end date" is a constant. In reality, the end date is a variable controlled by market forces, technological shifts, and corporate boardrooms.
3. Supporting Data: The High Cost of Lost Time
The financial implications of an early exit are often misunderstood. Most professionals focus on the "loss of salary," but the real damage is done to the time-value of money.
The Compounding Gap
In a typical 35-year career, the final ten years often contribute more to the final retirement corpus than the first twenty. This is due to the nature of compound interest, where the largest gains occur on the largest base.
- Scenario A: A professional works until 60. Their corpus grows at 10% annually. The growth in the final 5 years (55-60) can often equal the entire principal saved in the first 15 years of their career.
- Scenario B: An involuntary exit at 48. Not only does the fresh infusion of capital stop, but the individual may be forced to dip into the corpus early to sustain their lifestyle. This "double hit"—no new fuel and a leak in the tank—can reduce a retirement lifestyle by 40-60%.
The Employment Market for 45+
Data from recruitment firms indicates that while the "gig economy" is growing, the "re-employment" rate for professionals over 45 at their previous salary levels is less than 30%. Most are forced to take a "pay cut" of 20-50% to stay in the workforce, further straining their ability to reach their original retirement goals.
4. Industry Trends and Expert Responses
The recent layoffs at major tech centers in India have prompted a series of responses from HR experts and financial strategists. The consensus is that the "Job-as-Security" model is dead.
Corporate Restructuring as a Permanent Feature:
Industry analysts point out that layoffs are no longer just a response to recession; they are a tool for "organizational agility." Companies are pivoting toward AI and automation, rendering many traditional management roles obsolete regardless of the company’s profitability.
The Financial Planner’s Perspective:
Experts like Hemant Beniwal argue that the real risk is not market volatility, but "Time Risk."
"A 30 percent market fall at 50 will likely be forgotten by 60," Beniwal notes. "But ten lost years of income at 50 will still be shaping your life at 80. Money you can rebuild. Time you cannot."
The "Bangalore Speed" Metaphor:
Financial advisors often use the metaphor of Bengaluru traffic to explain career pacing. On a highway (the peak career years), you drive at 100 km/h. In traffic (a layoff or industry slowdown), you might only move at 20 km/h. The mistake is trying to maintain a "highway lifestyle" while stuck in "traffic." Flexibility—the ability to downshift expenses—is the only way to survive the crawl.
5. Strategic Implications: Building a Job-Independent Life
For the modern professional, the goal must shift from "Career Success" to "Financial Independence." The following four-step framework is now considered essential for anyone over the age of 35.
I. The "Early-Stop" Recalculation
Traditional retirement calculators ask for your retirement age and usually default to 58 or 60. Professionals must now run a "Stress Test" scenario: What if my last salary lands at 47 or 50?
If the plan fails under this scenario, the individual is currently over-leveraged or under-saved. The "gap" identified here is the true measure of their financial vulnerability.
II. Establishing a Financial Runway
An emergency fund of 3-6 months is no longer sufficient for senior professionals. Given the longer lead times to find comparable employment at age 50, a "Financial Runway" of 12-24 months in liquid, low-risk assets (Debt funds, FDs, Liquid funds) is required. This prevents the "panic sale" of long-term equity assets during a market downturn or a job hunt.
III. Decoupling Essential vs. Lifestyle Spending
One of the greatest risks to retirement is "Lifestyle Creep." When income stops, the "Essential" expenses (food, utilities, basic insurance) must be clearly separated from "Lifestyle" expenses (luxury travel, club memberships, premium car EMIs). A household that can gracefully trim 30% of its budget without collapsing is far more resilient than one built on fixed high-cost commitments.
IV. Asset Allocation for Resilience
The retirement corpus must be structured to grow even when contributions stop. This means maintaining a healthy exposure to equities even after a job loss to combat inflation, while ensuring the "Bucket Strategy" is in place—where the next 5 years of cash flow are protected in safe instruments, regardless of what the stock market or the job market does.
6. Conclusion: Taking the Hand off the Tap
The ultimate takeaway for the modern workforce is a lesson in control. As Beniwal succinctly puts it: "Your employer decides your income. Only you can decide your security."
A job is merely a tap that fills your financial reservoir. In the current economic climate, you are not the only person with a hand on that tap. The corporate world is increasingly transactional, and loyalty is rarely a shield against a spreadsheet-driven restructuring.
The path forward requires a psychological shift. Professionals must stop viewing their high-flying careers as a permanent state and start viewing them as a temporary window of opportunity to build a self-sustaining financial ecosystem. The goal is to reach a point where the next salary is a bonus, not a lifeline.
If your salary stopped today, how long would your family’s current lifestyle last? The answer to that question is the only metric of success that truly matters in the new era of retirement planning. Build that life now, while the tap is still running.