By Strategic Finance Correspondent
Updated: October 26, 2023
As the global demographic shift toward an aging population accelerates, a silent crisis is emerging within the financial planning industry. It is not a crisis of "not enough savings"—though that remains a concern for many—but rather a crisis of execution. Millions of disciplined savers are reaching the "finish line" of their careers only to find that the skills required to build wealth are diametrically opposed to the skills required to spend it.
This phenomenon, often referred to by economists as the "Decumulation Paradox," suggests that the transition from a salaried life to a corpus-dependent life is the most perilous period in an investor’s journey. According to financial experts and veteran planners, the transition involves navigating a minefield of risks that were largely irrelevant during the working years.
Main Facts: The Great Shift from Addition to Subtraction
For thirty years, the average investor follows a simple, linear logic: accumulation. The strategy is characterized by "addition"—adding to the corpus monthly through systematic investment plans (SIPs) or provident fund contributions. In this phase, time is a powerful ally, and market volatility is often a friend, allowing investors to buy more units when prices are low (Rupee Cost Averaging).
However, the moment an individual retires, the math flips. The strategy shifts to "subtraction." In this new paradigm, volatility becomes a predatory force. When an investor is forced to sell assets to fund living expenses during a market downturn, they permanently impair their capital. This "reverse rupee cost averaging" can deplete a lifetime of savings in a fraction of the time it took to build.
Financial planners now argue that the retirement corpus—often a combination of Employee Provident Fund (EPF) payouts, gratuities, and mutual fund holdings—is not an "end state" but a raw material. The challenge lies in converting this lump sum into a sustainable, inflation-adjusted monthly "paycheck" that must last for 300 to 400 months.
Chronology: The Three Phases of the Retirement Journey
To understand the complexity of retirement management, one must view it as a chronological progression rather than a static event.
Phase 1: The Accumulation Sprint (Ages 25–58)
During this period, the focus is on human capital—the ability to earn a salary. Errors in investment choices are often masked by new capital infusions. A bad market year at age 35 is a footnote because the investor has 25 years of future paychecks to repair the damage.
Phase 2: The Fragile Decade (Ages 55–65)
This is the "Retirement Red Zone," spanning the five years before and five years after the last day of work. It is here that the "Sequence of Returns Risk" is at its peak. A market crash during these years can be catastrophic because the investor is either about to stop or has just stopped contributing and is beginning to withdraw.
Phase 3: The Decumulation Marathon (Ages 60–90+)
This phase is characterized by the three distinct spending stages:
- The Go-Go Years: High activity, travel, and discretionary spending.
- The Slow-Go Years: A natural decline in activity and lifestyle expenses.
- The No-Go Years: Low lifestyle spending but a sharp, non-linear spike in healthcare costs.
Supporting Data: The Hidden Risks of the "Safe" Approach
The traditional "safe" retirement in India has long involved moving the entire corpus into Fixed Deposits (FDs). However, modern data suggests this may be the most dangerous strategy of all.
1. The Negative Real Return Trap
Current data indicates that while a senior citizen FD might offer a 7% interest rate, the post-tax return for those in higher tax brackets falls closer to 5%. Meanwhile, the "Lifestyle Inflation" rate for retirees, which includes a heavy weighting toward healthcare, is estimated at 7% to 9%. This creates a "guaranteed slow loss," where the purchasing power of the corpus erodes by 2-3% every year.
2. The 3% Rule vs. The 4% Rule
For decades, the "4% Rule" (withdrawing 4% of the initial corpus and adjusting for inflation annually) was the gold standard. However, this was based on US market history. In the Indian context, where inflation is structurally higher, experts like Hemant Beniwal argue that the "Genuinely Safe Withdrawal Rate" is closer to 3%. A retiree with a ₹5 Crore corpus who assumes a 4% withdrawal (₹20 Lakhs/year) versus a 3% withdrawal (₹15 Lakhs/year) may find themselves running out of money 10 years earlier than planned due to the compounding effect of inflation.
3. Healthcare Inflation: The Silent Killer
While the Consumer Price Index (CPI) might hover around 5-6%, medical inflation in India is consistently reported at 12-14%. For a retiree, healthcare is not a discretionary expense. A plan that models a flat 6% inflation rate across 30 years will almost certainly fail in the "No-Go" years when medical interventions become frequent.
Official Responses and Expert Perspectives
Financial industry leaders and behavioral economists have begun to speak out on the lack of preparedness for the decumulation phase.
The Behavioral Perspective:
Benjamin Graham famously noted that the investor’s worst enemy is himself. In retirement, this becomes amplified. Experts suggest that "loss aversion"—the psychological pain of seeing a corpus decline—leads retirees to make irrational decisions, such as selling equities at the bottom of a cycle or hoarding cash in low-yield accounts that lose value to inflation.
The Industry Critique:
There is a growing critique of the financial services industry, which is largely incentivized to focus on "Assets Under Management" (AUM) during the accumulation phase. "The industry is built for the gathering of wealth," says one veteran planner. "But the release of wealth is a customized, high-touch service that doesn’t scale well. Consequently, many retirees are handed a ‘Systematic Withdrawal Plan’ (SWP) and told it’s a strategy. It isn’t. It’s just a tool."
The Cognitive Decline Factor:
Research in geriatric finance shows that financial decision-making ability peaks in the mid-50s and often begins a subtle decline in the late 60s. Crucially, "financial confidence" does not decline at the same rate, leading to a dangerous gap where elderly investors may make high-stakes mistakes while being certain they are right.
Implications: A New Framework for Retirement
The shift from building a corpus to managing a withdrawal strategy requires a fundamental overhaul of the investor’s toolkit. Based on the challenges identified, the following implications are clear for current and future retirees:
The Necessity of Withdrawal Guardrails
Retirees cannot afford to withdraw a fixed amount regardless of market conditions. A "Guardrail Strategy" involves pre-defined rules: if the market falls by X%, the withdrawal is reduced by Y%. If the market performs exceptionally well, a "bonus" withdrawal can be taken. This prevents the permanent destruction of capital during downturns.
Tax-Efficient Sequencing
The order in which assets are liquidated—EPF first, then Debt Mutual Funds, then Equity—can add years to the life of a corpus. Each asset carries a different tax burden (Capital Gains vs. Income Tax slabs). A failure to optimize for taxes is equivalent to losing 10-15% of the corpus to avoidable leakage.
The "Longevity Risk" Buffer
Longevity risk is the risk of outliving one’s money. As medical science advances, planning for a 95-year lifespan is no longer conservative; it is mandatory. This requires maintaining an equity exposure even in retirement to ensure the corpus grows fast enough to outpace inflation over three decades.
The Legacy of Clarity
Retirement planning is increasingly being viewed as an act of "practical love." For the spouse who may not have handled the finances, a complex web of investments is a liability, not an asset. Modern retirement strategies now emphasize "simplification" and "consolidation"—moving from twenty different mutual funds and five bank accounts to a streamlined, automated system that a surviving spouse can manage with ease.
Conclusion
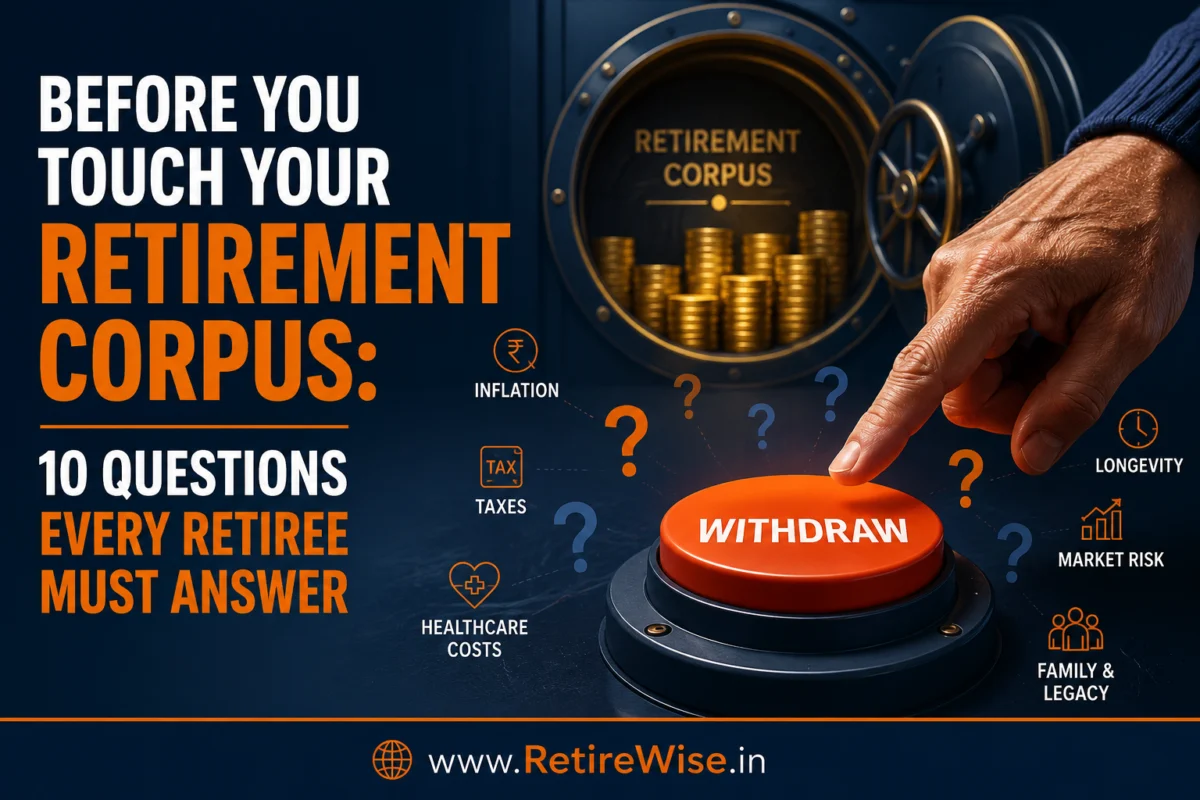
The transition into retirement is often celebrated as a finish line, but from a financial management perspective, it is the start of the most complex race an individual will ever run. The "Ten Questions" posed by experts serve as a sobering reminder: a large corpus is not a guarantee of a secure life.
The difference between a retirement of comfort and one of anxiety lies in the mastery of decumulation—the art of spending. As the data shows, those who fail to account for sequence risk, healthcare inflation, and the "FD trap" may find that while they were smart enough to earn a fortune, they were not prepared for the harder task of making it last.