By Investigative Financial Desk
For decades, the global financial services industry has operated on a singular, powerful narrative: the "Accumulation Phase." Investors are bombarded with messages about starting early, staying disciplined, and harnessing the power of compounding to build a "nest egg." However, as a generation of baby boomers and Gen X professionals reach the finish line, a sobering reality is emerging. The skills required to build wealth are fundamentally different—and often diametrically opposed—to the skills required to spend it sustainably.
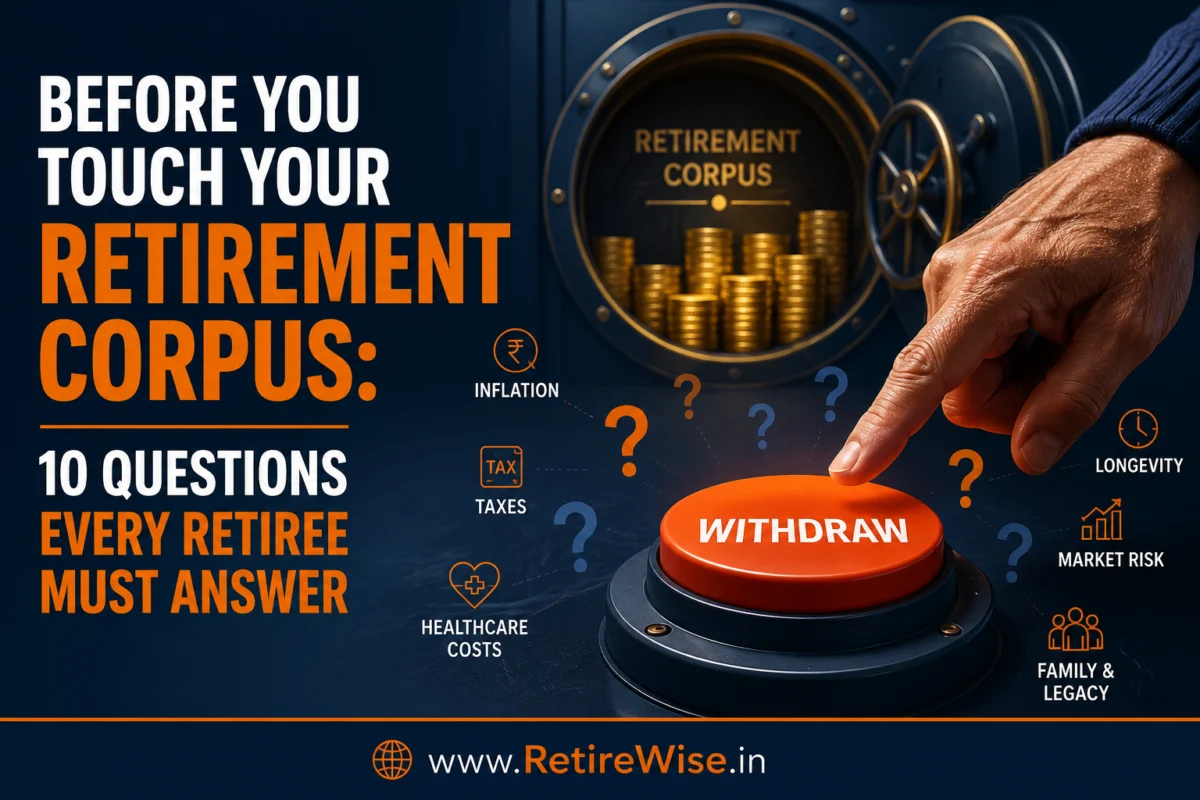
Recent insights from financial experts, including Hemant Beniwal of Retirewise, suggest that many diligent savers are entering retirement "completely unprepared for the second half of the game." While accumulating a corpus is a mathematical challenge of addition and time, withdrawal is a complex psychological and technical challenge of subtraction, market volatility, and diminishing time.
Main Facts: The Invisible Crisis of Retirement Management
The central crisis facing modern retirees is not necessarily a lack of funds, but a lack of a "decumulation strategy." Even those with substantial Employee Provident Fund (EPF) payouts and diversified portfolios often find themselves paralyzed when the monthly paycheck stops.
According to industry data, a significant portion of new retirees leave their life savings in low-yield savings accounts or fixed deposits (FDs) for years, fearing a wrong move. This "temporary" parking of funds often becomes permanent, leading to a "guaranteed slow loss" as inflation outpaces post-tax returns.
The core of the problem lies in the transition from Rupee Cost Averaging (buying more units when prices are low during the working years) to what experts call Reverse Rupee Cost Averaging. In retirement, selling assets to fund expenses during a market downturn permanently destroys capital, a phenomenon known as "Sequence of Returns Risk."
Chronology: The Lifecycle of a Retirement Strategy
To understand the complexity of this transition, one must look at the chronology of an investor’s journey:
1. The Accumulation Era (Ages 25–60)
During this 35-year window, time is the investor’s greatest ally. Errors in judgment or market crashes are mitigated by a steady salary and the ability to wait for a recovery. The primary goal is the "Number"—the total corpus required to quit working.
2. The Transition Point (The "EPF Moment")
Upon retirement, the "Number" is achieved. For many, this arrives as a large lump sum. This is the moment of maximum vulnerability. The investor must shift from a mindset of "growth" to one of "reliable cash flow" without any professional training for the latter.
3. The "Go-Go" Years (Ages 60–70)
In the first decade of retirement, spending is typically at its peak. Retirees are active, traveling, and fulfilling lifelong dreams. However, this is also when "Sequence of Returns Risk" is most dangerous. A market crash in these early years, combined with high spending, can deplete a corpus so severely that it never recovers.
4. The "Slow-Go" Years (Ages 70–80)
Physical activity naturally declines, and discretionary spending slows down. Many retirees mistakenly assume their financial planning is "done" at this stage, failing to realize that inflation is quietly eroding the purchasing power of their remaining assets.
5. The "No-Go" Years (Ages 80+)
Travel and leisure spending are replaced by ballooning healthcare costs. This is the phase where "Longevity Risk"—the risk of outliving one’s money—becomes a stark reality if the initial withdrawal strategy was flawed.
Supporting Data: The Math of Sustainable Withdrawals
The financial industry often references the "4% Rule"—the idea that an investor can safely withdraw 4% of their initial portfolio (adjusted for inflation) annually. However, new data suggests this rule is increasingly obsolete in high-inflation economies like India.
- The 3% Reality: Experts argue that due to India’s higher long-term inflation rates, a "safe" withdrawal rate is closer to 3%. A 1% difference may seem negligible, but over a 30-year horizon, it represents the difference between a comfortable legacy and financial insolvency.
- The Healthcare Inflation Gap: While general Consumer Price Index (CPI) inflation may hover around 6-7%, healthcare inflation in the region is estimated at 12-14%. Because medical costs consume a larger share of the budget in later years, a flat inflation model in retirement planning is fundamentally flawed.
- The Fixed Deposit Trap: A typical FD yielding 7% might seem safe. However, for an individual in the 30% tax bracket, the post-tax return is 4.9%. If personal inflation is 7%, the retiree is losing 2.1% of their purchasing power every year.
Official Responses: Why the Industry is Failing Retirees
The financial advisory industry has faced criticism for its heavy focus on accumulation over decumulation. There are several systemic reasons for this:
- Scalability: Accumulation strategies (SIPs, Diversified Mutual Funds) are easily scalable. Withdrawal strategies are deeply individual, requiring annual adjustments based on tax laws, health status, and market performance.
- Revenue Models: Most advisors are compensated based on Assets Under Management (AUM). In the withdrawal phase, AUM naturally declines, creating a disincentive for some firms to focus on aggressive spending strategies for their clients.
- The "SWP" Shortcut: Many professionals offer a Systematic Withdrawal Plan (SWP) as a complete strategy. Experts warn that an SWP is merely a mechanism, not a plan. It does not account for which asset to sell first or how to adjust when the market drops.
Implications: The Psychological and Structural Requirements of Retirement
The shift from building wealth to consuming it carries profound implications for the future of financial planning.
The Cognitive Decline Factor
Research consistently shows that financial decision-making capacity peaks in one’s 50s and begins a gradual decline in the 60s. Cruelly, "financial confidence" often remains high or even increases as actual ability declines. This creates a "perfect storm" where retirees make high-stakes decisions (like moving an entire corpus into a single "hot" investment) at the exact moment their judgment is most likely to be impaired.
The Need for "Withdrawal Guardrails"
A robust retirement plan must include predefined "guardrails." These are rules established in advance—while the retiree is at peak cognitive clarity—that dictate exactly how to behave during market volatility. For example, a guardrail might state: "If the portfolio drops by 20%, discretionary spending will be reduced by 10% until a recovery occurs." Without these rules, decisions are made emotionally under the stress of a falling market.
Tax-Efficient Sequencing
The order in which assets are liquidated is one of the most significant levers in retirement longevity. Drawing from taxable accounts versus tax-exempt accounts (like certain EPF portions or insurance payouts) can change the "burn rate" of a corpus by years. Retirees must view tax planning not as an annual event, but as a monthly withdrawal decision.
The Legacy of the Surviving Spouse
In many households, one partner (statistically often the male) handles the majority of financial decisions. A critical but overlooked implication of retirement planning is "survivorship readiness." A plan is not successful unless it is simple enough for the less-involved spouse to manage alone, or if a trusted advisor is already in place to provide continuity.
Conclusion: A Living Strategy
The transition into retirement is not a single event marked by a farewell party and a gold watch. It is the beginning of a 300-to-400-month journey that requires a "living" strategy.
As the data shows, the biggest threat to a retiree’s security is not the stock market, but the lack of a dynamic plan to navigate it. The "safe" choice—doing nothing or sticking to fixed deposits—is often the most dangerous choice of all. For the modern retiree, the goal has shifted: it is no longer about reaching the mountain peak of accumulation, but about the much more treacherous descent back down.
Strategic Checklist for Retirees:
- Do you have a documented withdrawal sequence (which asset to sell first)?
- Have you modeled your plan on 3% withdrawals rather than 4%?
- Are your healthcare inflation assumptions set at 12% or higher?
- Do you have written "guardrails" for market crashes?
- Is there a clear plan for your spouse to take over the income stream?
If the answer to more than two of these is "no," your retirement corpus—no matter how large—remains at risk.