Mumbai, [Date – e.g., October 10, 2026] – In the intricate landscape of personal finance, choosing the right savings instrument can significantly impact an individual’s financial health and goal achievement. Among the plethora of options available from commercial banks, Fixed Deposits (FDs) have long stood as a cornerstone of conservative investment strategies in India, revered for their safety and predictable returns. However, the traditional fixed deposit model has seen an evolution with the advent of the ‘Sweep-in’ or ‘Flexi’ FD, a hybrid product designed to offer the best of both worlds: higher interest rates than a savings account, coupled with enhanced liquidity.
This detailed analysis aims to unravel the fundamental differences between these two popular deposit schemes – the conventional Regular Fixed Deposit and its more agile counterpart, the Sweep-in Fixed Deposit. We will explore five critical distinctions encompassing liquidity, interest rate mechanisms, withdrawal rules, associated charges, and suitability for various financial goals. Furthermore, we will delve into the specific offerings and policies of major Indian banks like State Bank of India (SBI), HDFC Bank, and ICICI Bank, providing a comprehensive guide for investors seeking to optimize their savings and align their choices with their unique financial objectives.
The Foundation of Financial Security: Understanding Fixed Deposits
Fixed deposits have historically been a preferred choice for Indian households looking for secure, stable, and relatively higher returns on their savings compared to standard savings accounts. Their appeal lies in their simplicity and the assurance of capital preservation.
Understanding Regular Fixed Deposits
A Regular Fixed Deposit is a financial instrument where an investor deposits a lump sum of money with a bank for a predetermined period, known as the tenure. In return, the bank pays a fixed rate of interest, which is typically higher than that offered on a savings account. The interest can be paid out periodically (monthly, quarterly, half-yearly, annually) or compounded and paid at maturity along with the principal.
Key Characteristics of a Regular FD:
- Lump Sum Investment: Requires a one-time deposit of a specific amount.
- Fixed Tenure: The investor commits to keeping the funds locked for a chosen period, ranging from a few days to several years.
- Fixed Interest Rate: The interest rate is decided at the time of opening the FD and remains constant for the entire tenure, irrespective of market fluctuations.
- Guaranteed Returns: Subject to bank solvency and Deposit Insurance and Credit Guarantee Corporation (DICGC) coverage (up to ₹5 lakhs per depositor per bank), returns are assured.
- Limited Liquidity: Accessing funds before maturity typically involves penalties.
Regular FDs are ideal for individuals saving for a defined future goal, such as a down payment for a house, a child’s education, retirement planning, or any objective where funds can remain untouched for a specific duration.
The Emergence of Sweep-in Fixed Deposits: Bridging Liquidity Gaps
While traditional FDs offer attractive returns, their primary drawback has always been the lack of liquidity. In an emergency, breaking an FD prematurely often means forfeiting a portion of the accrued interest as a penalty. To address this need for both higher returns and accessible funds, banks introduced the Sweep-in Fixed Deposit, often referred to as a "Flexi FD" or "Auto-Sweep Facility."
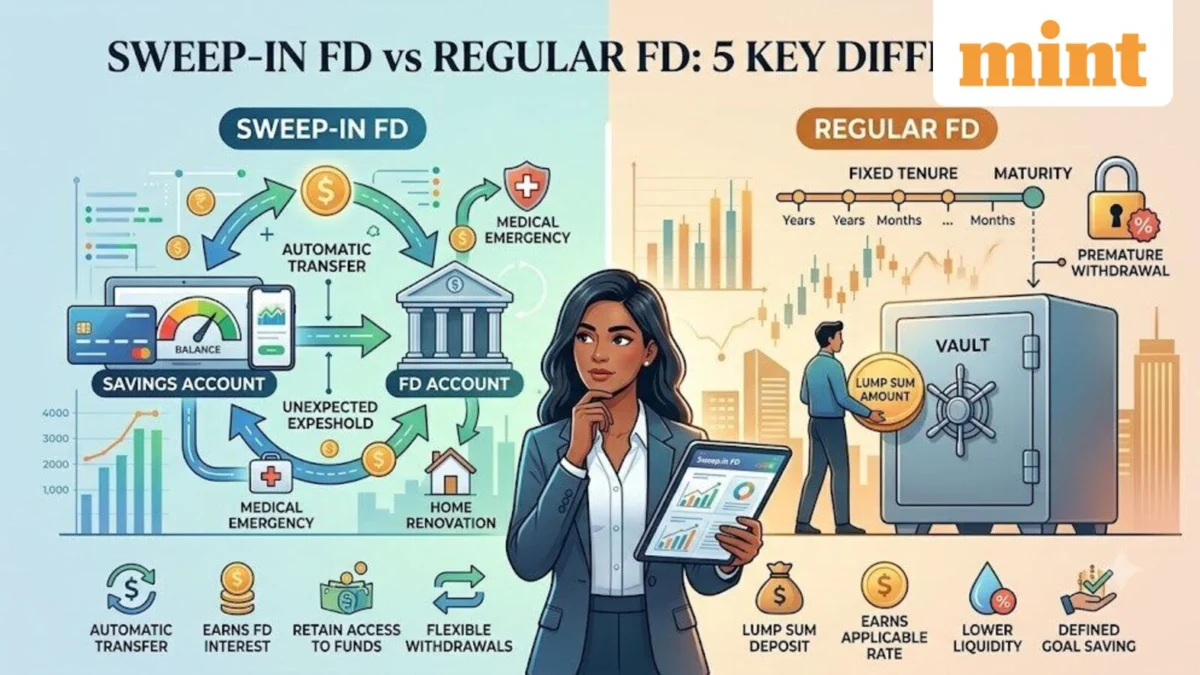
A Sweep-in FD is essentially a hybrid product that links a customer’s savings or current account to a fixed deposit. It operates on an automated mechanism: once the balance in the linked savings account exceeds a predefined threshold, the surplus amount is automatically "swept" into a fixed deposit, earning a higher interest rate. Conversely, if the balance in the savings account falls below a minimum threshold due to transactions, funds are automatically "swept back" from the FD to cover the deficit, ensuring liquidity without breaking the entire fixed deposit.
Key Characteristics of a Sweep-in FD:
- Automatic Fund Transfer: Surplus funds above a threshold are automatically moved to an FD.
- Dynamic Liquidity: Funds are automatically moved back from the FD to the savings account when needed, maintaining liquidity.
- Earns FD Rates on Surplus: Only the swept amount earns the FD interest rate, while the base savings account balance earns the standard savings rate.
- Convenience: Automates the process of optimizing idle cash.
Sweep-in FDs are particularly beneficial for individuals who maintain substantial balances in their savings accounts but also require ready access to funds for regular expenses or unforeseen emergencies.
The Evolution of Savings: A Chronological Perspective
The journey of fixed deposits in India reflects the evolving needs of its banking customers. Historically, FDs were simple, straightforward instruments, designed to encourage long-term savings in a capital-scarce economy. Their primary purpose was to mobilize funds for productive investments by offering a predictable return, fostering a culture of financial discipline.
However, as the Indian economy matured and consumer lifestyles became more dynamic, the need for liquidity became paramount. The traditional FD, with its rigid lock-in periods and punitive premature withdrawal clauses, often left depositors in a dilemma: sacrifice higher returns for liquidity, or compromise liquidity for better interest.
This growing demand for flexibility, especially from salaried individuals, small business owners, and those managing an emergency fund, prompted banks to innovate. The concept of "sweep-in" facilities began to gain traction in the early 2000s, emerging as a smart solution. It allowed customers to enjoy the best of both worlds – the high liquidity of a savings account for day-to-day transactions and the superior returns of a fixed deposit for their idle funds. This evolution wasn’t just a product tweak; it represented a significant shift in banking philosophy, moving towards more customer-centric and flexible financial solutions. The sweep-in FD, therefore, stands as a testament to the banking sector’s responsiveness to market demands for enhanced convenience and optimized wealth management.
Diving Deeper: Five Key Distinctions and Supporting Data
While both Regular and Sweep-in FDs serve the fundamental purpose of growing savings, their operational mechanics and suitability diverge significantly. Understanding these differences is crucial for making an informed investment decision.
1. Liquidity and Accessibility
- Regular FD: Designed for capital preservation over a fixed term, regular FDs inherently offer limited liquidity. Once funds are deposited, they are typically locked in until maturity. Accessing the money before the specified tenure usually necessitates a premature withdrawal, which often results in penalties and a reduced interest rate. This makes them unsuitable for immediate or emergency financial needs.
- Sweep-in FD: This is where sweep-in FDs shine. They offer superior liquidity by automatically transferring funds back to the linked savings account when the balance falls below the threshold. This "reverse sweep" ensures that the customer always has sufficient funds for transactions without manually breaking the FD. While the FD component is technically broken for the withdrawn amount, the remaining FD continues to earn interest, minimizing the impact of partial withdrawals. The amount withdrawn from the FD component and the units in which it is withdrawn depend on the bank’s specific rules (e.g., in multiples of ₹1,000 or ₹5,000).
2. Interest Rates and Return Calculation
- Regular FD: The interest rate for a regular FD is fixed at the time of deposit and applies to the entire lump sum for the chosen tenure. This rate is generally higher than what sweep-in FDs might effectively yield if frequent withdrawals occur. Interest can be compounded periodically, leading to higher effective returns over longer tenures. For instance, if a bank offers 6.50% p.a. for a 2-year FD, the entire deposited amount earns this rate.
- Sweep-in FD: The swept-in portion earns the applicable FD rate for the corresponding tenure. However, the overall effective return can be complex. Only the surplus amount that gets converted into an FD earns the higher rate, while the base balance in the savings account continues to earn the lower savings account interest. Furthermore, if funds are frequently swept back from the FD, the interest earned on those withdrawn portions might be impacted by premature withdrawal penalties, or the interest calculation might revert to the savings account rate for the period it was held as an FD. This means that while the stated FD rate might be attractive, the actual average return on the total funds (savings + FD) might be lower than a fully committed regular FD.
3. Withdrawal and Premature Closure Rules
- Regular FD: Premature closure of a regular FD typically incurs a penalty, often a reduction of 0.50% to 1.00% on the applicable interest rate (the rate for the period the FD was held or the contracted rate, whichever is lower). Some banks might also not pay any interest if the FD is closed within a very short period (e.g., 7 days). The entire FD amount is closed, and the penal interest is calculated on the full sum.
- Sweep-in FD: For sweep-in FDs, withdrawals are typically made in specific units (e.g., ₹1,000 or ₹5,000) from the FD component. Banks often follow a ‘Last-In, First-Out’ (LIFO) method for reverse sweeps, meaning the most recently created FD components are broken first. Each partial withdrawal from the FD component may be treated as a premature withdrawal, attracting a penalty on that specific withdrawn unit. However, the remaining FD balance continues to earn the contracted rate. This granular approach to withdrawals makes sweep-in FDs more flexible for managing fluctuating cash needs without completely derailing the higher interest earnings on the bulk of the funds.
4. Charges and Conditions
- Regular FD: Beyond premature withdrawal penalties, regular FDs generally do not involve significant ongoing charges. There are no universal processing fees, but banks may have specific rules regarding minimum deposit amounts, which vary widely (e.g., ₹1,000, ₹5,000, or ₹10,000).
- Sweep-in FD: Since sweep-in FDs are linked to a savings account, customers must adhere to the minimum balance requirements of the linked savings account. Failure to maintain this minimum balance can result in service charges. Additionally, as noted, premature withdrawal penalties can apply to the portions swept back from the FD. Some banks might also have a minimum threshold for the amount that can be swept into an FD (e.g., ₹10,000 or ₹25,000), and a minimum balance that must remain in the savings account before the sweep occurs.
5. Suitability and Target Audience
- Regular FD: Best suited for conservative investors who have a clear financial goal with a specific timeline and do not foresee needing access to their funds before maturity. Examples include saving for retirement, a child’s higher education, purchasing a major asset in the future, or building a long-term wealth corpus where capital safety and predictable returns are paramount. They are ideal for individuals who can commit to locking in their funds for a chosen period without interruption.
- Sweep-in FD: Ideal for individuals who maintain significant surplus balances in their savings accounts but also require convenient and immediate access to funds for regular payments, unforeseen expenses, or an emergency fund. This includes salaried professionals with fluctuating monthly expenses, small business owners who need to manage working capital efficiently, or anyone looking to earn more on their idle cash without sacrificing liquidity for an emergency fund. It offers a practical solution for optimizing short-to-medium term savings.
Beyond the Five: Other Crucial Considerations
When comparing these two FD types, investors should also factor in:

- Tenure Options: Both offer a range of tenures, but sweep-in FDs often create multiple smaller FDs of varying tenures, which can make tracking slightly more complex.
- Nomination Facility: Both types typically offer nomination facilities, ensuring smooth transfer of funds to beneficiaries.
- Tax Implications: Interest earned on both FDs is taxable as per the individual’s income tax slab. Tax Deducted at Source (TDS) applies if interest income exceeds a certain threshold (currently ₹40,000 for general citizens and ₹50,000 for senior citizens in a financial year). Form 15G/15H can be submitted to avoid TDS if eligible.
- Loan Against FD: Regular FDs are commonly used as collateral for loans, offering relatively lower interest rates. While it’s possible to take a loan against the FD component of a sweep-in facility, the dynamic nature of the underlying FD components might make the process slightly more nuanced compared to a single, stable regular FD.
Bank-Specific Offerings and Regulatory Framework
The operational details of both sweep-in and regular FDs can vary significantly between banks. It is imperative for investors to consult the specific terms and conditions of their chosen financial institution.
State Bank of India (SBI)
SBI offers its popular Multi-Option Deposit Scheme (MODS), which is a classic example of a sweep-in facility. Under MODS:
- Investors can link their savings or current account to this scheme.
- The minimum auto-sweep threshold typically starts at ₹50,000, meaning any amount above this in the linked account is swept into an FD.
- A minimum balance, often around ₹35,000, must be maintained in the savings account.
- Deposits under MODS start from ₹15,000 and are made in multiples of ₹5,000.
- Reverse-sweep withdrawals are also made in units of ₹5,000, ensuring granular liquidity.
- SBI’s regular FD rates broadly range from 3.05% to 6.40% per annum, depending on the tenure. The MODS FD component earns these applicable rates, subject to premature withdrawal clauses.
HDFC Bank
HDFC Bank also offers sweep-in facilities (e.g., MoneyMaximizer Fixed Deposit) alongside its range of regular FDs. Their terms specify that premature withdrawals, including those from sweep-in FDs and partial withdrawals, may attract a 1% reduction in the applicable interest rate. This penalty applies to the portion of the FD that is withdrawn prematurely. Investors should note that these rules are subject to change and depend on the specific type of fixed deposit invested and the bank’s prevailing policies. Linked-account balance requirements and other service charges also continue to apply for sweep-in facilities.
ICICI Bank
As of October 5, 2026, ICICI Bank’s fixed deposits offer rates up to 6.50% for general customers and 7.10% for senior citizens on eligible tenures. ICICI Bank also provides sweep-in facilities (e.g., Flexicash). While these attractive rates apply to the FD component of a sweep-in facility, the effective return can differ if funds are frequently swept back due to premature withdrawal penalties on those portions. It is crucial for customers to review the detailed terms and conditions, including minimum sweep-in amounts, minimum savings account balance, and specific premature withdrawal penalties for their Flexicash or similar products.
Regulatory Framework
It’s important to remember that all FDs offered by Scheduled Commercial Banks in India are insured by the Deposit Insurance and Credit Guarantee Corporation (DICGC), a subsidiary of the Reserve Bank of India (RBI). This insurance covers each depositor up to ₹5 lakhs for both principal and interest amount in each bank. This regulatory backing provides an additional layer of security for investors, irrespective of whether they choose a regular or a sweep-in FD. The RBI’s monetary policy also significantly influences the prevailing interest rates offered by banks on both types of FDs.
Strategic Financial Planning: Making the Right Choice
The decision between a sweep-in FD and a regular FD is not a matter of one being inherently "better" than the other. Instead, it hinges entirely on an individual’s unique financial reality, liquidity requirements, risk appetite, and long-term economic objectives.
Building an Emergency Fund
For individuals building an emergency fund, a sweep-in FD can be an excellent choice. It allows the emergency corpus to earn higher interest than a savings account while remaining readily accessible in times of need, such as a medical emergency, job loss, or unforeseen home repairs. The automatic nature ensures that funds are optimized without constant manual intervention.
Optimizing Idle Cash
Those who typically maintain a high balance in their savings account but don’t actively use all of it for monthly expenses can significantly benefit from a sweep-in facility. It ensures that idle cash is put to work, generating better returns, without compromising the flexibility needed for day-to-day transactions.
Long-Term Goal Planning
Conversely, for clearly defined, long-term goals where liquidity is not a primary concern, a regular FD might offer marginally better returns due to the absence of potential premature withdrawal penalties on frequently accessed portions. For instance, if you are saving for a child’s college tuition five years down the line, and you are confident you won’t need the money before then, a regular FD provides predictable growth.
Diversification and Risk Management
Both types of FDs represent low-risk investments. However, incorporating both into a diversified savings portfolio can be a prudent strategy. A portion of savings can be allocated to a sweep-in FD for liquidity and emergency needs, while another portion can be invested in regular FDs for longer-term, higher-yielding goals.
Conclusion: An Informed Decision for Financial Well-being
In the dynamic world of personal finance, understanding the nuances of available products is paramount. Both sweep-in and regular fixed deposits offer distinct advantages, catering to different financial profiles and objectives. While regular FDs remain the bedrock for secure, long-term wealth creation with predictable returns, sweep-in FDs have emerged as a sophisticated solution for optimizing liquidity without sacrificing the opportunity for higher interest earnings on surplus funds.
Before committing to either option, aspiring investors must conduct thorough due diligence. This includes comparing the latest interest rates across various banks, understanding their specific terms for premature withdrawals and associated penalties, and meticulously reviewing any linked-account requirements or service charges.
Ultimately, the investment decision should be a deeply personal one, guided by how one intends to utilize their funds, their comfort level with liquidity trade-offs, and their overarching financial aspirations. In instances of doubt or hesitation, seeking guidance from a certified financial advisor is always a wise approach. A professional can provide tailored advice, ensuring that your investment choices are strategically aligned with your unique long-term financial objectives, paving the way for enhanced financial well-being.
Disclaimer: This article is intended for general informational purposes only and does not constitute financial advice. Fixed deposit interest rates, withdrawal rules, and associated charges are subject to change and vary by bank and specific product. Readers are strongly advised to verify the latest terms and conditions directly with their bank and consult a qualified financial adviser before making any investment decisions.