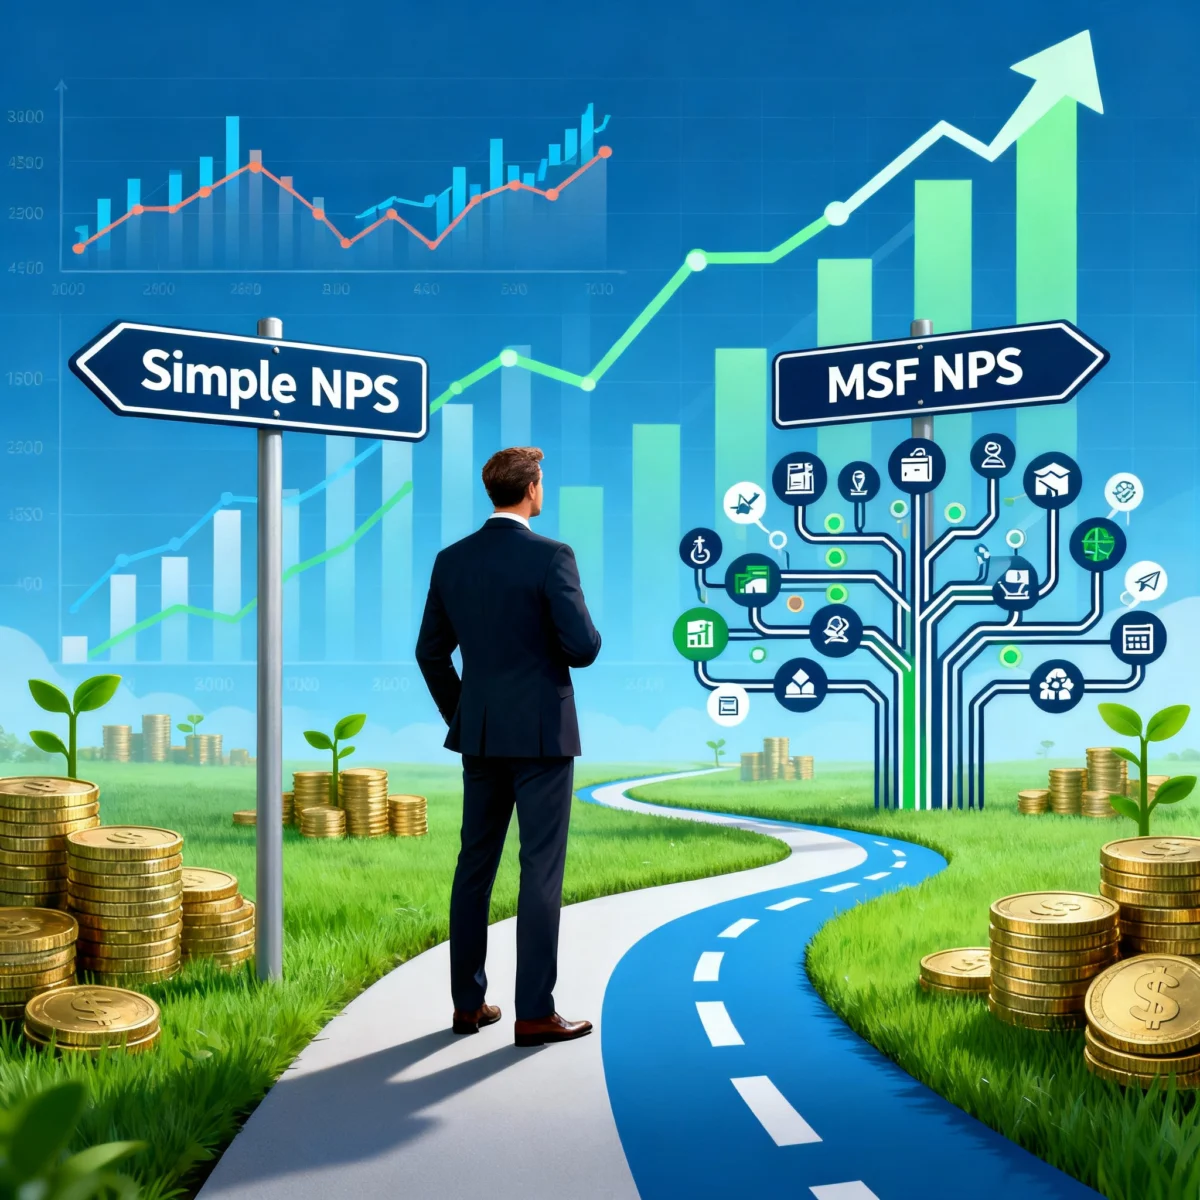
New Delhi, India – The National Pension System (NPS), long lauded for its low costs and straightforward approach to retirement savings, is undergoing its most significant transformation to date. The Pension Fund Regulatory and Development Authority (PFRDA) has unveiled the Multiple Scheme Framework (MSF), a move designed to inject greater choice and flexibility into the platform. While proponents herald it as a necessary evolution to attract a wider investor base, critics question whether this diversification risks muddying the waters of a product that was once celebrated for its inherent simplicity.
For years, NPS subscribers were confined to a binary choice: either an "Active Choice" or an "Auto Choice" scheme. These were often referred to as "common schemes," offering a generalized approach to asset allocation. The Active Choice allowed individuals to manually select their exposure to equity, government bonds, and corporate bonds, albeit with a strict cap of 75% on equity. The Auto Choice, on the other hand, automatically adjusted asset allocation based on the subscriber’s age, employing a lifecycle fund approach. This structured, albeit limited, framework was a cornerstone of NPS’s appeal: simple, transparent, and cost-effective.
However, this simplicity has arguably been a double-edged sword, contributing to NPS’s struggle to compete with the widespread popularity of mutual funds and insurance products, which often offer a broader spectrum of investment options and perceived accessibility. Recognizing this challenge, the PFRDA’s MSF aims to bridge this gap by empowering Pension Fund Managers (PFMs) – such as ICICI, HDFC, SBI, UTI, and Kotak – to design and launch a diverse array of new schemes.
The Dawn of Diversification: What’s New Under the MSF?
The Multiple Scheme Framework introduces several key departures from the existing NPS structure, fundamentally altering the investment landscape for subscribers:
- Expanded Equity Exposure: A significant shift is the potential for equity exposure to reach up to 100% within certain MSF schemes. This contrasts sharply with the 75% cap in the traditional Active/Auto schemes, offering a higher risk-reward proposition for investors seeking aggressive growth.
- Multi-Scheme Investment: Subscribers will no longer be restricted to a single scheme. The MSF allows individuals to invest in multiple schemes simultaneously, including a combination of MSF schemes and the existing common schemes. This opens up avenues for tailored portfolio construction.
- Targeted Scheme Design: PFMs are granted considerable latitude to create schemes catering to specific demographic and occupational segments. This includes developing options for particular age groups (e.g., young earners, middle-aged individuals), diverse segments, or specific occupations like gig workers, the self-employed, entrepreneurs, and consultants. This "blank canvas" approach, subject to PFRDA approval, allows for highly customized investment solutions.
- Risk Variants within Schemes: For each newly launched scheme, PFMs are mandated to offer both high-risk and moderate-risk variants. The introduction of a low-risk variant is optional. This ensures that even within a targeted scheme, investors can select a risk profile that aligns with their comfort level.
Navigating the New Landscape: Key Features and Rules
The introduction of MSF brings with it a new set of features and rules that subscribers need to understand:
| Feature | Existing NPS (Common Schemes) | NPS with MSF |
|---|---|---|
| Number of Schemes Allowed | Limited to one scheme per subscriber (Active or Auto Choice) | Can hold multiple schemes at one time. Can also hold MSF schemes and common schemes concurrently. |
| Equity Exposure Cap | Maximum 75% equity exposure | Up to 100% equity exposure allowed in high-risk schemes. |
| Vesting Period | Age of 60 years or superannuation | Minimum 15 years vesting period. This can be longer if decided by the PFM. |
| Switching Funds | Allowed between Active and Auto schemes | Switching allowed within MSF schemes only post 15-year vesting. Switch from MSF to common scheme (Active/Auto) permitted before vesting. |
| Expense Ratio | Capped at 0.1% p.a. | Capped at 0.3% p.a. for MSF schemes. Capped at 0.1% p.a. for common schemes. |
| Investor Segmentation | Generalized schemes for all subscribers | PFMs can launch schemes targeted at specific age groups, professions, and risk profiles. |
| Mandatory Annuity Purchase | Same for both. Currently at 40% for regular exit. 80% for premature exit. PFRDA proposed reducing from 40% to 20% for regular exit. | Same for both. Currently at 40% for regular exit. 80% for premature exit. PFRDA proposed reducing from 40% to 20% for regular exit. |
| Tax Implications | Tax rules are the same. Withdrawals up to 60% tax-exempt under Section 10(12A). | Tax rules are the same. Withdrawals up to 60% tax-exempt under Section 10(12A). |
| Flexibility and Complexity | Simple, easy to understand | More choice but increased complexity. |
Exit Routes and Tax Implications: A Continued Focus
The PFRDA has also addressed the crucial aspects of regular and premature exits, ensuring that the rules for MSF schemes align with the existing framework, with some notable differences in the definition of a "regular exit."
Regular Exit:
- Existing NPS: A regular exit occurs at or beyond the age of 60 or at the time of superannuation.
- MSF Schemes: A regular exit can occur after the completion of a vesting period of 15 years. This means subscribers do not have to wait until age 60 to access their funds, opening up possibilities for early financial planning.
Premature Exit:
- For both common and MSF schemes, a premature exit requires at least 80% of the corpus to be used for purchasing an annuity, with the remaining 20% available as a lump sum withdrawal.
Proposed Changes to Withdrawal Limits:
The PFRDA has put forth a significant proposal to increase the lump sum withdrawal limit from 60% to 80% for regular exits, concurrently reducing the mandatory annuity purchase from 40% to 20%. While this proposal is expected to be approved, it’s crucial to remember the prevailing tax regulations. Section 10(12A) of the Income Tax Act currently exempts lump sum withdrawals up to 60% of the accumulated corpus from taxation. Any withdrawal exceeding this 60% threshold, even if permitted by PFRDA, will be subject to the individual’s income tax slab rate unless the government revises the tax-exempt limit.
Illustrating the Shift: From Simplicity to Spectrum
To truly grasp the magnitude of the MSF, consider a hypothetical scenario:
Until Now:
An investor would choose either an Active or Auto scheme. Under Active Choice, they could manually allocate between Equity (E), Government Bonds (G), and Corporate Bonds (C), with E capped at 75%. Each PFM offered a single E, C, and G fund. Auto Choice presented four lifecycle funds with age-based asset allocation. This was the extent of the choice.
Under the MSF Framework:
The landscape transforms dramatically. An investor could potentially invest in:
- MSF-A: A high-risk scheme where a PFM launches a fund investing 100% in mid-cap equities. This scheme might have a 15-year vesting period.
- MSF-B: A moderate-risk scheme from the same PFM that allocates to a balanced fund or a 50:50 mix of equity and government debt funds. This could also have a 15-year vesting period.
- Existing Common Scheme: The investor could simultaneously hold an Active or Auto choice scheme for their long-term retirement goals, separate from their MSF investments.
This multi-pronged approach allows for strategic financial planning beyond just retirement. For instance, an investor starting at age 35 with MSF-A (15-year vesting) could access their funds at age 50, aligning with potential life goals like children’s higher education. With the proposed withdrawal changes, they could potentially access 80% of their corpus, with 60% tax-free and the remaining 20% taxed at their slab rate. This flexibility, while potentially beneficial for freelancers or those with uncertain career paths, raises questions about NPS’s core purpose and its tax advantages.
PFRDA’s Strategic Gambit: Addressing NPS’s Traction Deficit
The introduction of the MSF appears to be a strategic move by the PFRDA to address NPS’s persistent challenge in gaining widespread traction comparable to its more established financial product counterparts. The regulator likely recognizes that while NPS offers compelling low costs and tax benefits, its limited product offerings have hampered its appeal.
Several factors have likely contributed to this situation:
- Limited Investment Choices: The inherent simplicity, while a virtue, has also been a constraint, failing to cater to the diverse risk appetites and financial goals of a broader investor base.
- Perceived Lack of Flexibility: The long lock-in periods and the structure of exits have made NPS seem less adaptable to evolving life circumstances compared to mutual funds.
- Taxation Nuances: While NPS offers tax benefits, the complex tax treatment of lump sum withdrawals and the mandatory annuity component can be confusing for investors. The PFRDA’s proposed changes aim to simplify this, but the underlying tax laws remain a crucial factor.
- Competition from Other Pension Products: The emergence of other pension schemes, including the Unified Pension Scheme (UPS), might have drawn subscribers away from NPS.
The MSF, therefore, is an attempt to inject "more spice" and "exoticism" into the NPS product, making it more attractive and competitive. The PFRDA’s intention is to create a more conducive environment for the growth of the pension industry.
The Double-Edged Sword of Choice: Simplicity vs. Complexity
While the increased choice and flexibility offered by MSF are undoubtedly positive developments for many, they also introduce a significant degree of complexity. The PFRDA’s decision to allow PFMs to launch a wide array of schemes, each with its own risk variants and vesting periods, means that selecting an NPS investment will now require a level of due diligence comparable to choosing a mutual fund. This stands in stark contrast to NPS’s original promise of simplicity.
The expense ratio for MSF schemes has been capped at 0.3% per annum, which, while still lower than many actively managed mutual funds, is a notable increase from the 0.1% cap on common schemes. This marginal increase in cost, coupled with the enhanced complexity, leads to a critical question: if NPS begins to mirror the investment flexibility and product diversity of mutual funds, does it still warrant the unique tax benefits it currently enjoys, benefits that are not extended to mutual fund investments?
The Road Ahead: Navigating the New NPS Ecosystem
The introduction of the Multiple Scheme Framework represents a pivotal moment for the National Pension System. It is a bold attempt to revitalize a product that has struggled to capture the imagination of a significant segment of the investing public. The increased flexibility, higher equity exposure potential, and targeted scheme design offer compelling new avenues for investors.
However, the PFRDA faces the delicate task of balancing this newfound flexibility with the core tenets that made NPS attractive in the first place: simplicity and cost-effectiveness. The success of MSF will hinge on its ability to deliver enhanced investor choice without alienating the existing subscriber base or creating a labyrinthine investment selection process.
What should investors do?
For existing NPS investors who are comfortable with the current structure, the MSF is voluntary. There is no compulsion to switch or engage with the new framework. Sticking with the existing common schemes remains a perfectly viable option.
For those considering NPS or looking to optimize their existing investments, a thorough understanding of the MSF is crucial. It necessitates a deeper dive into the new schemes offered by PFMs, a careful assessment of risk profiles, and a clear understanding of the exit and tax implications.
The PFRDA’s MSF is a significant evolution, promising to transform NPS into a more dynamic and adaptable investment vehicle. Whether this evolution leads to greater investor participation or dilutes the product’s core strengths remains to be seen. The coming months will be critical in observing how investors react to this paradigm shift and how effectively the PFRDA manages the delicate balance between choice and simplicity in the evolving landscape of retirement savings in India.
Disclaimer: Registration granted by SEBI, membership of BASL, and certification from NISM in no way guarantee performance of the intermediary or provide any assurance of returns to investors. Investment in securities market is subject to market risks. Read all the related documents carefully before investing.
This post is for educational purposes alone and is NOT investment advice. This is not a recommendation to invest or NOT invest in any product. The securities, instruments, or indices quoted are for illustration only and are not recommendatory. My views may be biased, and I may choose not to focus on aspects that you consider important. Your financial goals may be different. You may have a different risk profile. You may be in a different life stage than I am in. Hence, you must NOT base your investment decisions based on my writings. There is no one-size-fits-all solution in investments. What may be a good investment for certain investors may NOT be good for others. And vice versa. Therefore, read and understand the product terms and conditions and consider your risk profile, requirements, and suitability before investing in any investment product or following an investment approach.