For millions of homeowners, a home loan is the single largest financial commitment they will ever undertake. With interest rates fluctuating in response to central bank policies and broader economic cycles, the dream of owning a home can sometimes feel burdened by the weight of a long-term, high-interest debt. This has popularized the concept of the "home loan balance transfer"—a financial maneuver that allows borrowers to shift their outstanding debt from one lender to another.
While many view this as a one-time "reset button," the reality is more nuanced. Can you switch lenders multiple times? Is it a sound financial strategy, or does it invite a cascade of hidden costs that negate the interest savings? As we delve into the mechanics of mortgage refinancing, we examine the eligibility, the hidden arithmetic, and the long-term implications of becoming a "serial switcher."
The Mechanics: What is a Home Loan Balance Transfer?
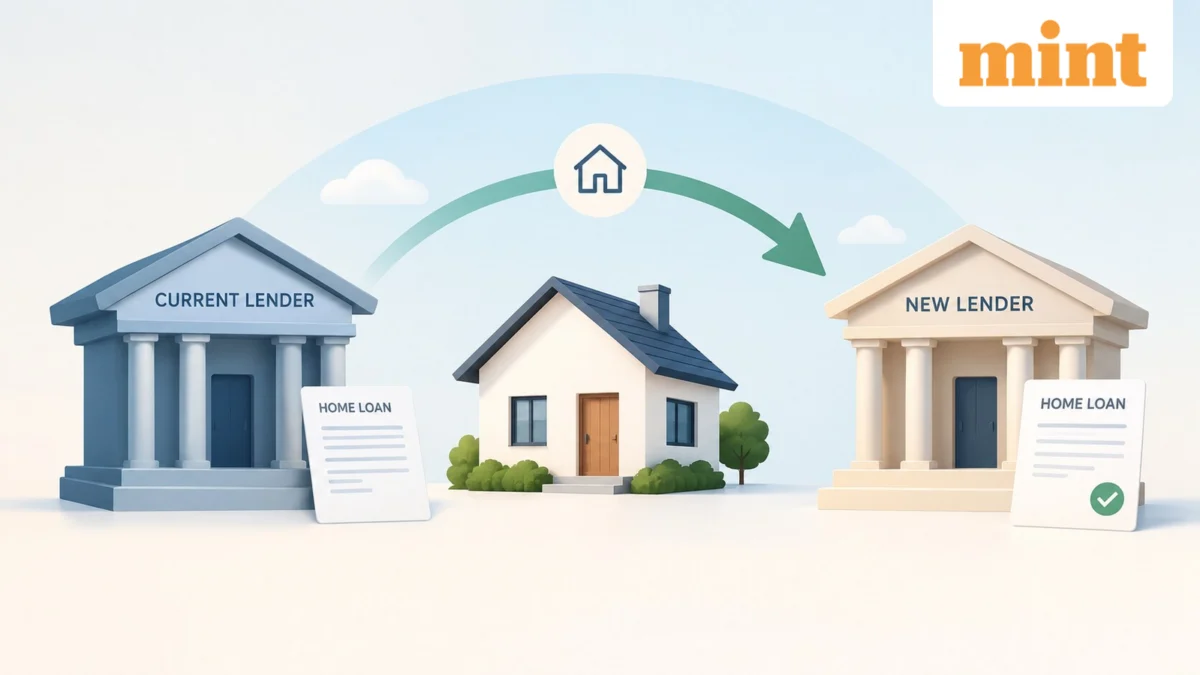
At its core, a home loan balance transfer is a refinancing mechanism. When a borrower finds that their current lender’s interest rate is no longer competitive—or that a rival institution is offering a significantly lower rate—they may apply for a balance transfer.
The process is effectively treated as a new loan application. The new lender conducts a thorough assessment of the borrower’s current creditworthiness, property valuation, and repayment history. If the application is approved, the new lender pays off the entire outstanding principal amount to the original bank. The borrower then begins a new repayment schedule with the new lender, ideally at a lower interest rate, which serves to reduce the monthly Equated Monthly Installment (EMI) or shorten the remaining loan tenure.
Breaking the Myth: Can You Switch Multiple Times?
A common misconception in personal finance is that a borrower is "locked" into their chosen lender after a single transfer. There is no legal or regulatory limit on the number of times you can transfer a home loan.
In theory, if a borrower consistently finds a lender offering a better interest rate—and maintains a strong credit score—they could move their loan multiple times over the course of its 15, 20, or 30-year tenure. However, the absence of a legal cap does not imply that such behavior is always advisable. Every time a loan is transferred, the borrower incurs new administrative costs and undergoes a fresh underwriting process.
Chronology of a Typical Transfer
- Market Monitoring: The borrower identifies a lender offering a significantly lower interest rate (often a spread of 50 to 100 basis points).
- Due Diligence: The borrower calculates the "break-even point"—the time it takes for the interest savings to exceed the transfer costs.
- The Application: A formal application is filed with the new lender.
- Underwriting: The new lender reviews the property documents and the borrower’s current financial standing.
- Foreclosure: The new lender disburses funds to the existing bank to close the account.
- Commencement: The new loan structure begins.
The Financial Calculus: Is It Worth the Effort?
To determine if a switch is warranted, one must look past the alluring "lower interest rate" headline. Consider a borrower with an outstanding principal of ₹25 lakh at a 7% interest rate for 20 years. The total interest burden is approximately ₹21.5 lakh. If a competitor offers a 6% rate, the interest burden drops to ₹18 lakh, a saving of ₹3.5 lakh.
However, this calculation ignores the "friction costs." When deciding to switch, borrowers must account for:
1. Processing Fees
Much like the initial loan, the new lender will charge a processing fee, which can range from 0.5% to 1% of the loan amount. On a large balance, this is a significant upfront expense that must be recovered through monthly savings.
2. Legal and Administrative Charges
Transferring a loan involves fresh documentation, property title verification, and stamp duty requirements in certain jurisdictions. These costs can eat into the margins of your savings.
3. Prepayment Penalties
Under current guidelines issued by the Reserve Bank of India (RBI), banks are generally prohibited from charging prepayment penalties on floating-rate home loans. However, if your loan is on a fixed-rate basis—a rarity in many modern markets but still present in older contracts—lenders can legally impose a penalty of up to 2% of the outstanding balance. Always consult your existing loan agreement before initiating a transfer.

When Should You Consider a Switch?
Refinancing should not be treated as a hobby, but as a surgical financial intervention. You should consider a transfer only when:
- The Interest Differential is Substantial: A marginal reduction of 0.10% is rarely worth the administrative headache and processing fees. Experts generally suggest that a spread of at least 0.50% to 0.75% is required to make the switch financially viable.
- The Remaining Tenure is Long: If you have only two years left on a 20-year loan, the total interest savings from a rate drop will likely be dwarfed by the upfront processing fees. The math works best in the early-to-mid stages of the loan tenure.
- Improved Terms and Services: Sometimes, the motivation to switch goes beyond the interest rate. A new lender might offer superior digital tools, better customer service, or the ability to secure a "top-up" loan for home renovations or other personal needs.
- Improved Credit Profile: If your credit score has improved significantly since you first took the loan, you are now a "prime" borrower. You can leverage this to negotiate better rates not just with new banks, but often by asking your existing lender to match market rates—a process known as an internal rate reset.
The Implications: What You Must Know
While the prospect of saving lakhs of rupees is enticing, the implications of frequent switching are often overlooked.
The Impact on Credit Scores
Every time you apply for a new loan, the lender performs a "hard inquiry" on your credit report. Multiple inquiries in a short span of time can negatively impact your credit score. If you switch lenders too frequently, you may find that your creditworthiness appears unstable, potentially making it harder to secure future credit (such as auto loans or credit cards) at favorable rates.
The Opportunity Cost
Time is money. The process of applying for a new loan, collecting documents, coordinating between two banks, and ensuring the original mortgage lien is released can take weeks. Borrowers must weigh whether the time invested in the transfer process could be more productively spent elsewhere.
The Risk of "Hidden" Terms
New lenders often lure customers with "teaser" rates that are only valid for a limited period before resetting to a higher rate. Always read the fine print. Ensure that the lower interest rate is not contingent upon purchasing bundled products like life insurance or investment plans that you do not need.
Expert Perspective: A Strategic Approach
Financial analysts at major institutions like Kotak Mahindra Bank and ICICI Bank emphasize that the decision to transfer must be data-driven. According to internal reports, the most successful borrowers are those who conduct an annual audit of their loan accounts.
"The goal is not to have the lowest rate for one month, but to have a sustainable, manageable EMI over the life of the asset," says one financial advisor. "If your bank is unwilling to lower your rate, and a reputable competitor is offering a significantly better deal with clear terms, then a transfer is a rational economic decision. But do not jump at every minor rate change."
Internal vs. External Transfers
Before you apply to a new bank, try a "retention strategy" with your current lender. Contact your relationship manager and inform them that you are considering a transfer due to competitive offers. Many banks have a formal process to reset interest rates for existing customers to prevent them from moving to a competitor. This "internal" switch avoids all the hassle of documentation and processing fees while achieving the same goal.
Conclusion: The Path Forward
The ability to transfer a home loan multiple times is a powerful tool for the modern borrower. It provides a safeguard against stagnation and keeps lenders competitive. However, it is a tool that requires precision.
Before embarking on a transfer, create a simple spreadsheet. List the total cost of the transfer (processing fees, legal fees, etc.) and calculate the total savings over the remaining life of the loan. If the savings do not comfortably exceed the costs, remain where you are.
Ultimately, your home loan should be an instrument that facilitates your life, not one that dictates your financial stress. By understanding the costs, the risks, and the strategic timing of a balance transfer, you can ensure that you are paying only what you owe, and not a penny more in unnecessary interest. Always remember: in the world of personal finance, patience and arithmetic are your greatest allies.