In the high-stakes world of retirement planning, the traditional focus has long been on the "magic number"—the corpus required to sustain a lifestyle for three decades without a paycheck. However, a growing movement among financial planners and gerontology experts suggests that the industry has been solving only half of the equation. As life expectancy increases across the globe, a new and more daunting crisis is emerging: the "Physical Retirement."
While financial literacy has improved significantly, allowing many to reach their golden years with substantial wealth, a troubling trend has surfaced where individuals find themselves financially independent but physically or cognitively bankrupt. This phenomenon, often termed the "Longevity Paradox," posits that the very discipline required to build a massive retirement fund—long hours, high stress, and the postponement of self-care—often destroys the health necessary to enjoy it.
The Dual Retirement: A New Framework for the 21st Century
The concept of retirement is undergoing a fundamental shift. It is no longer a single event but a dual-track process consisting of a financial retirement and a physical retirement. The "quiet tragedy," as identified by financial experts, occurs when the physical retirement arrives years, or even decades, before the financial one.
Take the case of Ravi, a retired professional who spent forty years meticulously navigating market volatility and economic crises. He reached his financial goals with precision, yet he finds himself paralyzed by a fear that no spreadsheet can mitigate. His concern is not the depletion of his bank account, but the depletion of his vitality. "My biggest concern after my last paycheck was not at all about money," Ravi explains. "It was about whether we will both have the same energy and adventurous spirit we had in our thirties. To travel, to explore, to go on long drives."
Ravi’s situation highlights a critical blind spot in modern wealth management. He represents the "successful planner" who did everything right by the book, only to realize that the one asset he cannot rebuy—his physical health—is the one he neglected during his wealth-accumulation phase.
Chronology of a Shifting Landscape: From Survival to Quality of Life
Historically, retirement was a brief period. In the mid-20th century, life expectancy in many developing nations hovered around 60 to 65 years. Retirement was often a five-to-ten-year window of rest before the end of life.
However, the timeline has shifted dramatically:
- The 1980s–1990s: The rise of defined contribution plans shifted the burden of retirement saving from the employer to the individual. The focus was purely on "The Number."
- The 2000s: Advancements in medical science began extending life, but not necessarily "healthspan" (the period of life spent in good health). The industry saw an increase in retirees living into their 80s and 90s, but often with chronic conditions.
- The 2020s: A post-pandemic realization took hold. Wealthy retirees began to report that "Financial Independence" (FI) was hollow without "Physical Independence" (PI). The fear shifted from "running out of money" to "running out of self."
This chronological shift has brought stories like that of a retired professional woman who built a stellar career and a robust portfolio, only to spend her final six years bedridden. Her story serves as a cautionary tale: a full corpus is meaningless if the individual is unable to climb their own stairs, drive their own car, or live independently.
Supporting Data: The Hidden Costs of the "Health-Wealth Gap"
The data supporting the need for a holistic retirement approach is stark. According to various healthcare inflation indices, medical costs in many regions are rising at 12–15% annually—nearly double the rate of general inflation.
Furthermore, the "morbidity gap" is widening. While people are living longer, they are often living with chronic ailments for a larger percentage of their lives.
- Cognitive Decline: Research suggests that after the age of 65, the risk of developing some form of cognitive impairment increases significantly. This poses a massive financial risk, as impaired judgment can lead to catastrophic investment mistakes or susceptibility to financial fraud.
- The Cost of Dependence: Home healthcare and assisted living costs are not always fully covered by standard insurance, and they can erode even a substantial corpus within a few years.
- The "Purpose" Factor: Studies by the American Psychological Association and similar global bodies have shown that retirees who lose their sense of purpose experience a 20% higher risk of mortality and a faster decline in cognitive function.
These statistics suggest that health is not merely a lifestyle choice; it is a critical component of financial risk management.
Official Responses: The Evolution of Financial Planning
Leading financial advisors are now integrating "Health Capital" into their client reviews. The consensus among forward-thinking planners is that a plan that only grows money is incomplete.
"Money buys healthcare; it does not buy health," says Hemant Beniwal, a prominent financial planner. This distinction is becoming the cornerstone of modern advisory services. The industry is moving toward a "Life-First" planning model, where the client’s physical capabilities and personal goals dictate the investment strategy, rather than the other way around.
Experts emphasize three key pillars for a sustainable retirement:
- Asset Protection (Financial): Maintaining the corpus against inflation and market volatility.
- Maintenance of Independence (Physical): Investing in preventative health to avoid the high costs of long-term care and dependence.
- Social and Intellectual Continuity (Purpose): Ensuring the retiree remains engaged to prevent the "Sudden Retirement Syndrome" that can lead to rapid physical decline.
The Psychological Vacuum: When Purpose Retires
Perhaps the most poignant aspect of this crisis is the loss of purpose. The story of a successful trader who was pressured by his family to shut down his business and move to a big city illustrates this danger. On paper, the move was a financial and safety-oriented success. In reality, it was a death sentence.
By removing his routine, his social circle, and his sense of being "needed," his family inadvertently accelerated his physical decline. Within years, a man who was once sharp and active became bedridden and passed away. This highlights a critical implication: Retirement decisions must be made based on emotional and psychological dividends, not just financial efficiency.
Implications: Building a Resilient Retirement
The implications of this shift are profound for both individuals and the financial services industry. To avoid the tragedy of a "body retiring before the money," a new set of rules must be adopted:
1. Health as a Compounding Asset
Just as financial investments compound over time, so do health habits. Consistency in exercise, sleep, and nutrition in one’s 40s and 50s determines the "yield" of the retirement years. A retiree who enters their 60s with high mobility and cognitive clarity has a much "cheaper" and more fulfilling retirement than one who does not.
2. Planning for the "Surviving Spouse"
Financial plans must account for the high probability that one spouse will eventually navigate the journey alone. This involves not just leaving behind a bank account, but ensuring the spouse has a community, a simplified financial system they understand, and a support network. This is an act of "loving and practical" planning that transcends simple wealth management.
3. The Role of Community and Movement
Observation of active retirement communities reveals a common thread: those who thrive are those who maintain a "discipline of movement." Whether it is yoga, laughter clubs, or simple daily walks, these activities are not about aesthetics; they are investments in the ability to remain independent. In many successful aging communities, only a small fraction of residents (roughly 10%) actively engage in these "health deposits," suggesting a massive opportunity for public health and financial education.
4. Integrating Cognitive Risk into Portfolios
As individuals age, their ability to manage complex portfolios may diminish. A truly robust retirement plan includes "guardrails"—simplified structures, trusted advisors, or automated income streams—that protect the wealth even if the owner’s mental clarity begins to fade.
Conclusion: The Holistic Balance Sheet
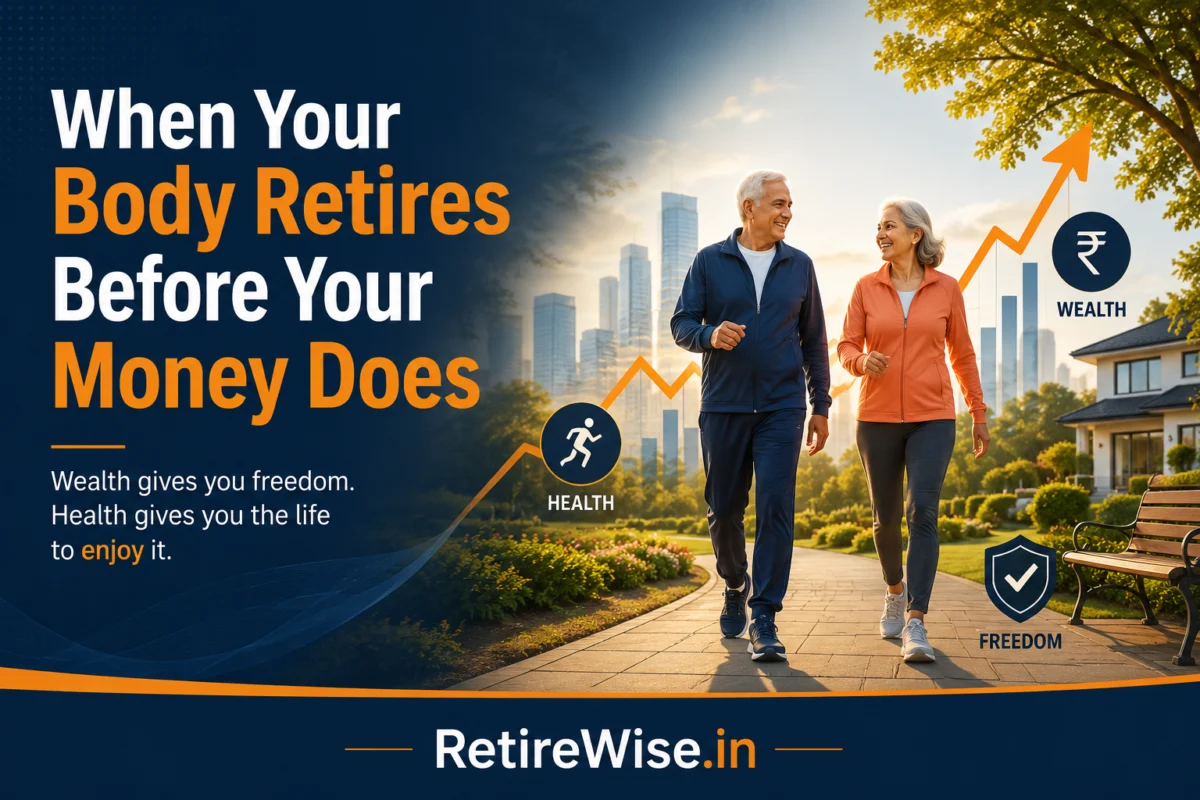
The ultimate goal of retirement is not to reach a specific number, but to fund a life worth living. The greatest risk facing modern retirees is not a market crash, but the realization of financial freedom at the exact moment they lose the physical or mental capacity to enjoy it.
A successful retirement plan must grow wealth, health, and purpose in tandem. As the financial world moves toward this more integrated approach, the message to the next generation of retirees is clear: Do not spend your health building your wealth, only to spend your wealth trying to buy back your health. The spreadsheet may show you are ready to retire, but your body and mind must be ready to live.