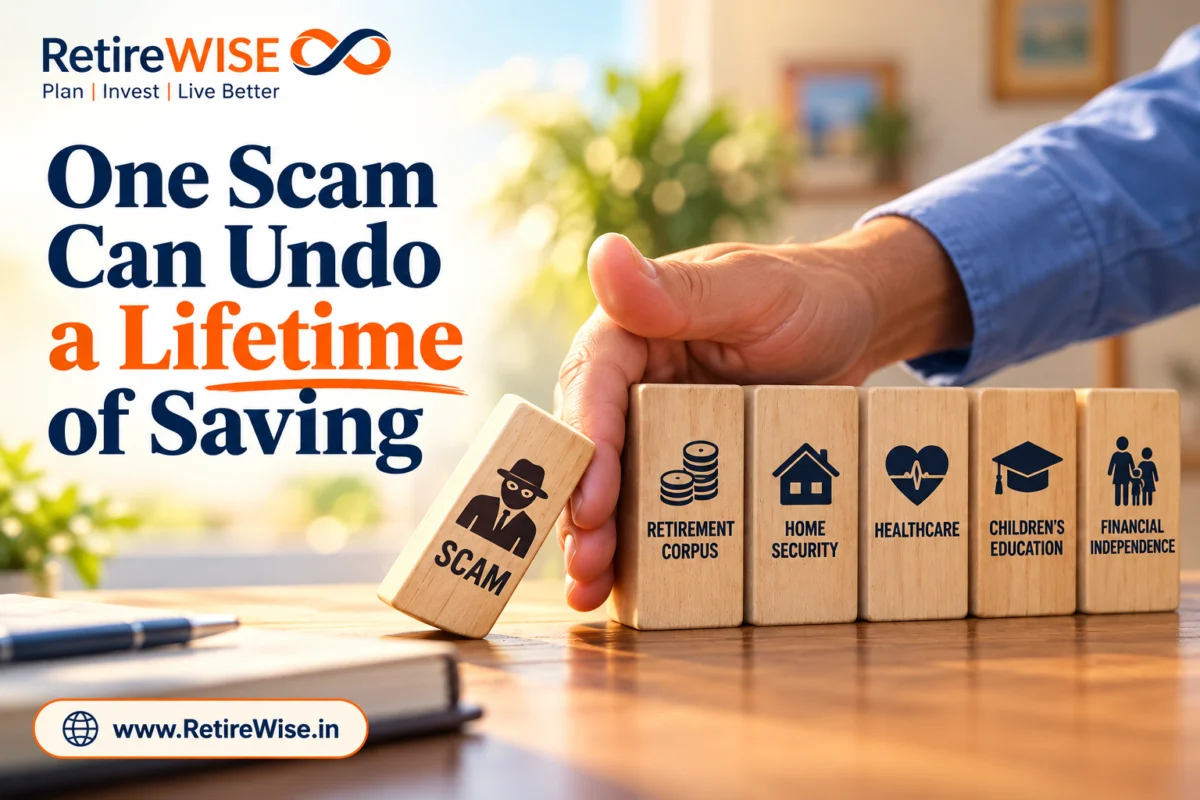
In the landscape of modern retirement planning, the traditional enemies have always been well-defined: market volatility, creeping inflation, and the "longevity risk" of outliving one’s savings. However, a new and far more predatory threat has emerged that threatens to undo decades of disciplined saving in a matter of hours. For the modern retiree, the greatest risk to their corpus is no longer a stock market crash, but the sophisticated, psychologically-driven financial scam.
As financial planners and wealth managers pivot their strategies to account for this rising tide of cyber-enabled fraud, the message is becoming clear: protecting a retirement nest egg is now just as critical—and perhaps more difficult—than growing it.
Main Facts: The "No Recovery" Reality of Retirement Scams
The fundamental difference between a financial loss during one’s working years and a loss during retirement is the ability to recover. For a professional in their 30s or 40s, a bad investment or a financial setback is a "time problem." With a monthly salary and decades of earning potential ahead, the loss can be amortized and eventually recouped.
For a retiree, however, the safety nets are gone. There is no next paycheck to replenish the coffers. The corpus sitting in bank accounts and mutual funds is a finite resource that must sustain them for the rest of their lives. When a fraudster siphons off ₹50 lakh or ₹1 crore, they aren’t just taking money; they are taking years of independence, dignity, and security.
Financial experts note that while market downturns are cyclical—often recovering within a few years—scam-related losses are permanent. The money vanishes into a labyrinth of mule accounts and cryptocurrency mixers, rarely to be seen again. This "permanent impairment of capital" at an advanced age represents the ultimate failure of a retirement plan.
Chronology: The Anatomy of a "Digital Arrest"
To understand the severity of the threat, one must examine the evolution of the tactics used. The era of the "Nigerian Prince" email has been replaced by "Digital Arrest" scams—a highly orchestrated form of psychological warfare.
Phase 1: The Initial Hook
The process typically begins with a phone call from an individual posing as an official from a courier company (like FedEx or DHL) or a law enforcement agency. The victim is told that a package in their name has been intercepted containing illegal items—narcotics, fake passports, or restricted documents.
Phase 2: Psychological Grooming
Once the victim is panicked, they are "transferred" to a fake police officer or a CBI official via a video call. The fraudsters often use sophisticated setups, including fake police station backdrops, authentic-looking uniforms, and forged legal documents. They use "doxxing" techniques, reciting the victim’s Aadhaar number, address, and family details to establish immediate, terrifying credibility.
Phase 3: The Isolation and Interrogation
The victim is told they are under "digital arrest" and must stay on the video call 24/7. They are forbidden from contacting family members or lawyers, under the guise of "national security" or "confidentiality." During this period, which can last for days, the scammers methodically inventory the victim’s assets—asking about fixed deposits, savings accounts, and jewelry.
Phase 4: The "Security Deposit"
The climax of the scam involves the "verification" of the victim’s funds. They are instructed to transfer their entire life savings into a "government-monitored" account for "investigation," with the false promise that the money will be returned once their name is cleared. Once the transfer is made, the scammers vanish.
Supporting Data: The Rising Scale of the Menace
The scale of this crisis is reflected in both individual tragedies and national statistics. Recently, an army veteran in India was defrauded of ₹1.28 crore in a digital-arrest scam. The callers were so methodical that they questioned him about his service record and pension details, using his sense of duty against him.
According to data from the Indian Cybercrime Coordination Centre (I4C), digital arrest scams and investment frauds have seen a meteoric rise. In the first four months of 2024 alone, Indians lost over ₹1,750 crore to cyber-frauds. Retirees and senior citizens are disproportionately targeted because they often have significant liquid assets and may be less familiar with the nuances of evolving digital technology.
Furthermore, the emergence of Artificial Intelligence (AI) has added a terrifying new dimension. AI voice cloning can now replicate a loved one’s voice with just a few seconds of audio from a social media clip. Fraudsters use this to stage "kidnapping" or "accident" calls, where a parent hears what sounds exactly like their child pleading for help, leading to impulsive, high-value transfers.
Official Responses and Regulatory Guardrails
In response to this epidemic, the Government of India and regulatory bodies like SEBI and the RBI have intensified their awareness campaigns. The Ministry of Home Affairs (MHA) has been proactive in promoting the National Cybercrime Helpline Number: 1930.
The "Golden Hour" Strategy
Law enforcement agencies emphasize the "Golden Hour"—the first 60 minutes after a fraudulent transaction occurs. If a victim reports the crime to 1930 or through the cybercrime.gov.in portal within this window, there is a significantly higher chance that the banks can "freeze" the funds before they are withdrawn or moved out of the banking system.
Regulatory Warnings
The Reserve Bank of India (RBI) has repeatedly clarified that no government agency or bank will ever ask for a PIN, OTP, or a transfer of funds over a phone call. Furthermore, "Digital Arrest" is not a legal concept in Indian law; police and judicial authorities do not conduct arrests or legal proceedings via WhatsApp or Skype video calls.
Implications: Building a "Human Firewall"
The implications of this trend suggest that financial planning must now include "defensive architecture." It is no longer enough to have a diversified portfolio; one must have a "friction-heavy" financial life.
1. The Power of Financial Friction
One of the best defenses for a retiree is to keep the majority of their wealth in "low-velocity" assets. While a savings account allows for instant transfers, money held in mutual funds or fixed deposits requires a multi-step process to liquidate and move to a third party. This delay provides a critical window for the "panic" to subside and for family members to intervene.
2. The Family Password
As AI makes visual and auditory evidence unreliable, experts are recommending a low-tech solution: the family password. Families are encouraged to agree on a secret word or phrase known only to them. If a family member calls in distress asking for money, the first step is to ask for the password. If the caller cannot provide it, the call is a confirmed fraud.
3. Combatting the "Shame Factor"
Perhaps the most significant implication is the psychological one. Scammers rely on the victim’s shame. Many retirees, once they realize they have been duped, stay silent to avoid being seen as "incompetent" by their adult children. This silence allows the scammers to continue their work. Creating an environment where seniors feel safe to report "mistakes" without judgment is a critical component of family financial security.
Conclusion: The New Pillar of Retirement Planning
As we move further into the digital age, the definition of a "successful retirement" is changing. It is no longer just about the person who accumulated the most wealth, but about the person who managed to keep it.
The advice for retirees today is clear: Verify before you trust. Never act under the pressure of urgency. Keep your financial details close, and your family communication closer. In the battle against fraudsters, your greatest assets are not just your passwords and encryption, but your skepticism and your willingness to hang up the phone.
Protecting your corpus is not a secondary task—it is the very foundation upon which a peaceful retirement is built. After twenty-five or thirty years of labor to build a legacy, it deserves more than a few minutes of misplaced trust to take it away.