Date: October 10, 2026
Industry Analysis: Commercial Real Estate
The Indian commercial office market has reached a fascinating crossroads. According to the latest data released by global real estate consultant Cushman & Wakefield, the sector is currently presenting a two-tiered narrative: while net absorption of office space has experienced a temporary recalibration, gross leasing activity has surged to unprecedented historical highs. This dichotomy reflects the structural resilience of the Indian office ecosystem, driven by the relentless expansion of Global Capability Centres (GCCs) and a strategic shift in corporate real estate planning.
Main Facts: The Divergence of Net and Gross Metrics
For the January-September 2026 period, the Indian office market reported a net absorption—defined as the net change in occupied space—of 36.7 million square feet (sq ft) across eight major cities. This represents a 20 per cent year-on-year decline compared to the 46 million sq ft recorded during the same period in 2025.
However, viewing this decline in isolation would be a misreading of market health. In stark contrast, gross leasing—which encompasses fresh absorption, open market renewals, and pre-leasing activity—scaled a record-breaking 64.6 million sq ft. This 1 per cent annual increase confirms that overall market activity remains vibrant. The discrepancy between these two figures is largely attributed to a high base effect from the previous year and a tactical tightening of "quality" supply in key micro-markets during the first half of 2026.
Chronology of Market Dynamics: A Year of Two Halves
The trajectory of the 2026 office market can be segmented into two distinct phases. During the first half of the year, the market faced significant supply-side headwinds. Developers, navigating a period of project completions and regulatory shifts, limited the introduction of fresh, high-grade office stock. This scarcity constrained occupier options, particularly for large-scale requirements in Tier-1 cities.
As the industry moved into the third quarter (July-September 2026), a significant uptick in building completions began to reshape the landscape. This surge in supply, while arriving later than anticipated, has provided the necessary "headroom" for the next phase of corporate expansion. The third quarter alone saw net absorption reach 14.1 million sq ft, signaling that the market is beginning to absorb the newly commissioned inventory as occupiers pivot from hesitant scouting to long-term commitments.
Supporting Data: Regional Performance and Divergence
The national average for net leasing hides a deeply nuanced regional performance. Cushman & Wakefield’s data highlights a clear split between markets that faced supply constraints and those that experienced aggressive expansion.
Markets Facing Contraction in Net Leasing:
- Delhi-NCR: Recorded a 48 per cent decline, falling to 5 million sq ft from 9.6 million sq ft.
- Chennai: Also saw a 48 per cent dip, dropping to 2.8 million sq ft from 5.4 million sq ft.
- Mumbai: Experienced a 46 per cent decrease, moving from 7.6 million sq ft to 4.1 million sq ft.
- Pune: Reported a 39 per cent decline, totaling 4.2 million sq ft against 6.9 million sq ft in the previous year.
- Kolkata: Observed a moderate 12 per cent decline to 1.1 million sq ft.
Markets Showing Robust Growth:
- Ahmedabad: Emerged as a standout performer, with net leasing surging 81 per cent to 1.2 million sq ft.
- Hyderabad: Posted a strong 41 per cent increase, reaching 7.3 million sq ft.
- Bengaluru: Retaining its status as India’s largest office market, Bengaluru recorded a 16 per cent rise in net leasing, climbing to 11 million sq ft.
The performance of Bengaluru, Hyderabad, and Ahmedabad suggests that these cities have successfully managed to align their new project pipelines with the specific space requirements of modern occupiers, particularly those in the technology and GCC sectors.
Official Responses and Strategic Outlook
Anshul Jain, Chief Executive, India, SEA, MEA & APAC Office and Retail at Cushman & Wakefield, emphasized that the underlying fundamentals of the Indian office market remain "structurally strong."
"With 64.6 million sq ft of gross leasing in the first nine months of 2026, the highest ever for this period, the market continues to demonstrate remarkable depth and resilience, despite persistent macroeconomic and geopolitical uncertainty," Jain stated. He further noted that the sustained momentum is heavily underpinned by the continuous influx of Global Capability Centres. India’s massive talent pool, combined with the country’s unparalleled cost competitiveness, remains a primary driver for multinational corporations looking to centralize their global operations within Indian borders.
Veera Babu, Executive Managing Director of Tenant Representation-India, echoed these sentiments, providing a technical perspective on the moderation of net absorption. "While year-to-date net absorption moderated compared to last year, this was against a strong 2025 base and was also influenced by limited supply additions during the first half of the year," Babu explained.
Looking ahead, Babu remains optimistic, citing a shift in occupier behavior. "We are seeing occupiers plan further ahead. Pre-commitments are gaining traction, and businesses are considering a broader set of locations, including those beyond established office hubs, as part of their long-term growth plans."
Implications: The Future of Corporate Workspace
The data for 2026 points to several critical implications for developers, investors, and corporate occupiers:
1. The "Quality" Premium
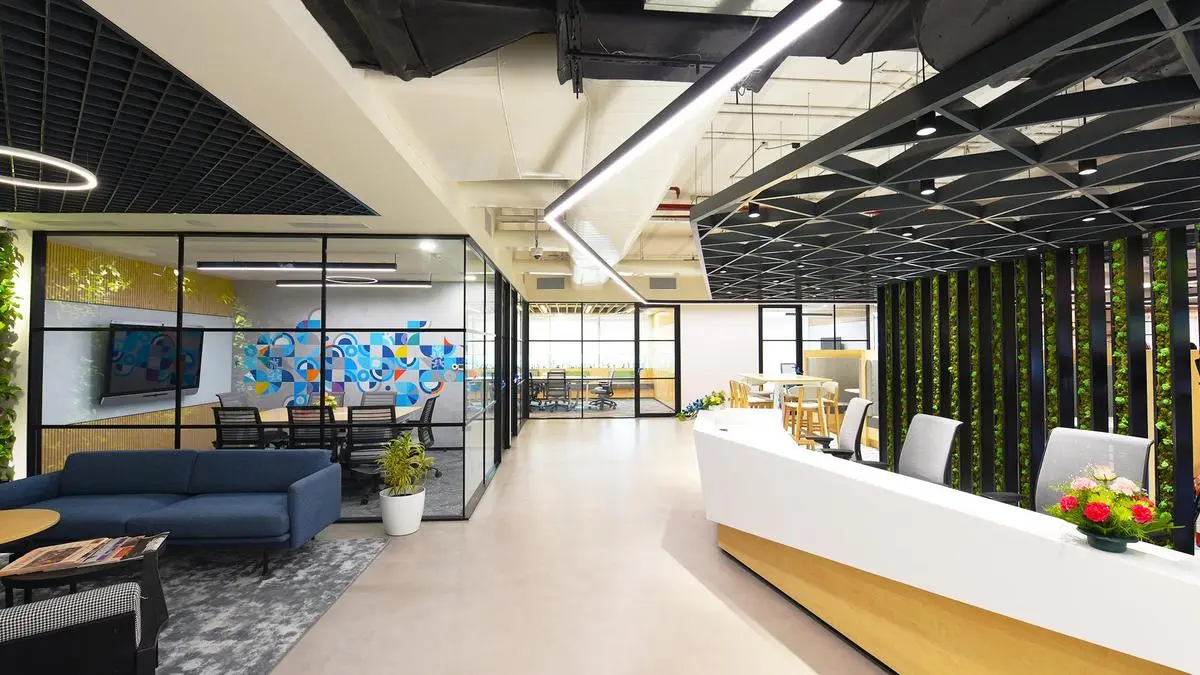
The market is increasingly prioritizing high-specification, Grade-A workspaces that adhere to global ESG (Environmental, Social, and Governance) standards. Buildings that fail to meet these evolving sustainability and wellness benchmarks are seeing slower absorption rates, regardless of their location.
2. The Rise of Decentralization
The surge in markets like Ahmedabad and the resilience of Hyderabad indicate that the "hub-and-spoke" model is maturing. Occupiers are no longer tethered solely to the traditional Central Business Districts (CBDs) of Mumbai or Delhi-NCR. As infrastructure improves, secondary hubs and peripheral business districts are becoming increasingly attractive for large-scale corporate consolidation.
3. The GCC Dominance
Global Capability Centres have moved beyond being mere cost-arbitrage vehicles. They are now innovation centers. As these entities expand, they require not just space, but specialized environments that foster collaboration and high-end R&D. This evolution is the primary engine fueling the record-breaking gross leasing figures observed this year.
4. A Shift in Leasing Strategy
The increase in pre-commitments signifies a move toward risk mitigation. Occupiers are looking to lock in future space before construction completes, ensuring they are not left without high-quality options as the market tightens. This trend is likely to sustain the momentum of gross leasing even if global economic volatility continues.
Conclusion
The first nine months of 2026 have presented a market that is far more sophisticated than simple absorption numbers might suggest. While the 20 per cent annual decline in net leasing highlights the impact of supply constraints and a high 2025 base, the record 64.6 million sq ft of gross leasing is the truer barometer of India’s commercial real estate vitality.
As developers accelerate project completions and occupiers adopt longer-term, strategic real estate horizons, the Indian office market is poised to maintain its trajectory. The challenges of the first half of the year appear to be behind us, replaced by a second half defined by expansion, diversification, and the continued dominance of India as a global corporate hub. For stakeholders, the message is clear: despite temporary fluctuations in net absorption, the demand for high-quality, strategically located workspace remains firmly on an upward path.