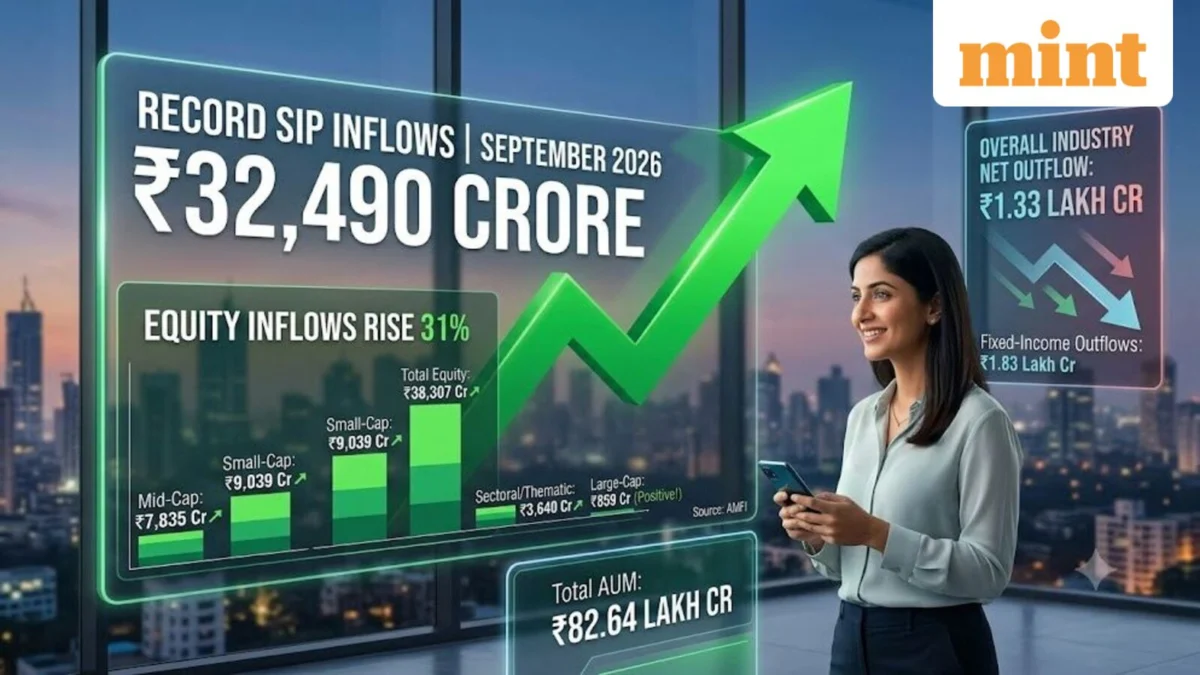
Mumbai, October 12, 2026 – India’s mutual fund industry presented a fascinating dichotomy in September 2026, showcasing both robust retail investor confidence and significant institutional churn. Monthly investments through Systematic Investment Plans (SIPs) soared to an unprecedented ₹32,490 crore, marking yet another milestone in the retail investment landscape. This surge was complemented by a substantial 30.6% month-on-month increase in equity mutual fund inflows, reaching ₹38,307 crore, indicating a strong appetite for risk assets among investors.
However, these impressive figures were overshadowed by a staggering ₹1.33 lakh crore in net outflows across the entire mutual fund industry during the month. The primary catalyst for this considerable withdrawal was the fixed-income segment, which alone witnessed net outflows of an alarming ₹1.83 lakh crore. This sharp contrast paints a picture of a dynamic market where retail investors continue to embrace disciplined, long-term equity exposure, even as institutional and corporate players adjust their debt portfolios in response to prevailing economic and interest rate environments. The industry’s overall Assets Under Management (AUM) consequently declined to ₹82.64 lakh crore in September from ₹87.08 lakh crore in August, reflecting the sheer scale of the debt withdrawals.
A Chronicle of Steadfast Growth and Sudden Shifts
The journey of India’s mutual fund industry, particularly its retail participation through SIPs, has been one of consistent upward momentum over the past decade. SIPs, designed to encourage disciplined investing by allowing individuals to invest a fixed amount regularly, have evolved from a niche investment strategy to a cornerstone of financial planning for millions of Indians.
The Unstoppable Ascent of SIPs
The September 2026 record of ₹32,490 crore in SIP inflows is not an isolated event but rather the continuation of a powerful trend. For several years, SIP contributions have consistently broken previous records, reflecting increasing financial literacy, easier access to investment platforms, and a growing understanding of rupee cost averaging benefits. Just a few years prior, monthly SIP inflows were hovering around the ₹10,000-15,000 crore mark. By late 2024, they had comfortably crossed ₹20,000 crore, and by mid-2025, they were approaching ₹25,000 crore. The jump from ₹32,297 crore in August to ₹32,490 crore in September, while numerically modest, signifies an underlying resilience and expansion of the retail investor base. This steady accretion of capital through SIPs has provided a crucial domestic counter-balance to potential volatility induced by foreign institutional investor movements, lending stability to the Indian equity markets.
Equity’s Enduring Appeal
Alongside the SIP surge, equity mutual funds have been a consistent beneficiary of investor confidence. The 30.6% month-on-month rise in net equity inflows to ₹38,307 crore in September is a testament to the bullish sentiment surrounding India’s economic growth prospects and corporate earnings potential. This trend has been particularly pronounced in the post-pandemic recovery period, where Indian equities have demonstrated remarkable resilience and growth, attracting both new and seasoned investors. The narrative of India as a rapidly growing economy with a young demographic and robust consumption story has resonated deeply, encouraging investors to allocate a larger portion of their savings to equity-oriented schemes for long-term wealth creation.
The Abrupt Reversal in Debt Funds
In stark contrast to the equity story, the debt mutual fund segment experienced a dramatic reversal. While debt funds often see periodic fluctuations due to corporate treasury movements or quarterly advance tax payments, the scale of the ₹1.83 lakh crore outflow in September was exceptional. In August, debt funds had seen a relatively minor outflow of ₹8,127 crore, making the September figures a significant anomaly. This sudden and massive exodus typically points to larger systemic factors at play, such as shifts in interest rate expectations, changes in monetary policy, or large-scale rebalancing by institutional investors seeking higher yields elsewhere or managing liquidity. Such sharp movements highlight the sensitivity of the debt market to macroeconomic indicators and the often-short-term horizon of institutional investments in certain debt categories.
Granular Insights: Unpacking the September Data
The data released by the Association of Mutual Funds in India (AMFI) provides a detailed breakdown of these trends, offering crucial insights into investor behavior and market dynamics.
SIPs: The Bedrock of Retail Participation
The record SIP inflow of ₹32,490 crore in September 2026 solidifies its position as the preferred mode of investment for a vast majority of retail investors. This consistent growth indicates that more individuals are adopting a disciplined approach to investing, leveraging the power of compounding and rupee cost averaging. The total number of SIP accounts also continued its upward trajectory, likely crossing the 11-crore mark, while the SIP AUM is estimated to have neared ₹15 lakh crore, reflecting the cumulative impact of these regular investments. This segment underscores a structural shift in how Indian households approach savings and investments, moving away from traditional avenues towards market-linked products.
Equity Funds: A Deep Dive into Preferences
The net inflows into equity mutual funds, totaling ₹38,307 crore, reveal a nuanced preference among investors:
- Small-cap Mutual Funds: These funds continued to attract significant capital, with inflows of ₹9,039 crore, up from ₹7,973 crore in August. This consistent interest in small-cap stocks suggests that investors are willing to take on higher risk in pursuit of potentially higher returns, betting on the growth potential of emerging companies within the broader Indian economy.
- Mid-cap Fund Inflows: Mirroring the small-cap trend, mid-cap funds saw inflows rise to ₹7,835 crore from ₹6,989 crore. Mid-caps are often seen as a sweet spot, offering a balance between the growth potential of small-caps and the relative stability of large-caps.
- Flexi-cap Schemes: These funds, which allow fund managers the flexibility to invest across market capitalizations without strict constraints, saw inflows increase to ₹6,702 crore from ₹5,059 crore. This preference highlights investor trust in fund managers’ ability to navigate dynamic market conditions and allocate capital optimally.
- Sectoral Thematic Funds: Inflows into these specialized funds surged to ₹3,640 crore from ₹1,713 crore. This significant jump indicates growing conviction among investors about specific sectors poised for growth. For instance, themes around infrastructure development, manufacturing prowess (aligned with ‘Make in India’ initiatives), digital transformation, or consumption stories could be driving this interest.
- Large-cap Mutual Funds: After experiencing net outflows of ₹1,147 crore in August, large-cap funds returned to positive territory, attracting ₹859 crore. This shift could signify a rotation towards established, blue-chip companies, possibly driven by institutional investors seeking stability, or retail investors looking for relatively safer bets within the equity space after a period of high growth in mid and small caps.
These detailed figures underscore a broad-based confidence in Indian equities, with investors diversifying their exposure across the market capitalization spectrum and thematic opportunities.
Debt Funds: The Epicenter of Outflows
The colossal net outflow of ₹1.83 lakh crore from fixed-income mutual funds in September, a dramatic increase from ₹8,127 crore in August, requires careful examination. This exodus was likely concentrated in categories such as:

- Liquid Funds and Ultra Short Duration Funds: These funds are often used by corporations for parking short-term cash and managing treasury operations. A significant portion of the outflows could be attributed to corporations withdrawing funds for advance tax payments, quarterly rebalancing, or shifting to higher-yielding direct investment options like Commercial Papers (CPs) or Certificates of Deposit (CDs) if short-term interest rates in the money market became more attractive.
- Corporate Bond Funds and Gilt Funds: While less susceptible to short-term corporate liquidity needs, these funds could also see withdrawals if investors anticipate a continued rise in interest rates. Rising interest rates generally lead to a decline in the net asset value (NAV) of existing debt funds, prompting some investors to book losses or shift to instruments that offer better yields for new investments.
- Credit Risk Funds: If there are concerns about credit quality in the broader economy, investors might pull money from funds exposed to lower-rated corporate bonds.
The sheer magnitude of these outflows dominated the otherwise positive trends, leading to an overall net outflow for the industry and a significant contraction in the total AUM from ₹87.08 lakh crore to ₹82.64 lakh crore. This illustrates the powerful impact that large institutional movements can have on the overall industry statistics, often masking robust underlying retail participation.
Official Responses and Expert Commentary
Industry leaders and financial experts have offered their perspectives on these contrasting trends, emphasizing the long-term potential while acknowledging short-term market dynamics.
Mr. Venkat Nageshwar, CEO of AMFI, commented on the latest figures: "The consistent record-breaking SIP inflows are a clear indicator of the deepening financialization of savings in India and the unwavering trust retail investors place in the mutual fund ecosystem. This disciplined approach to investing through SIPs is not just about wealth creation for individuals, but also about providing a stable, domestic capital flow that strengthens our equity markets. While we acknowledge the significant outflows from debt funds this month, these movements are often cyclical and reflective of corporate treasury management or adjustments to interest rate expectations. The long-term growth story for the Indian mutual fund industry remains robust, driven by retail participation."
Ms. Anjali Sharma, Chief Investment Officer at Zenith Asset Management, offered her insights into the equity market’s appeal: "The robust inflows into equity funds, particularly across small, mid, and flexi-cap categories, underscore investor confidence in India’s sustained economic growth trajectory. Earnings visibility, coupled with the government’s pro-growth policies, makes a compelling case for equity investments. The return of large-cap funds to positive inflows also suggests a broader market participation and potentially a flight to quality as some investors rebalance their portfolios. For debt, the outflows are largely a function of the current interest rate environment and corporate liquidity needs. As yields adjust, we anticipate a stabilization in debt fund flows."
Mr. Rajeev Kapoor, a seasoned financial planner and founder of WealthPath Advisors, advised caution and emphasized the importance of individual financial goals: "While the record SIP numbers are certainly encouraging and reflect a growing financial maturity among retail investors, it’s crucial for individuals not to get swayed solely by monthly inflow trends. The massive debt fund outflows, for instance, highlight that institutional behavior can be very different from retail. Investors must ensure their mutual fund schemes are perfectly aligned with their long-term economic objectives, investment horizon, and personal risk tolerance. Chasing hot sectors or reacting impulsively to market movements, whether inflows or outflows, can be detrimental to wealth creation. SIPs are powerful tools for discipline, but they do not assure or guarantee returns, nor do they protect against market-driven losses."
Implications for Investors, Industry, and Economy
The September 2026 data carries several significant implications for various stakeholders within India’s financial ecosystem.
For Retail Investors: A Call for Prudence and Patience
The continued strength of SIPs signifies that retail investors are increasingly committed to long-term wealth creation through equities. This is a positive development, fostering financial discipline and harnessing the power of compounding. However, the data also serves as a reminder that the overall industry figures can be heavily influenced by institutional movements, particularly in the debt segment. Retail investors should:
- Focus on Personal Financial Goals: Do not be swayed by short-term market trends or headlines. Your investment decisions should always be aligned with your personal financial objectives, risk profile, and investment horizon.
- Understand Diversification: While equity offers growth potential, a balanced portfolio that includes debt, gold, and other asset classes can help mitigate risk and provide stability.
- Consult a Financial Advisor: Professional guidance can help tailor an investment strategy that suits individual needs, ensuring that choices are informed and not reactive.
- Long-Term Perspective: SIPs are designed for the long haul. Market fluctuations, including debt fund outflows, are part of the investment landscape. Staying invested through cycles is key to realizing long-term benefits.
For the Mutual Fund Industry: Adapting to Evolving Dynamics
The industry faces both opportunities and challenges. The sustained growth in SIPs presents an immense opportunity for deeper market penetration, especially in semi-urban and rural areas. Fund houses will need to continue innovating in product design, distribution, and investor education to capitalize on this growing retail base.
On the challenge front, managing large-scale debt fund outflows requires careful liquidity management and strategic product offerings that can adapt to changing interest rate environments. Fund managers will need to be agile in positioning their debt portfolios to attract and retain institutional capital while catering to the evolving needs of retail debt investors. Furthermore, the industry may face increased scrutiny from regulators regarding the transparency and risk management of debt funds, especially in times of significant volatility.
For the Indian Economy and Capital Markets: A Pillar of Stability
The consistent flow of domestic capital through SIPs into equities is a crucial stabilizing factor for the Indian capital markets. It reduces the market’s dependence on fickle foreign institutional investments, providing a robust demand base for Indian companies. This domestic flow reflects growing confidence in India’s economic narrative and its potential for sustained growth. The shift towards financial assets from traditional physical assets (like gold or real estate) is a healthy sign for the economy, channeling savings into productive investments that fuel corporate expansion and job creation. While the debt market movements indicate short-term adjustments, the underlying retail equity participation signals a structural strengthening of India’s investment landscape.
In conclusion, September 2026 served as a powerful illustration of the multi-faceted nature of India’s mutual fund industry. The unprecedented SIP inflows and strong equity participation underscore the rising financial awareness and long-term vision of retail investors. Simultaneously, the significant debt fund withdrawals highlight the intricate dance of institutional capital, responding dynamically to macroeconomic shifts. Navigating these contrasting currents effectively will be key for investors and the industry alike, as India continues its journey towards becoming a financial powerhouse.