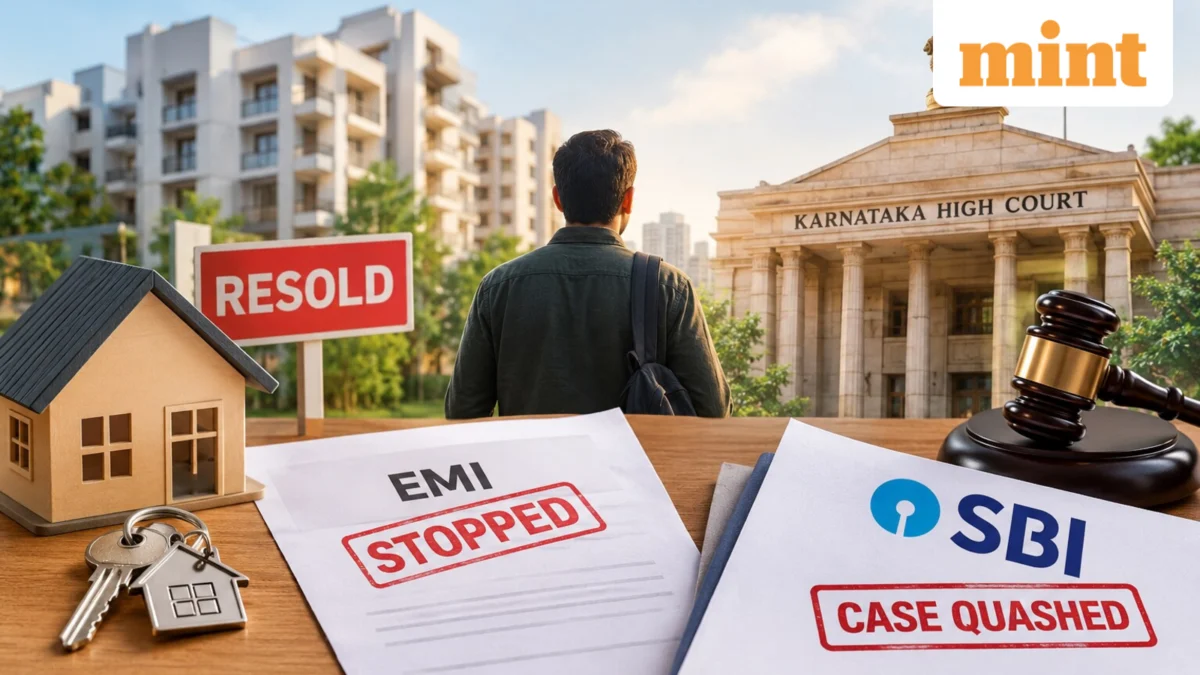
In a landmark judicial intervention that offers significant relief to property buyers across India, the Karnataka High Court has quashed criminal proceedings initiated by the State Bank of India (SBI) against a homebuyer who stopped his Equated Monthly Instalments (EMIs) after discovering his builder had illegally resold his apartment.
The ruling serves as a powerful rebuke against the weaponization of criminal law in civil financial disputes. By explicitly stating that an outstanding financial liability—even one resulting from a defaulted loan—does not automatically constitute a criminal offence, the court has drawn a sharp line in the sand between contractual obligations and malicious intent.
The Anatomy of the Dispute: A Breach of Trust
The case centers on Mr. Bari, a Mumbai-based professional, who in the financial year 2019-20 sought to invest in the Bengaluru real estate market. He secured a home loan of ₹39.92 lakh from the State Bank of India to purchase flat B-306 in the ‘Grandeur Park’ project.
Like millions of other homebuyers, Bari entered into a standard tripartite agreement—a three-way contract involving the buyer, the lender, and the developer—on February 8, 2020. For years, Bari acted in good faith, diligently servicing his EMIs from his home in Mumbai, trusting the builder to complete the project as promised.
The situation spiraled in March 2023 when Bari discovered, to his shock, that the developer had sold his allotted unit to a third party without his knowledge or consent, and without informing the lender. Upon learning that his asset had been effectively stripped from him, Bari ceased all EMI payments.
Instead of navigating the civil dispute with the builder, SBI initiated criminal proceedings in September 2024. The bank filed an FIR against Bari, leveling charges of cheating, criminal breach of trust, and misappropriation of funds. The bank’s legal counsel relied on specific clauses of the tripartite agreement to argue that the buyer remained liable for the debt regardless of the developer’s actions, effectively treating the cessation of payments as a criminal act of delinquency.
Chronology of the Legal Battle
- February 2020: Mr. Bari signs a tripartite agreement with SBI and the builder for a flat in the Grandeur Park project, Bengaluru.
- 2020–2023: Bari maintains a clean repayment record, fulfilling his financial obligations to the bank despite residing in a different city.
- March 2023: Bari discovers that the developer has illegally resold his flat to a third party. He immediately stops EMI payments as the underlying asset is no longer his.
- September 2024: SBI files an FIR against Bari, alleging criminal intent, cheating, and breach of trust.
- October 2026: The Karnataka High Court quashes the criminal FIR, ruling that the dispute is purely civil in nature and that the buyer lacked criminal intent.
The Tripartite Agreement: Why the Builder Bore Responsibility
Central to the court’s decision was the interpretation of the tripartite agreement. Under Clauses 2, 4, 5, and 6 of the document, the responsibility for financial settlement in the event of project failure or cancellation is clearly defined.
Crucially, Clause 5 of the agreement mandates that if the project fails to materialize or if the builder cancels the booking for any reason, the developer is legally obligated to refund the entire amount collected from the homebuyer directly to the bank.
Legal experts argue that this clause is designed to protect the lender’s interest by ensuring that if the asset is compromised, the primary debtor—the developer—must settle the dues. The court observed that Bari had neither received the title of the property nor participated in the illicit resale, nor had he gained any financial benefit from the developer’s fraud. Consequently, the attempt to label his payment stoppage as "cheating" was found to be legally untenable.
Judicial Rationale: Criminal Law as a Last Resort
In its scathing critique of the bank’s actions, the Karnataka High Court emphasized that public-sector institutions are held to a higher standard of due diligence. The court noted that the bank had bypassed the appropriate civil remedies to pursue an individual whose primary "offense" was reacting to a fraudulent act committed by a third party.

"The existence of an outstanding loan or the failure of the underlying transaction, by itself, cannot be treated as constituting a criminal offence," the court stated. The judiciary underscored that criminal prosecution is not a shortcut for debt recovery. For a criminal charge like "cheating" to stick, there must be evidence of mens rea—a guilty mind or malicious intent from the inception of the contract. In this instance, Bari had proven his commitment to the contract for years; his decision to stop payments was a logical reaction to the total collapse of the developer’s obligations.
Implications for the Indian Banking Sector
This ruling carries profound implications for the Indian real estate and banking landscape. For years, banks have often used the threat of criminal FIRs to pressure homebuyers into continuing payments even when projects are stalled or fraudulent. This judgment effectively clips the wings of lenders who might be tempted to use the police as a collection agency.
1. Shift in Risk Assessment
Banks will now be required to conduct more rigorous due diligence on developers. If a project is compromised, the lender must look to the developer for recovery as stipulated in the tripartite agreement, rather than shifting the entire burden of risk onto the buyer.
2. Empowerment of the Homebuyer
Homebuyers often feel powerless against large institutional lenders. This ruling reinforces the idea that the homebuyer is also a victim of builder fraud. By protecting the buyer from criminal prosecution, the court has provided a layer of security that encourages buyers to demand accountability from developers without the looming threat of being jailed for "defaulting" on a loan for a non-existent house.
3. Civil vs. Criminal Clarity
The ruling serves as a definitive guide for lower courts and police stations. It mandates that any dispute stemming from a loan agreement where the underlying property transaction is contested must be treated as a civil dispute, governed by the Transfer of Property Act or the RERA (Real Estate Regulatory Authority) guidelines, rather than the Indian Penal Code.
Expert Perspectives: A Lesson in Due Diligence
Kalpit Khandelwal, Partner at Aekom Legal, highlights the necessity for buyers to be hyper-vigilant during the signing of tripartite agreements. "The agreement is the primary document that dictates the allocation of risk," Khandelwal explains. "In this case, the court correctly identified that the contract explicitly shifted the burden of refund to the builder. Buyers must scrutinize these clauses—specifically regarding ‘default’ and ‘cancellation’—before signing, as they are the first line of defense if a developer defaults."
Experts suggest that buyers should:
- Demand transparency: Ensure all project approvals are updated in real-time.
- Monitor RERA portals: Check for project delays or legal issues associated with the developer.
- Consult legal counsel: Before stopping payments, buyers should send formal notices to the bank and the builder, documenting the reason for the cessation of EMIs to avoid being labeled as a willful defaulter.
Conclusion: The Road Ahead
While the Karnataka High Court’s ruling is a massive victory for Mr. Bari, it also highlights the systemic gaps that persist in the Indian housing market. While the criminal case is quashed, the civil battle regarding the recovery of the money already paid remains.
The ruling does not automatically wipe away the debt; it simply ensures that the borrower is treated with the due process of civil law rather than the blunt instrument of criminal litigation. For the banking sector, it is a reminder that while the recovery of funds is a legitimate objective, it must be pursued within the bounds of contractual justice. For the homebuyer, it is a reassurance that the law will not allow them to be doubly victimized—first by a fraudulent builder and then by an overzealous lender.
As the real estate sector continues to evolve, this case will likely serve as a foundational reference point for future litigation, ensuring that the sanctity of the homebuyer-lender relationship remains rooted in fairness and mutual accountability.