New Delhi, India – For many young professionals, a significant salary hike is a tangible marker of career progression and a promise of enhanced financial security. The immediate gratification often translates into a feeling of greater purchasing power and a perceived ability to enjoy a more comfortable lifestyle. However, a closer examination of financial trends reveals a peculiar paradox: higher earnings do not automatically translate into higher savings or accelerated wealth creation. Instead, for a significant segment of the millennial and Gen Z workforce, the additional income is frequently absorbed by a confluence of rising rent, burgeoning lifestyle expenses, and increased discretionary spending, leaving little surplus to build a robust financial cushion.
This phenomenon, often termed "lifestyle creep," is a silent saboteur of wealth accumulation. It underscores a critical distinction: the problem isn’t necessarily how much a person earns, but rather the efficacy with which they manage the money that flows into their accounts each month. As Uttam Agarwal, Chief Business Officer at BajajCapital – La Premièr, aptly observes, "Lifestyle expenses often rise alongside income as young professionals spend more on better housing, convenience, travel, and new experiences." The inherent challenge arises when this increase in spending occurs without a corresponding, proportional rise in savings and investments, effectively neutralizing the financial benefits of a fatter paycheck.
Recent economic shifts, including fluctuating inflation rates and the escalating cost of living in major metropolitan hubs, further compound this issue. While a 10-15% annual increment might seem substantial on paper, its real purchasing power can quickly diminish when faced with a 7-10% increase in rent, higher fuel prices, and the pervasive allure of consumerism. This article delves into five common money habits that frequently prevent young professionals from building substantial wealth, even as their salaries steadily grow, offering insights into how to navigate this intricate financial landscape.
The Salary Hike Paradox: When More Income Doesn’t Mean More Savings
The contemporary economic environment presents a unique set of challenges for young professionals. The competitive job market often pushes them towards high-cost urban centers, where the cost of living, particularly rent, can consume a significant portion of their income. A 2023 survey by a prominent real estate consultancy indicated that rent in major Indian metros increased by an average of 15-20% year-on-year, far outpacing typical salary increments for many. This baseline expenditure already eats into potential savings, making disciplined financial management even more crucial.
Beyond necessities, the digital age has ushered in an era of unprecedented convenience and aspirational living. From food delivery apps and ride-sharing services to a plethora of streaming subscriptions and the latest tech gadgets, the temptation to spend is constant and easily accessible. Social media platforms often amplify this pressure, creating an unspoken expectation to keep pace with peers’ perceived lifestyles, leading to what financial psychologists term "social contagion spending." The psychological gratification derived from these immediate purchases often overshadows the long-term benefits of deferred gratification through savings and investments.
The paradox thus lies in the human tendency to adapt spending patterns to new income levels. What was once considered a luxury quickly becomes a necessity. This shift in financial perception, if left unchecked, can lead to a perpetual cycle where financial security remains an elusive goal, regardless of how high the salary climbs. Financial literacy and conscious decision-making, therefore, become paramount in transforming a salary hike from a fleeting pleasure into a foundational step towards enduring wealth.
Five Money Habits Hindering Wealth Creation for Young Professionals
The journey to financial independence is paved not just with high earnings, but with astute financial discipline. Here are five prevalent habits that, according to financial experts, can derail wealth-building efforts even for those with robust incomes:
1. The Peril of Lifestyle Creep: Allowing Expenses to Rise with Every Salary Hike
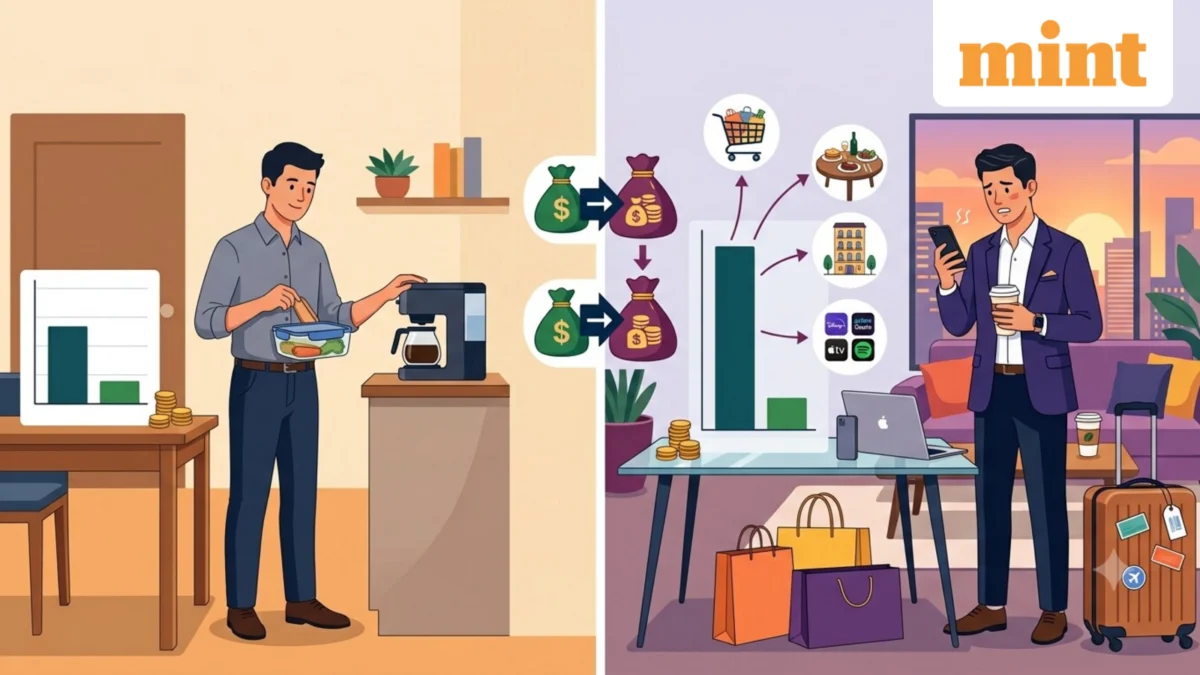
One of the most insidious threats to wealth accumulation is lifestyle creep, the gradual increase in spending as discretionary income rises. A higher income often creates a sense of entitlement to "upgrade" various aspects of one’s life. This could manifest as moving into a more expensive apartment, dining out at upscale restaurants more frequently, booking international holidays, purchasing designer clothes, or subscribing to premium services. Individually, these expenses might seem justifiable, but collectively, they can swiftly consume a substantial share of any salary increase.
For instance, a young professional earning ₹1 lakh per month might secure a ₹20,000 raise, bringing their income to ₹1.2 lakh. Instead of directing a significant portion of this increment towards savings, they might decide to move from a shared accommodation to a private apartment, increasing their rent by ₹10,000. They might also subscribe to a new fitness app (₹500), upgrade their phone plan (₹200), and increase their weekly food delivery budget by ₹2,000. While each decision seems minor, the cumulative effect means that ₹12,700 of the ₹20,000 raise is already committed to new expenses, leaving only ₹7,300, or just over a third, available for actual savings.
"The problem is not necessarily spending more as income grows, but allowing expenses to rise so much that the amount saved remains unchanged," states Agarwal. He emphasizes that the key is to ensure that spending does not increase without a corresponding and proportional increase in savings. Young professionals can certainly allow themselves some lifestyle upgrades – a reward for their hard work – but a significant portion of every salary hike, ideally 50% or more of the increment, should be consciously directed towards financial goals. This strategy ensures that while one enjoys an improved quality of life, their financial cushion grows even faster. According to a recent survey on consumer spending habits, over 60% of young professionals admitted that their discretionary spending increased by more than 30% after a salary hike, often without a commensurate rise in their savings rate. This highlights the widespread nature of lifestyle creep and its profound impact.
2. The Flaw of Passive Saving: Only Saving What Is Left at the End of the Month
A common, yet fundamentally flawed, approach to saving is to spend first and then attempt to save whatever remains at the end of the month. This method makes savings entirely dependent on the fluctuating leftovers after all monthly expenses, which can vary wildly. Some months might see a small surplus, while others, particularly those with unexpected costs or increased social engagements, might leave nothing at all. This "passive saving" strategy inherently prioritizes immediate consumption over long-term financial security.
A more consistent and effective approach, widely advocated by financial planners, is to "pay yourself first." This involves setting aside a predetermined amount for savings and investments at the very beginning of the month, ideally immediately after the salary is credited. The remaining income is then used for planned spending. This proactive approach ensures that saving is a non-negotiable financial commitment rather than an afterthought.
Agarwal recommends that working professionals aim to save and invest around 20-30% of their monthly take-home pay, depending on their financial obligations and lifestyle. For someone earning ₹1 lakh a month, this translates to targeting savings and investments of ₹20,000 to ₹30,000. Those who find this target initially challenging can begin with a smaller, more achievable amount, say 10-15%, and gradually increase it as their earnings grow. The objective is to embed saving as a regular, automatic part of monthly financial decisions, ensuring consistency and leveraging the power of compound interest over time. "The greatest regret many older professionals have is not starting to save and invest consistently earlier in their careers," says Ms. Anjali Singh, a wealth management advisor. "The magic of compounding works best with time and consistency."
3. The Stealthy Drain: Underestimating the Impact of Recurring Expenses
While lifestyle creep focuses on new expenses, underestimating recurring expenses deals with the cumulative impact of ongoing, often seemingly small, payments. Rent, loan EMIs, food deliveries, subscriptions (streaming, gym memberships, software), daily coffees, and credit card expenses can gradually, and often imperceptibly, reduce the amount available for savings. Because many of these payments are spread across the month or are automatically debited, it can be difficult to perceive their collective magnitude.
A higher salary can foster a false sense of security, creating the impression that there is ample room to spend, even when fixed commitments have already consumed a significant share of income. For example, a young professional might have EMIs for an education loan, a car loan, and perhaps a gadget loan. Add to this the monthly rent, internet, mobile bills, and several streaming subscriptions, and the "discretionary" income can shrink dramatically before any actual discretionary spending even begins.
Tracking monthly expenses rigorously is a powerful tool to combat this "stealthy drain." Whether through budgeting apps, spreadsheets, or simply reviewing bank statements, understanding where money is truly going is the first step towards control. This does not necessarily mean eliminating every discretionary expense but rather gaining clarity on how recurring costs affect the amount available for savings and investments. "Many clients are genuinely surprised when they see a consolidated report of their monthly outgoings, especially the cumulative cost of their subscriptions and convenience services," notes Mr. Rajesh Kumar, a Certified Financial Planner. "A simple spending audit can reveal significant areas for reallocation towards savings." This balance becomes particularly critical when contemplating new fixed commitments, such as a higher rent or an additional loan EMI, which can lock in higher expenses for years to come.
4. The Vulnerability Gap: Neglecting an Emergency Fund
Building long-term wealth is a marathon, not a sprint. However, the race can be severely disrupted if unexpected expenses repeatedly force an individual to dip into long-term savings or, worse, borrow money at high-interest rates. Life is unpredictable, and emergencies such as medical bills, sudden job loss, unforeseen family responsibilities, or urgent home/vehicle repairs can put immense pressure on even a meticulously planned budget. Without a dedicated emergency fund, these events can derail financial progress, pushing individuals into debt and away from their wealth-building trajectory.
Agarwal strongly recommends maintaining an emergency fund covering at least three to six months of essential expenses. This reserve should be held in a liquid, easily accessible account, such as a high-yield savings account, separate from regular checking and investment accounts. The purpose of this fund is purely to provide a financial cushion during unexpected events, preventing the need to liquidate investments prematurely (potentially incurring losses or taxes) or rely on expensive borrowing instruments like credit cards or personal loans.
Beyond a cash reserve, adequate health insurance is an indispensable safeguard against crippling medical costs. Similarly, term insurance, where needed (especially if one has dependents), provides crucial financial protection against unforeseen life events. For young professionals, these safeguards are just as important as regular investing. While an emergency fund may not generate the same excitement as investing in growth assets, it provides unparalleled peace of mind and acts as a critical firewall, protecting one’s burgeoning wealth from unforeseen shocks. According to a study by the National Centre for Financial Education, a significant portion of the Indian working population lacks adequate emergency savings, making them highly vulnerable to financial distress during crises.
5. The Mindset Mismatch: Treating Savings as a Burden Instead of a Long-Term Habit
The psychological aspect of saving is often overlooked. Trying to save an overly aggressive share of income immediately can be difficult and unsustainable, particularly for young professionals grappling with high rent, student loan repayments, and other living expenses. If the savings target leaves too little room for everyday needs, social life, and personal interests, it can feel like a punitive burden. This often leads to burnout, resentment towards saving, and ultimately, giving up on financial discipline altogether.
Agarwal suggests a more gradual and sustainable approach: "Start with an achievable savings amount and increase it gradually as income rises." For a 25-year-old, saving around 15-20% of monthly take-home pay can be an excellent starting point, with the aim of moving towards 25-30% or even higher as earnings grow and financial obligations potentially decrease (e.g., student loans paid off). The key is to make saving a consistent habit, much like brushing teeth or exercising, rather than a periodic, strenuous effort.
Time is a young investor’s most powerful ally. Consistent investments made over a longer period, even if smaller initially, can harness the power of compounding to achieve substantial long-term financial goals. However, financial discipline need not equate to asceticism or giving up every enjoyable experience. Agarwal emphasizes the importance of balancing "enjoying life today with securing one’s financial future." As salaries increase, young professionals have the unique opportunity to direct a significant part of each increment towards savings, while still allowing some room for considered lifestyle improvements. This balanced approach fosters a positive relationship with money, making savings a rewarding journey rather than a burdensome obligation.
The Path Forward: Cultivating Financial Discipline and Strategic Planning
The journey from a young professional with a rising salary to a financially secure individual with substantial wealth is not linear. It demands a conscious shift in mindset and the cultivation of disciplined money habits. The "salary hike paradox" serves as a crucial reminder that income growth alone is insufficient; effective money management is the cornerstone of true financial prosperity.
The chronology of financial success for young professionals often begins with awareness. Recognizing the pitfalls of lifestyle creep, passive saving, underestimated expenses, and neglecting an emergency fund is the critical first step. This awareness must then translate into actionable strategies:
- Automate Savings: Set up automatic transfers to savings and investment accounts immediately after salary credit.
- Budget and Track: Utilize budgeting tools to understand income and expenditure patterns, identifying areas for optimization.
- Prioritize Emergency Funds: Build and maintain a robust emergency fund as a foundational element of financial security.
- Invest Consistently: Start investing early, even with small amounts, to leverage the power of compounding over time.
- Seek Guidance: Consult with financial advisors to create a personalized financial plan aligned with long-term goals.
The implications of adopting these habits are profound. Beyond accumulating wealth, consistent financial discipline fosters a sense of control, reduces stress, and opens doors to achieving significant life goals, whether it’s buying a home, funding higher education, or securing a comfortable retirement. Conversely, neglecting these habits can lead to perpetual financial anxiety, increased debt, and the frustration of never quite getting ahead, regardless of one’s professional success.
In conclusion, while a salary hike is a welcome recognition of hard work and talent, its true value is unlocked through intelligent financial stewardship. Young professionals stand at a unique vantage point, with time and potential on their side. By consciously choosing to manage their money proactively, cultivating positive financial habits, and viewing savings not as a burden but as an investment in their future selves, they can transform rising incomes into the bedrock of lasting financial freedom and prosperity. The choice to break free from the salary hike paradox lies firmly in their hands.
About the Author
Kirti Jha is a Senior Content Producer at Mint, where she writes on mutual funds, taxation, personal finance and macroeconomic developments. Her reporting focuses on helping readers understand complex financial developments through data-driven, research-backed stories that explain how policy changes, market trends and regulatory decisions affect investors and households.
Before joining Mint, Kirti worked at ET Money, where she specialised in mutual fund research and investment analysis. She tracked portfolio disclosures, fund manager strategies, sectoral allocation shifts and investment trends, distilling large datasets into investor-focused insights. Her work combined quantitative analysis with consumer-centric storytelling, enabling readers to better understand fund positioning, portfolio changes and long-term investment opportunities.
Kirti holds a Bachelor’s degree in Economics from Indraprastha College for Women, University of Delhi, and a Master’s in Finance from the Jindal School of Banking & Finance at O.P. Jindal Global University. Her academic training emphasised analytical thinking, quantitative research and financial decision-making, providing a strong foundation in understanding capital markets, financial systems and economic policy. With a combined experience in investment research and financial journalism, she is committed to producing accurate, accessible and insightful journalism that empowers readers to make well-informed financial decisions.