By News Analysis Desk
Published: October 12, 2026
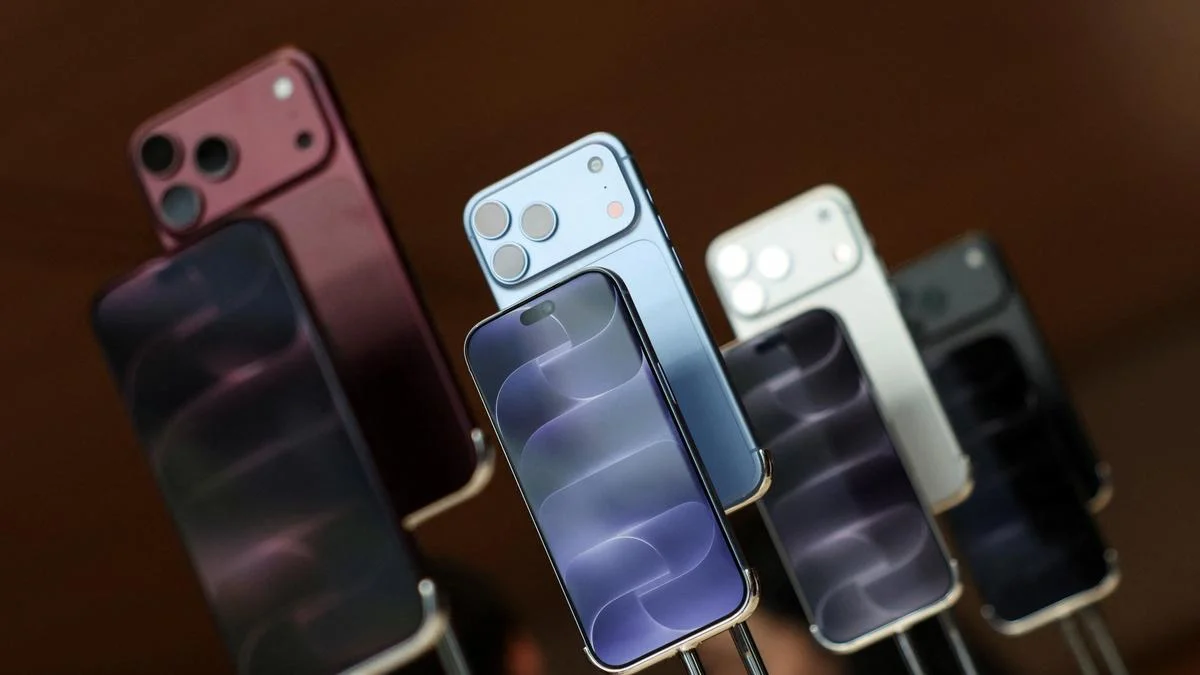
The global smartphone industry has entered its most precarious era since the dawn of the mobile revolution. According to the latest data released by Counterpoint Research for the third quarter of 2026, global smartphone shipments plummeted by a staggering 20% year-over-year (YoY). This contraction marks the lowest quarterly volume recorded since 2012, effectively erasing nearly a decade and a half of growth in the sector.
The primary catalyst for this historic downturn is not a lack of consumer interest in technology, but a crippling supply-side crisis: the skyrocketing cost of memory chips. As the Bill of Materials (BOM) for mobile devices reaches unsustainable levels, manufacturers have been forced to pass costs onto consumers, leading to a 20% surge in retail prices throughout 2026. This "perfect storm" of high production costs and inflated price tags has disrupted original equipment manufacturer (OEM) shipments and altered the competitive landscape of the mobile world.
The Anatomy of a Supply Chain Crisis: The Memory Bottleneck
The crisis began in early 2026 when the semiconductor industry faced a series of unforeseen logistical and material shortages. Specifically, the production of high-density NAND and DRAM chips—essential for the AI-heavy features of modern smartphones—hit a bottleneck. As memory costs escalated, they began to consume a disproportionate share of a smartphone’s total production budget.
Counterpoint Research noted that the inflated BOM costs left OEMs with little room to maneuver. Unlike previous years where manufacturers might absorb minor cost fluctuations to maintain market share, the 2026 memory surge was too significant to ignore. Consequently, shipments were disrupted as brands scaled back production of low-margin models, focusing instead on inventory they could sell at a premium.
By the end of Q3 2026, the global average selling price (ASP) for smartphones had reached an all-time high. The 20% increase in retail prices has effectively priced out millions of consumers in emerging markets, leading to the massive volume decline observed in the quarterly data.
Chronology of the 2026 Market Slump
The descent into the current market state followed a clear, deteriorating timeline:
- Q1 2026: The Initial Squeeze: Early reports from supply chain auditors indicated that memory chip yields were falling below targets. Manufacturers began warning of potential price adjustments for upcoming summer launches.
- Q2 2026: The BOM Explosion: The cost of 256GB and 512GB memory modules—now the industry standard—jumped by nearly 40%. OEMs began cancelling orders for entry-level devices that were no longer profitable to produce.
- Q3 2026: The Shipment Crash: As new flagship and mid-range devices launched with significantly higher price tags, consumer demand hit a wall. Global shipments fell to levels not seen since the era of the iPhone 5 and Samsung Galaxy S3.
- October 2026: Structural Realignment: Brands like Oppo and Vivo began radical internal restructurings to survive the low-volume environment, consolidating sub-brands and narrowing their product portfolios.
Supporting Data: A Brand-by-Brand Breakdown
The Q3 2026 figures reveal a market that is consolidating at the top, even as total volumes shrink. While every major player saw a decline in shipments, the impact was felt unevenly across the "Big Five."
Samsung: The Resilient Leader
Samsung managed to retain its position as the world’s largest smartphone vendor. Despite a 3% YoY decline in its own shipments, the South Korean giant actually saw its market share increase to 23%. This resilience is largely attributed to Samsung’s vertical integration; as a major manufacturer of memory chips itself, Samsung was better positioned to manage BOM costs compared to competitors who rely entirely on external suppliers.
Apple: A Historic High in Market Share
In a surprising turn of events, Apple’s market share crossed the 20% threshold for the first time in a third quarter, reaching 22%. However, this achievement came amidst a volume decline. The dip in shipments was primarily driven by a strategic anomaly: the absence of a base "iPhone 18" model. Apple’s decision to skip a standard entry-level flagship in favor of higher-priced "Pro" and "Ultra" iterations helped maintain revenue and share but left a hole in shipment volumes that would typically be filled by more affordable units.
Xiaomi: The Hardest Hit
Xiaomi faced the most significant challenges among the top three, with shipments plunging more than 30% YoY. Its market share fell to 10% as the brand struggled to reconcile its "value-for-money" identity with the reality of high component costs. Xiaomi’s heavy reliance on the mid-to-low-tier segment made it particularly vulnerable to the memory price hikes, which erased the margins of its popular Redmi and Poco series.

Oppo and Vivo: The Search for Efficiency
Both Oppo and Vivo saw shipments decline by more than 20%. Oppo’s market share settled at 9%, while Vivo followed at 8%. Both companies responded by raising prices across their entry and mid-range portfolios, a move that successfully protected some margin but significantly dampened consumer sell-through.
Official Responses and Strategic Pivots
The industry’s reaction to the Q3 data has been one of defensive consolidation. Analysts and corporate spokespeople have signaled that the "growth-at-all-costs" era is officially over, replaced by a "value-first" survival strategy.
Oppo’s Consolidation Strategy
According to the Counterpoint note, Oppo has taken the drastic step of consolidating its operations across its primary brand, Realme, and OnePlus. The goal is to reduce R&D overlap and improve cost efficiency. By merging supply chain procurement and narrowing the number of unique models launched per year, Oppo hopes to gain better leverage with component suppliers and weather the memory price storm.
Vivo’s Regional Focus
Vivo has pivoted its strategy to focus heavily on its "fortress markets" of India and China. While it is strengthening its budget-friendly Y-series to capture value-conscious consumers, it is simultaneously expanding its premium X, V, and S series to attract high-end buyers who are less sensitive to price hikes. However, Vivo admitted that price hikes have pushed several of its budget models out of key psychological price bands (such as the sub-$200 segment), while persistent stock shortages continue to constrain its ability to meet what demand remains.
Counterpoint Research Outlook
"A meaningful recovery in overall volumes is unlikely until component costs and supply conditions improve," stated the research firm. They warned that production cuts and tighter portfolios are likely to remain the norm for the remainder of 2026 and well into 2027.
Implications for the Future of Mobile Technology
The 20% plunge in shipments carries profound implications for the broader tech ecosystem, ranging from app development to the roll-out of 6G infrastructure.
1. The Death of the "Budget Flagship"
For years, consumers enjoyed "flagship killers"—devices that offered top-tier specs at mid-range prices. The 2026 memory crisis has effectively killed this segment. With BOM costs so high, manufacturers can no longer afford to sell high-spec devices at a discount. The market is bifurcating into ultra-premium devices for the wealthy and strictly utilitarian devices for everyone else.
2. Lengthening Replacement Cycles
As the average price of a smartphone jumps 20%, consumers are holding onto their existing devices for longer. The average replacement cycle, which used to be 24–30 months, is expected to stretch toward 40 months. This shift will force OEMs to focus more on software longevity and after-sales service to keep customers within their ecosystems.
3. The Premiumization of the Market
With volume down, brands are chasing value. We are seeing a "premiumization" of the smartphone market where the focus is on selling fewer units at much higher margins. This is evidenced by Apple and Samsung’s increasing market shares despite falling volumes. Success is no longer measured by how many phones are shipped, but by the Average Selling Price (ASP) and the ecosystem lock-in.
4. Supply Chain Sovereignty
The Q3 2026 crash serves as a wake-up call for governments and corporations regarding semiconductor dependency. The fact that a spike in memory chip costs could cripple a global industry will likely lead to increased investment in localized chip manufacturing and a push for alternative technologies that are less reliant on traditional high-cost memory modules.
Conclusion
The third quarter of 2026 will be remembered as a turning point for the smartphone industry. The 20% drop in shipments and the retreat to 2012-era volumes signal that the mobile market has reached a state of maturity—and fragility. As memory chip costs continue to dictate the rhythm of the market, the coming months will test the resilience of even the world’s largest tech giants. For the consumer, the message is clear: the era of cheap, high-performance mobile technology has paused, replaced by a landscape where every gigabyte of memory comes at a premium.