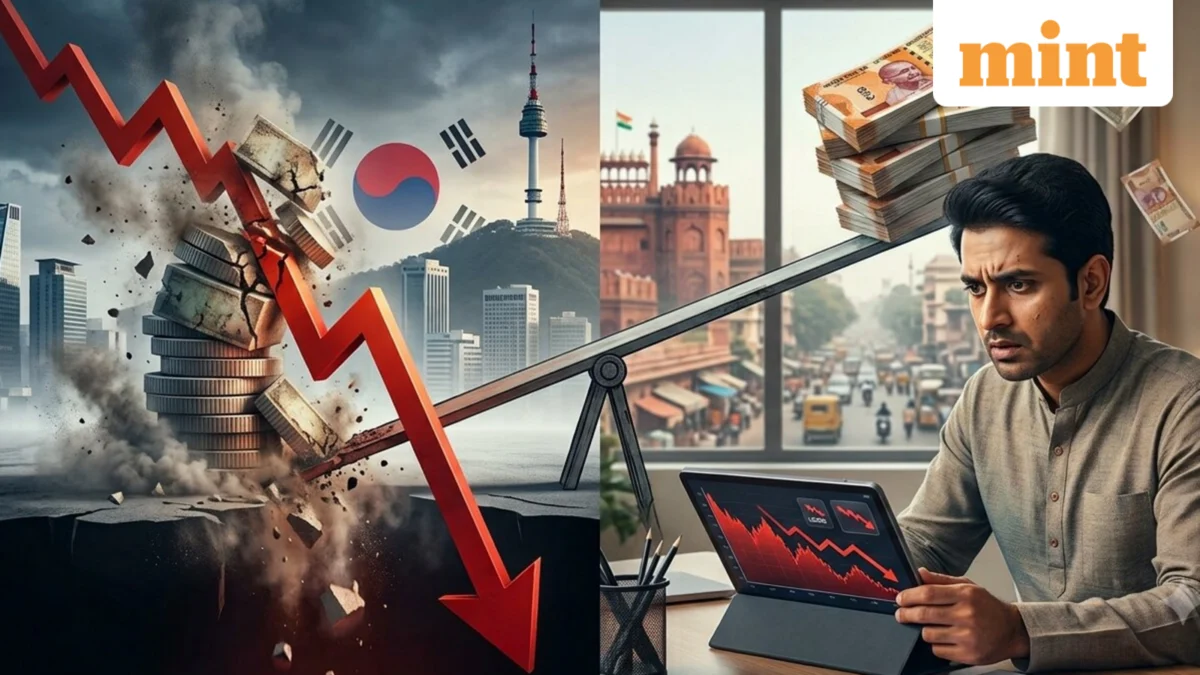
In a stark reminder of the perils lurking within complex financial instruments, retail investors in South Korea have suffered a staggering collective loss of 2.3 trillion won ($1.7 billion) between May and August. The losses, primarily tied to leveraged exchange-traded products (ETPs) tracking the nation’s tech titans—Samsung Electronics and SK Hynix—have sent shockwaves through the financial community. This incident serves as a cautionary tale for retail investors globally, particularly in India, where the appetite for high-octane trading instruments continues to outpace financial literacy.
The Anatomy of the Wipeout: A Chronological Breakdown
The crisis was not an overnight phenomenon but the culmination of months of speculative fervor surrounding the AI-centric semiconductor boom.
- Late May 2024: As anticipation regarding AI-related semiconductor demand reached a fever pitch, South Korean retail investors poured capital into leveraged ETFs and notes that promised 2x or 3x returns on the daily performance of Samsung and SK Hynix.
- June 2024: The market reached a local peak. Optimism was high, and the trading volume for these leveraged products skyrocketed as retail participants sought to "turbocharge" their gains.
- July 2024: The tide turned abruptly. A global market correction triggered a sharp decline in tech stocks. SK Hynix plummeted by approximately 35%, while Samsung Electronics saw a 21% retreat. Because these products were leveraged, the downside was magnified exponentially.
- Late July – August 2024: By July 29, the damage was irreversible for many. The largest 2x SK Hynix fund had shed nearly 82% of its value from its June peak. Panic selling ensued, with roughly $1 billion exiting these specific funds in a single month.
Decoding Leveraged ETFs: The Mathematical Trap
To understand why retail investors lost so much, one must distinguish between "long-term investment" and "daily-reset trading."
Leveraged ETFs are designed to deliver multiples of an underlying asset’s daily return. Sidharth Sogani Jain, founder and CEO of Blue Aster Capital and CREBACO Global, emphasizes that the "daily" aspect is the most misunderstood feature of these products.
"The fund resets its exposure every single day," Jain explains. "Over a month, it does not give you 2x the return. It gives you 2x of each day’s move, compounded. Retail investors often buy these as a long-term turbocharged version of a stock, but in reality, they are short-term trading instruments with an expiry built into their mathematics."
The Scourge of Volatility Decay
The most dangerous feature of these products is "volatility decay." Consider a stock that rises 5% one day and falls 5% the next. A standard investor would be down only 0.25%. However, a 2x leveraged ETF in the same scenario would be down nearly 1%, and a 3x fund would be down over 2%. In a sideways or oscillating market, these funds bleed value even if the underlying stock ends up back at its starting price. Recovery math is even more brutal: if a fund drops by 82%, it requires a staggering 456% gain just to break even.
The South Korean Regulatory Response
The South Korean government, specifically the Financial Services Commission (FSC), faced intense criticism for the regulatory vacuum that allowed retail investors to pile into such high-risk products with little protection.
Following the massive losses, the regulatory response was swift but reactive. Officials increased the minimum cash deposit required to trade these products from 10 million won to 30 million won. Furthermore, they made mandatory education modules and "mock trading" sessions compulsory for retail participants.
However, lawmakers like Choi Eun-seok, who brought these figures to light, argue that the damage was already done. The regulatory framework prioritized market openness, assuming retail investors understood the risks, only to find that the complexity of these products made "informed consent" nearly impossible for the average participant.
Global Implications: The Indian Context
The South Korean experience is a mirror held up to the Indian financial landscape. Indian retail investors have shown an increasing affinity for high-leverage products, primarily through the Futures and Options (F&O) segment.

The SEBI Findings
The Securities and Exchange Board of India (SEBI) recently conducted a comprehensive study that highlighted a grim reality: over 91% of individual derivatives traders in India incurred losses in FY25. The net losses for this group rose by 41% in a single year, totaling approximately ₹1.06 lakh crore.
Just as in Korea, Indian investors are often drawn to the promise of "easy money" and the allure of AI-driven market momentum. Many Indian investors also access US-listed leveraged ETFs through overseas brokerage platforms, often without a full grasp of the tax implications or the structural volatility decay inherent in these instruments.
When Are Leveraged Products Useful?
Institutional investors utilize leveraged ETFs for very specific, short-term strategies. They are generally used as a "scalpel" rather than a "hammer"—positions are measured in days, sized as a tiny fraction of the total portfolio, and monitored with constant risk management.
For the average retail investor, these products become weapons of mass financial destruction when:
- Held for the long term: They are not designed for buy-and-hold strategies.
- Used to "double down" on a conviction: Using leverage to amplify a bet on a sector like semiconductors ignores the inherent cyclicality of the industry.
- Underestimated volatility: Retail investors frequently underestimate how a high-volatility, sideways market will erode their principal through daily resets.
Expert Insight: Building Sustainable Wealth
The consensus among financial professionals is clear: conviction in a theme—whether it is Artificial Intelligence, electric vehicles, or semiconductor manufacturing—is not a valid reason to employ leverage.
"If you have a long-term conviction, use diversified ETFs or buy the underlying stocks directly," advises Jain. "You avoid the compounding risks, you avoid the daily-reset decay, and you allow time to work in your favor rather than against you."
Conclusion: The Lesson for the Future
The $1.7 billion wipeout in South Korea serves as a painful reminder that financial innovation often outpaces the average investor’s understanding of risk. As global markets become more interconnected and complex financial instruments become more accessible through mobile apps and low-barrier-to-entry platforms, the burden of "financial literacy" shifts heavily onto the individual.
Investors must recognize that leverage is a double-edged sword. While it can magnify gains in a unidirectional bull market, it acts as an accelerator for losses in a volatile environment. Before participating in any leveraged product, an investor should be able to answer three questions:
- Do I understand the mathematical impact of daily resets on this product?
- Am I using this as a short-term hedge or a long-term bet (and if the latter, am I aware of why that is a mistake)?
- Can I afford to lose 100% of the capital allocated to this trade?
As regulators globally grapple with the rise of retail derivatives and leveraged products, the South Korean case will likely become a benchmark for future policy. Until then, the most effective protection remains the investor’s own skepticism of "get-rich-quick" instruments that promise outsized returns for minimal effort. True wealth creation, as history consistently shows, is rarely built on the back of daily-reset leverage; it is built on patience, diversification, and a deep understanding of the risks involved.