Main Facts
In the complex world of personal finance, choosing a financial advisor marks a pivotal decision, yet it is merely the first step on a lifelong journey of wealth management. As an investor’s life invariably evolves – with shifts in income, the emergence of new financial goals, and changes in personal responsibilities – the counsel they receive must adapt in kind. The efficacy of this crucial relationship hinges on its ability to evolve dynamically. However, when interactions with an advisor increasingly pivot towards the promotion of novel financial products, rather than a thorough and insightful review of existing investments and an alignment with evolving life stages, it signals a potential misalignment of interests. Such a shift warrants a critical reassessment of the advisory relationship, prompting investors to scrutinize whether their financial partner continues to uphold their fiduciary duty and truly serve their long-term interests.
A robust financial advisory relationship is built on a foundation of trust, transparency, and tailored guidance. Its core purpose is to empower investors to make informed decisions, meticulously aligned with their financial aspirations, risk tolerance, and investment horizon. This entails not just initial goal setting but a continuous process of regular portfolio reviews, clear and comprehensive explanations of all recommendations, and unwavering transparency regarding all associated costs and remuneration structures. When these fundamental pillars begin to erode, or are consistently absent from the engagement, it becomes imperative for investors to evaluate whether their advisor is genuinely acting as a steward of their wealth.
Sanjiv Bajaj, Joint Chairman and Managing Director of Bajaj Capital Ltd, a prominent voice in the Indian financial advisory landscape, succinctly identifies five critical warning signs that investors should vigilantly monitor. These include conversations unduly dominated by the pushing of new products, recommendations delivered without adequate or comprehensible explanations, irregular or perfunctory portfolio reviews, obfuscated or unclear cost structures, and a general breakdown in open and effective communication. Bajaj underscores a crucial tenet: "A good advisor relationship should get more valuable with time. The longer an advisor knows you, the more relevant and meaningful your conversations should become." This statement encapsulates the essence of a truly valuable partnership – one that deepens in understanding and utility over the years, rather than stagnating or devolving into a transactional exchange.
Chronology: The Evolution and Potential Deterioration of the Advisor-Client Relationship
The journey with a financial advisor typically commences with an optimistic "honeymoon" period. During this initial phase, the investor diligently outlines their financial aspirations, details their current financial standing, and perhaps sets forth ambitious goals for the future, whether it be retirement planning, wealth accumulation, or specific asset purchases like a home or higher education for children. The advisor, in turn, performs an initial assessment, crafts a preliminary financial plan, and recommends a foundational portfolio designed to meet these stated objectives. This period is characterized by earnest discussions, a sense of shared purpose, and the establishment of initial trust.
Ideally, as time progresses, this relationship should mature and deepen. A competent advisor would proactively engage with the investor, anticipating life changes, reviewing market shifts, and ensuring the financial plan remains a living document, continually adjusted to reflect new realities. Regular meetings would transcend mere transactional updates, evolving into strategic discussions about future opportunities, risk mitigation, and the optimization of existing holdings. The advisor, armed with a growing understanding of the client’s unique circumstances, psychological comfort with risk, and long-term vision, becomes an indispensable partner, offering increasingly relevant and nuanced advice. This is the stage where the relationship truly "gets more valuable with time," as Bajaj suggests.
However, the trajectory of this relationship can, unfortunately, diverge from this ideal path. The deterioration often begins subtly, almost imperceptibly, with small shifts that gradually erode trust and effectiveness. Perhaps the initial enthusiasm wanes, and meetings become less frequent or more superficial. The focus might gradually shift from the investor’s overarching life goals to the advisor’s immediate targets or the latest product launches. Communication might become less transparent, explanations less thorough, and proactive engagement might give way to reactive responses, or worse, silence. This chronological decline can manifest through the very warning signs identified by Sanjiv Bajaj – a gradual slide from a client-centric partnership to a product-driven or disengaged dynamic. An investor, initially reassured, might slowly find themselves questioning the advice, feeling unheard, or simply becoming disengaged as the advisor’s approach becomes increasingly misaligned with their evolving needs. Understanding this potential chronological decay is key to recognizing the red flags before the financial plan suffers irreversible damage.
Supporting Data: Delving Deeper into the Five Warning Signs
1. The Product-Centric Approach: A Shift from Goals to Sales Targets
One of the most immediate and concerning red flags is an advisor who consistently prioritizes the recommendation of new financial products over a comprehensive review of your existing portfolio and a deep understanding of your current financial position. This dynamic often manifests as an advisor pushing new mutual fund schemes, insurance policies, or other investment vehicles, without first demonstrating a clear understanding of what you already own, how those assets are performing, and whether they still align with your goals.
Why it matters: This product-first mentality can lead to "churning," where an advisor encourages frequent buying and selling of investments not necessarily for the client’s benefit, but to generate commissions or meet sales quotas. It often results in a fragmented, inefficient portfolio that lacks strategic coherence. Such an approach suggests a fundamental misalignment of interests, where the advisor’s agenda (sales) takes precedence over the investor’s objectives (wealth growth, risk management). A truly holistic financial plan considers the entire financial picture, ensuring every component works in harmony towards specific, predefined goals.
Sanjiv Bajaj emphasizes this crucial distinction: "Before suggesting something new, a good advisor should first understand what you already own, what each investment is meant to do for you, and whether anything needs to change." This highlights the importance of context. New investments might occasionally be appropriate, but their recommendation should always stem from a thorough analysis of the investor’s overall financial health and strategic needs, rather than merely the availability of a new product in the market. Investors should proactively ask probing questions: "How does this proposed investment integrate with my existing portfolio?", "What specific financial purpose does it serve?", "Does it address a clear, identified financial need?", and critically, "What are the associated costs and risks compared to my current holdings or alternative solutions?" Without satisfactory answers, caution is warranted.
2. The Enigma of Unexplained Recommendations: Decoding the ‘Why’
An advisor’s role extends beyond merely suggesting investments; it fundamentally involves educating and empowering the investor. If recommendations are consistently made without transparent, understandable explanations regarding their suitability, the inherent risks, the associated costs, or their specific role within the broader portfolio, investors are left unable to make truly informed decisions. This lack of clarity can be profoundly disempowering.
Why it matters: Financial decisions, particularly investment choices, carry significant implications. An investor must comprehend the rationale behind each recommendation to truly own their financial plan. Without understanding the ‘why,’ they cannot effectively evaluate the advice, articulate their strategy to others, or remain committed to the plan during periods of market volatility. Moreover, a reluctance to provide clear explanations can mask unsuitable advice, excessive risk-taking, or investments that primarily benefit the advisor through higher commissions.
An effective advisor should be capable of articulating precisely how a recommendation aligns with the investor’s specific financial goals, their individual risk appetite, and their investment horizon. Investors should not only feel comfortable questioning the advice but should be actively encouraged to do so. Bajaj identifies unclear recommendations and an advisor’s reluctance to engage in thorough explanations as significant warning signs. If an advisor repeatedly fails to provide satisfactory and digestible explanations, it signals a breakdown in the core educational and trust-building aspects of the relationship, necessitating a reassessment of its value and effectiveness.
3. Stagnant Strategies in a Dynamic Life: The Unreviewed Portfolio
Life is a continuum of change, and so too must be a financial plan. Major life events—such as starting a family, navigating career transitions, taking on significant liabilities like a home loan, or approaching the critical juncture of retirement—profoundly alter an individual’s financial landscape. These changes impact income streams, savings capacity, immediate and long-term financial needs, and crucially, an individual’s capacity and comfort with taking investment risks.
Why it matters: A financial strategy that remains static amidst these life-altering events quickly becomes obsolete and potentially detrimental. An old investment approach, once perfectly suitable, might now expose an investor to undue risk, miss out on critical growth opportunities, or fail to adequately prepare for new financial demands. For instance, a growth-oriented portfolio suitable for a young professional might be dangerously aggressive for someone nearing retirement, whose priority has shifted to capital preservation and income generation.
Bajaj succinctly captures this predicament: "Maybe your goals have evolved, but nobody has revisited your investment approach. Or your income or comfort with risk has changed, and it never came up in discussion." This underscores the critical need for proactive, regular portfolio reviews. These reviews should not be mere formalities but substantive discussions designed to reassess priorities, validate current investment strategies against evolving circumstances, and determine if the existing portfolio remains appropriate. Crucially, such reviews should not automatically lead to the purchase of new products but rather to thoughtful adjustments, rebalancing, or strategic changes to existing holdings.
4. The Murky Waters of Fees and Remuneration: Demanding Transparency
Financial advice, like any professional service, comes with a cost, and investors have an absolute right to a crystal-clear understanding of what they are paying for and how their advisor is remunerated. This transparency must extend to all applicable advisory fees, commissions earned on product sales, product-related charges (such as expense ratios in mutual funds), and any other relevant incentives or potential conflicts of interest that might influence the advisor’s recommendations.
Why it matters: Opaque fee structures can lead to investors paying more than necessary, eroding investment returns over time. More importantly, a lack of transparency regarding an advisor’s remuneration model can conceal significant conflicts of interest. For example, an advisor paid primarily through commissions might be incentivized to recommend products that offer higher payouts, irrespective of whether they are the most suitable or cost-effective option for the client. This directly undermines the trust inherent in the advisor-client relationship.
The remuneration structure can vary significantly across different financial services models – from fee-only advisors who charge a flat fee or a percentage of assets under management (AUM) and do not earn commissions, to commission-based advisors, or hybrid models. Regardless of the model, what remains paramount is that investors possess a complete and unambiguous understanding of all applicable costs and potential conflicts of interest before committing to any decision. "You should have a clear picture of what your financial decisions cost and how your advisor is paid," states Bajaj unequivocally. If an advisor is evasive, provides vague answers about charges, or fails to adequately explain potential conflicts, investors must press for clarification before proceeding with any recommendation. This vigilance is crucial for ensuring the advice received is genuinely independent and client-focused.
5. The Breakdown of Dialogue: When Communication Fails
At its core, a successful financial advisor-client relationship is built on a bedrock of trust and open, honest communication. Investors must feel empowered to ask questions, seek clarification, and express concerns without any sense of discomfort, intimidation, or fear of dismissal. This psychological safety is paramount for effective collaboration.
Why it matters: When communication falters, the entire advisory framework crumbles. If an advisor consistently provides evasive answers, dismisses legitimate concerns, or fails to adequately explain decisions, investors are left in a precarious position. They struggle to assess the suitability of the advice, lose confidence in their advisor, and may even disengage from their own financial planning process, leading to suboptimal outcomes. A relationship devoid of open dialogue transforms the advisor from a trusted partner into an unapproachable authority figure, creating a power imbalance that is detrimental to the investor’s interests.
Bajaj highlights the subtle but powerful indicators of this breakdown: "investors should pay attention to situations in which they hesitate to ask questions or do not receive straight answers." This hesitation is a red flag in itself, signifying a lack of psychological safety within the relationship. A financial partnership that stifles open discussion makes it exponentially harder for investors to truly comprehend their investments, understand the rationale behind strategic decisions, and ultimately make confident, informed choices about their financial future. The ability to engage in a respectful, two-way dialogue is non-negotiable for a truly effective and empowering advisory experience.
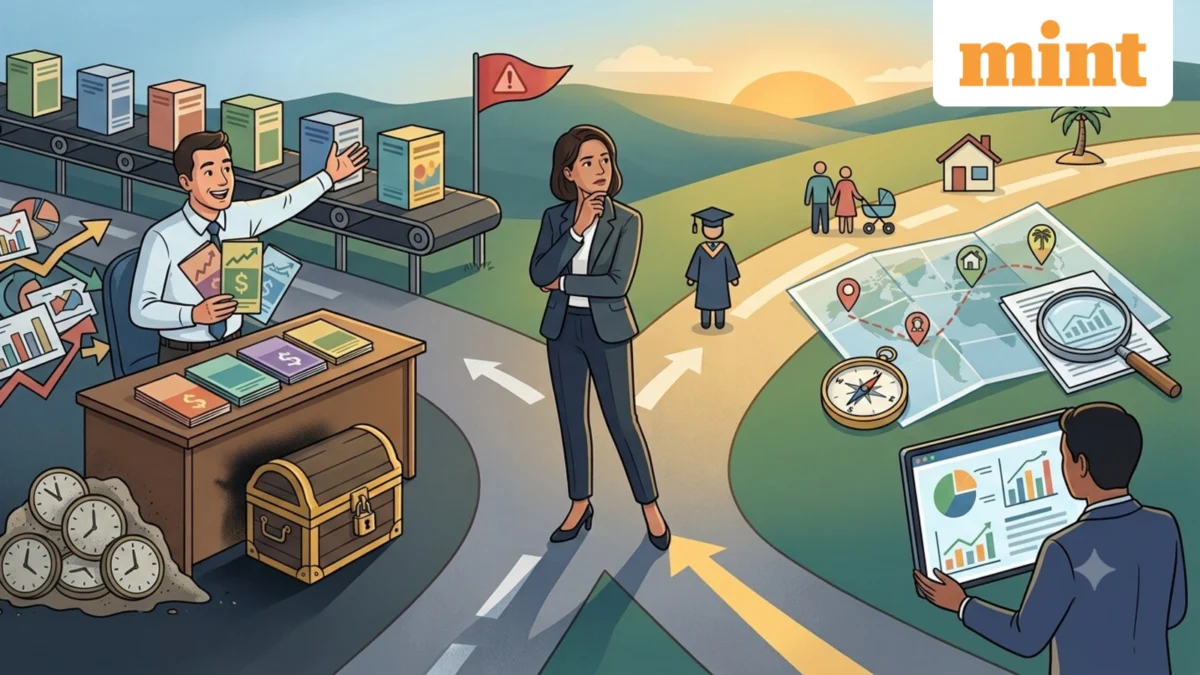
Navigating the Crossroads: When to Consider a Change
Recognizing these warning signs is the first critical step, but acting on them requires careful consideration. Sanjiv Bajaj wisely cautions against impulsive decisions, noting that "a single disappointing interaction or an isolated unsuitable recommendation does not necessarily warrant an immediate change." Trust, once built, deserves an opportunity for repair.
Therefore, investors should adopt a structured approach:
- Step 1: Open Dialogue: The initial response to a perceived problem should always be to raise concerns directly and candidly with the advisor. Articulate precisely what issues have arisen, citing specific instances or patterns of behavior. Document these conversations, including dates, topics discussed, and any commitments made by the advisor.
- Step 2: Evaluate the Response: Observe how the advisor responds. Do they acknowledge the issues? Do they offer satisfactory explanations? More importantly, do they demonstrate a genuine willingness to adapt their approach, improve communication, or provide the necessary transparency? A proactive, apologetic, and constructive response can often salvage the relationship.
- Step 3: Persistent Problems: If, despite these direct discussions, the same problems continue to surface, or if the advisor remains dismissive, uncommunicative, or unwilling to change, then a serious reassessment of the relationship becomes not just appropriate, but necessary. At this juncture, the long-term value proposition of the advisor is clearly compromised.
Before making the definitive decision to switch advisors, investors must undertake thorough due diligence. This includes gaining a comprehensive understanding of their existing holdings, their current investment objectives, any costs associated with transferring assets or exiting products, and the implications of changing service providers. The ultimate objective is not merely to switch for the sake of switching, or because another advisor is promoting new products. Instead, it is to secure a truly client-centric advisory relationship that remains perpetually relevant to their evolving financial needs, providing genuine value and peace of mind.
The Enduring Value of a True Financial Partner
Ultimately, the intrinsic value of a financial advisor transcends the mere number of products recommended or transactions executed. Its true measure lies in the quality of the guidance provided – advice that is objective, well-explained, and meticulously tailored to the investor’s unique circumstances. It resides in the transparency of the relationship, ensuring that all costs, conflicts of interest, and rationales are openly communicated. And crucially, it is found in how effectively the advice adapts to the investor’s changing life stages and financial landscape.
A good financial advisor acts as a steadfast financial partner, a guide through market complexities, a sounding board for critical decisions, and a proactive advocate for the investor’s long-term prosperity. Such a partnership fosters peace of mind, facilitates informed decision-making, and significantly enhances the likelihood of achieving life’s most ambitious financial goals. For investors, therefore, vigilance, active participation, and a willingness to demand the highest standards of service are not just advisable, but absolutely essential in securing and preserving their financial future. The onus is on the investor to remain engaged and empowered, ensuring their financial journey is navigated with a trusted, transparent, and truly client-focused professional at their side.