Introduction: The Psychological and Fiscal Pivot at Sixty
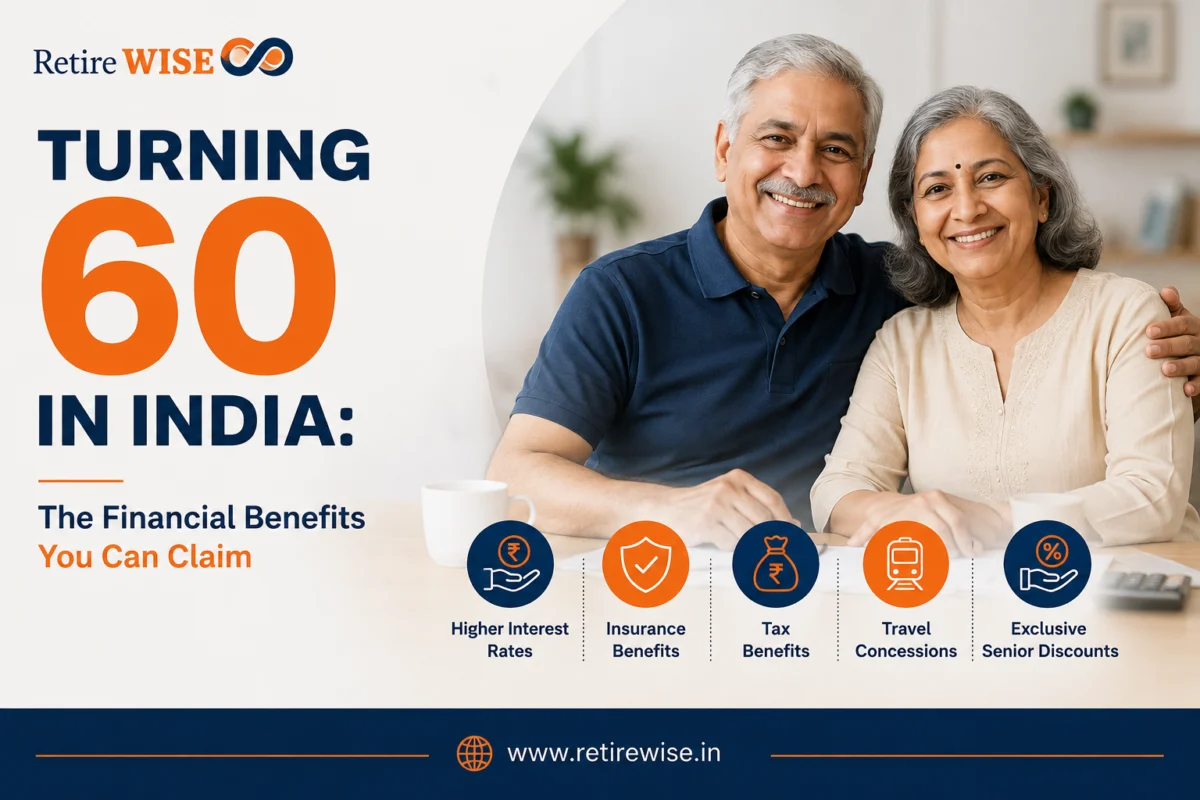
In the Indian socio-economic context, the age of sixty has long been a milestone of transition—from the active pursuit of wealth to its preservation. However, as of August 2026, this transition is no longer just a personal milestone; it is a significant fiscal pivot. Upon reaching sixty, the Indian financial system begins to treat the individual through a different lens. Banks offer higher yields, the Income Tax Department provides broader exemptions, and state-run utilities offer various concessions.
While these benefits are designed to ease the cost of living for retirees, a professional analysis of the current economic climate reveals a stark reality: these perks are a "garnish," not the "meal." With medical inflation hovering in the double digits and the cost of urban living rising, understanding these benefits is essential for cash-flow management, but relying on them as a substitute for a robust retirement corpus is a strategic error.
This report provides a detailed examination of the senior citizen benefit landscape in India as of late 2026, detailing the facts, the chronology of policy shifts, and the long-term implications for retirees.
I. Main Facts: The Current Benefit Infrastructure
As of August 25, 2026, the benefits available to Indian citizens aged 60 and above (and 80 and above for "super-seniors") are structured across three primary pillars: Investment Incentives, Tax Rationalization, and Lifestyle Concessions.
1. Investment and Interest Rate Premiums
The cornerstone of senior financial security remains the Senior Citizens Savings Scheme (SCSS). For the second quarter of the 2026-27 fiscal year, the interest rate is held at 8.2% per annum. This scheme remains the most attractive sovereign-backed fixed-income instrument, allowing a maximum investment of ₹30 lakh per individual. For a retired couple, this effectively means ₹60 lakh can be parked in a high-yield, low-risk environment.
Furthermore, scheduled commercial banks continue the tradition of offering a 0.50% premium on standard Fixed Deposit (FD) rates for seniors. Some institutions, such as the State Bank of India, have introduced "Patron" tiers for those over 80, offering an additional 0.10% to 0.15% over the standard senior rate.
2. The Tax Regime Dichotomy
Taxation for seniors in 2026 is defined by the choice between the "Old Regime" and the "New Regime."
- Old Regime: Maintains a higher basic exemption limit of ₹3,00,000 for seniors and ₹5,00,000 for super-seniors. It allows for critical deductions under Section 80D (Health Insurance up to ₹50,000) and Section 80TTB (Interest income up to ₹50,000).
- New Regime (Default): As of 2026, this has become the preferred route for many, as it offers a full tax rebate for income up to ₹12,00,000. For pensioners, the inclusion of the standard deduction effectively pushes the tax-free limit toward ₹12.75 lakh, though it eliminates the ability to claim specific health or interest-based deductions.
3. Operational and Lifestyle Perks
Beyond the balance sheet, seniors receive priority in various sectors:
- TDS Thresholds: The threshold for Tax Deducted at Source (TDS) on interest income stands at ₹1,00,000 per bank.
- Healthcare: Priority queues at government hospitals and subsidized diagnostic services through the CGHS (for former government employees) or state-specific senior health cards.
- Transport: While railway concessions remain a point of contention, state-run bus services offer discounts ranging from 50% to 100%.
II. Chronology: The Evolution of Senior Benefits (2020–2026)
To understand the current state of benefits, one must look at the policy shifts over the last six years, which have moved away from universal subsidies toward targeted fiscal tools.
- March 2020: The Ministry of Railways suspended all senior citizen fare concessions during the COVID-19 pandemic. Despite repeated petitions to the Supreme Court and Parliament, these concessions have not been restored as of August 2026, citing the Indian Railways’ operational deficit.
- March 2023: The Pradhan Mantri Vaya Vandana Yojana (PMVVY), a popular LIC-managed pension scheme, reached its sunset clause and was not renewed. This consolidated the SCSS as the primary government-backed high-yield option.
- April 2025: The Union Budget officially made the New Tax Regime the "default" for all taxpayers, significantly increasing the rebate limits to simplify compliance for retirees who no longer wish to track investment proofs.
- April 1, 2026: A landmark shift in tax administration occurred with the introduction of Form 121. This unified declaration replaced the decades-old Forms 15G and 15H. Designed for the digital-first era, Form 121 allows seniors to declare their nil-tax liability across multiple financial institutions through a single digital portal, preventing unnecessary TDS.
III. Supporting Data: The Erosion of Purchasing Power
While an 8.2% return on SCSS or a 7.5% return on a Senior FD appears generous, the data suggests a more complex story when adjusted for inflation and taxation.
| Financial Variable | Value (Aug 2026) | Impact on Senior Income |
|---|---|---|
| SCSS Interest Rate | 8.2% | High nominal safety; taxable under slabs. |
| Avg. Senior FD Rate | 7.3% – 7.7% | Competitive, but often trails medical inflation. |
| Medical Inflation (India) | ~12% – 14% | Outpaces almost all fixed-income returns. |
| Form 121 TDS Limit | ₹1,00,000 | Eases immediate cash flow; does not reduce tax liability. |
| New Regime Rebate | Up to ₹12L | Beneficial for those with moderate pensions. |
The "Real" Rate of Return:
For a senior in the 20% tax bracket (Old Regime) invested in an 8.2% SCSS, the post-tax return is approximately 6.56%. If the consumer price index (CPI) for seniors—which is heavily weighted toward healthcare and services—is 7%, the retiree is effectively experiencing a negative real rate of return of -0.44%. This data underscores why benefits alone cannot sustain a three-decade retirement.
IV. Official Responses and Policy Context
The Government of India and the Reserve Bank of India (RBI) have maintained a consistent stance regarding the "Senior-First" fiscal policy.
Ministry of Finance:
Officials have stated that the introduction of Form 121 in 2026 was a response to "the growing administrative burden on the elderly." By unifying the declaration process, the government aims to reduce the "paperwork friction" that often led to seniors having their capital locked in tax refunds for 12 to 18 months.
Ministry of Railways:
In a recent parliamentary session (July 2026), the Railway Minister reiterated that while the government "respects the contributions of elders," the focus has shifted toward providing physical comforts—such as escalators, lifts, and lower-berth quotas—rather than fare subsidies. The official position remains that the subsidy burden on the railways is already at 55% for all passengers, making further concessions fiscally unsustainable.
RBI and Banking Sector:
The RBI has encouraged banks to maintain the 0.5% premium for seniors as a "social stability measure." However, they have also cautioned seniors against "yield-chasing" in unregulated cooperative banks, emphasizing that the Deposit Insurance and Credit Guarantee Corporation (DICGC) only covers up to ₹5 lakh.
V. Implications: The "Perk vs. Plan" Dilemma
The enrichment of senior benefits in 2026 brings to light several critical implications for those currently in or entering retirement.
1. The Trap of "Safety Bias"
The existence of "Senior FDs" and "SCSS" creates a psychological safety net that often traps retirees in low-growth assets. With life expectancy in urban India rising toward the mid-80s, a 60-year-old may need their money to last 25-30 years. Relying solely on these "benefits" ignores the necessity of equity exposure to combat long-term inflation.
2. The Health Insurance Imperative
Section 80D offers a ₹50,000 deduction, but the actual cost of a comprehensive health policy for a 65-year-old couple in 2026 often exceeds ₹80,000 to ₹1,20,000 per annum. The "benefit" covers only a fraction of the premium. This implies that the most critical "benefit" a senior can give themselves is a robust health cover secured before they turn sixty.
3. Reverse Mortgage: The Underutilized Safety Valve
As property values in Indian metros have surged, many seniors are "asset-rich but cash-poor." While not a government "concession" in the traditional sense, the regulatory framework for reverse mortgages has been streamlined in 2026. This allows seniors to monetize their primary residence for monthly income without vacating the property—an essential tool for those whose corpus has been eroded by inflation.
4. The Unified Tax Declaration (Form 121)
The shift to Form 121 signifies a broader move toward the digitization of the silver economy. Seniors who are not "tech-savvy" risk missing out on these administrative benefits. The implication is clear: financial literacy and digital literacy are now inseparable components of a successful retirement.
Conclusion: Garnish vs. Meal
The suite of senior citizen benefits available in India in 2026 is arguably the most comprehensive it has ever been. From the 8.2% SCSS to the simplified Form 121 and the generous New Tax Regime rebates, the "cushion" is well-padded.
However, a professional journalistic audit of these perks reveals that they are designed to ease the cost of living, not to fund it. The fundamental pillars of a dignified retirement remain a well-diversified corpus, adequate health insurance, and a strategic withdrawal plan.
As we move further into 2026, the message for India’s elders is clear: Claim every concession, utilize every tax break, and enjoy every discount. You have earned them. But never mistake these peripheral perks for the core engine of your financial freedom. The perks are the garnish; your planning is the meal.