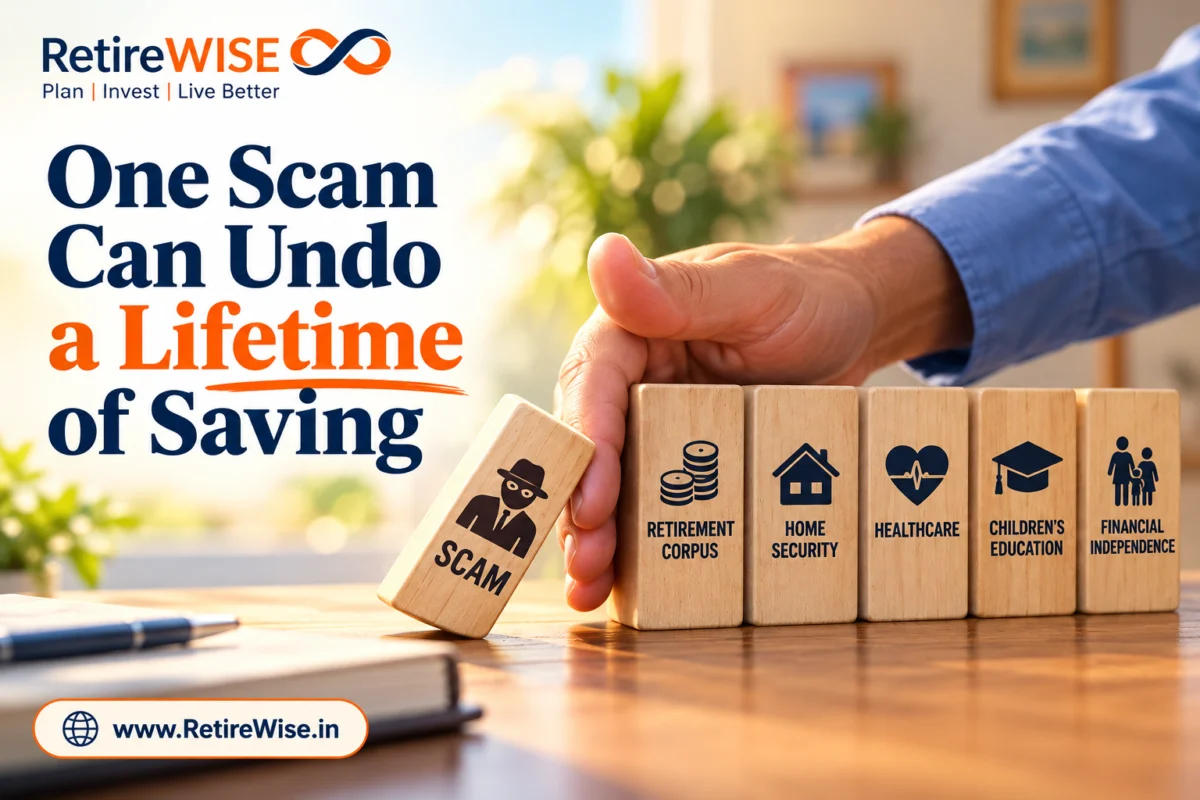
In an era of digital transformation, the greatest threat to a retiree’s financial security is no longer market volatility or inflation, but the sophisticated evolution of cyber-fraud. Experts warn that while markets eventually recover, a single scam can permanently erase a lifetime of labor.
As the global financial landscape shifts toward digital-first interactions, a silent epidemic is targeting the most vulnerable segment of the economic population: retirees. For decades, financial planning focused almost exclusively on wealth accumulation and the mitigation of market risk. However, a new and more predatory variable has entered the equation. Today, a successful retirement is no longer just about how much one earns or saves, but about how effectively one can defend those savings from a burgeoning industry of international cyber-criminals.
Main Facts: The Terminal Nature of Retirement Fraud
The fundamental difference between a financial loss in one’s 30s and a loss in one’s 70s is the "recovery window." During the accumulation phase of life, a professional has two primary safety nets: a recurring monthly salary and the luxury of time. If an investment fails or a mistake is made, the individual can adjust their lifestyle, work longer, or wait for market cycles to turn.
In retirement, these safety nets vanish. The corpus sitting in bank accounts and mutual funds is the final reservoir of a lifetime’s effort. It is the only barrier between independence and a precarious reliance on children or the state.
"It is about preserving what I have earned," says Hemant Beniwal, a veteran financial planner. "Of all the risks a retiree faces, a scam is the one with no recovery. A market crash takes your money and gives much of it back over a few years. A scam takes it and is gone forever."
The scale of the problem is staggering. According to recent reports from the National Cyber Crime Reporting Portal, senior citizens are increasingly the primary targets for "Digital Arrest" scams, KYC update frauds, and sophisticated social engineering attacks. The damage is not merely financial; it is psychological, often leading to a loss of dignity and the "longevity risk" where a retiree outlives their remaining, diminished assets.
Chronology of a Crisis: The Anatomy of a Modern Scam
To understand how high-net-worth individuals and educated professionals fall victim to these schemes, one must examine the methodical chronology of a typical "Digital Arrest" scam—a trend that has seen a meteoric rise in 2024 and 2025.
Phase 1: The Information Harvest
The scam does not begin with the phone call; it begins with data. Fraudsters often purchase leaked databases containing personal details. They know where a target’s children study, their past professional history, and even their general residential area. This "homework" provides the veneer of legitimacy required to bypass initial skepticism.
Phase 2: The Hook and Isolation
The victim receives a call, often via WhatsApp or a spoofed official number, claiming to be from the Police, the Narcotics Control Bureau (NCB), or a federal investigative agency. The "hook" is usually a fabricated crisis—a package containing illegal drugs addressed to the victim, or a family member being detained in a criminal case.
Phase 3: The "Digital Arrest"
The victim is told they are under "digital arrest." They are ordered to keep their camera on and are forbidden from contacting anyone, including family members or lawyers. This isolation is critical; it prevents the victim from seeking a second opinion that would break the spell of fear.
Phase 4: The Financial Siphoning
Once the victim is in a state of total panic, the "officer" offers a way out: a "refundable" security deposit to clear their name or to facilitate a "secret investigation." This is where the life savings are moved. In one documented case, an Army veteran was methodically questioned about his fixed deposits and gold holdings before being coerced into transferring ₹1.28 crore.
Supporting Data: The Rising Cost of Vulnerability
The data surrounding cyber-fraud in India and among the NRI (Non-Resident Indian) community suggests that education and professional success are no longer adequate shields.
- The Scale of Loss: Recent data from the Indian Cyber Crime Coordination Centre (I4C) indicates that Indians lost over ₹1,750 crore to cyber-criminals in just the first four months of 2024.
- The Target Profile: Contrary to the myth that only the "tech-illiterate" are scammed, a significant portion of victims are retired professionals, including doctors, engineers, and former military officers.
- The AI Factor: The emergence of Generative AI has introduced "Voice Cloning." With just a few seconds of audio from a social media video, scammers can replicate the voice of a child or grandchild, making "emergency" calls for money appear indistinguishable from reality.
Financial planners now argue that the "real cost" of a scam should be measured in years. If a retiree loses ₹50 lakh, they haven’t just lost the principal; they have lost the ₹4 lakh in annual income that capital would have generated for the next 20 years.
Official Responses and Protective Measures
The Indian government and financial regulators have stepped up efforts to combat this menace, but they emphasize that "citizen awareness" remains the first line of defense.
The National Helpline (1930)
The Ministry of Home Affairs (MHA) has established the 1930 National Cyber-Fraud Helpline. The "Golden Hour"—the first 60 minutes after a transaction—is critical. If reported within this window, the banking system has a significantly higher chance of freezing the funds before they are laundered through a chain of mule accounts.
Regulatory Directives
The Reserve Bank of India (RBI) and SEBI have implemented stricter Two-Factor Authentication (2FA) and "cooling-off" periods for adding new beneficiaries. However, scammers often bypass these by convincing the victims to share their OTPs (One-Time Passwords) or screen-sharing access.
The "Friction" Strategy
Financial advisors are now recommending a structural approach to money management to prevent total loss. This involves:
- Limited Liquidity: Keeping only essential funds in a primary savings account linked to a UPI or debit card.
- Asset Layering: Holding the bulk of a corpus in Mutual Funds or Fixed Deposits. Because these assets require a T+1 or T+2 settlement period to reach a bank account, they provide a "forced pause" that can allow a victim to snap out of a panicked state before the money is sent to a stranger.
Implications: The Shift in Retirement Planning
The rise of cyber-scams is fundamentally changing the role of the financial advisor. Modern retirement planning is evolving from a purely mathematical exercise into a behavioral and protective one.
The Family Password Protocol
One of the most effective non-technological defenses being advocated is the "Family Password." Families are encouraged to agree on a secret word or phrase that is never shared online. If a family member calls in a panic asking for money, the recipient asks for the password. If the caller cannot provide it, the call is immediately flagged as a deepfake or a scam.
The De-Stigmatization of Victimhood
A major implication of these scams is the role of "shame." Scammers rely on the fact that victims, especially proud retirees, may feel too embarrassed to admit they were fooled. This silence allows the scammer more time to move the funds. Experts urge adult children to create a "safe space" for their parents to report mistakes immediately.
The New "Security" Standard
In the past, a "secure" retirement meant a diversified portfolio. In 2024 and beyond, a secure retirement requires:
- Digital Hygiene: Regular updates of passwords and the use of dedicated devices for financial transactions.
- Independent Verification: A hard rule of "Verify then Trust." If a bank calls, the consumer hangs up and calls the official number found on the back of their physical debit card.
- Pressure Resistance: Recognizing that any "authority" that demands immediate payment or threatens arrest over a video call is, by definition, fraudulent.
Conclusion: Guarding the Golden Years
The journey to a comfortable retirement often spans thirty to forty years of disciplined saving and prudent investing. It is a tragedy of the modern age that this decades-long effort can be dismantled in thirty minutes of psychological manipulation.
As the "Digital Arrest" and AI-cloning scams become more pervasive, the financial industry must prioritize "Defensive Planning" alongside "Growth Planning." For the retiree, the message is clear: The biggest risk to your lifestyle isn’t a 10% drop in the stock market; it is the person on the other end of the phone claiming there is an emergency.
By implementing "friction" in financial structures, adopting family safety protocols, and utilizing official reporting channels like 1930, retirees can ensure that their lifetime of work remains a legacy for their family, rather than a windfall for a criminal. The preservation of the corpus is no longer a passive act—it is an active, daily discipline.