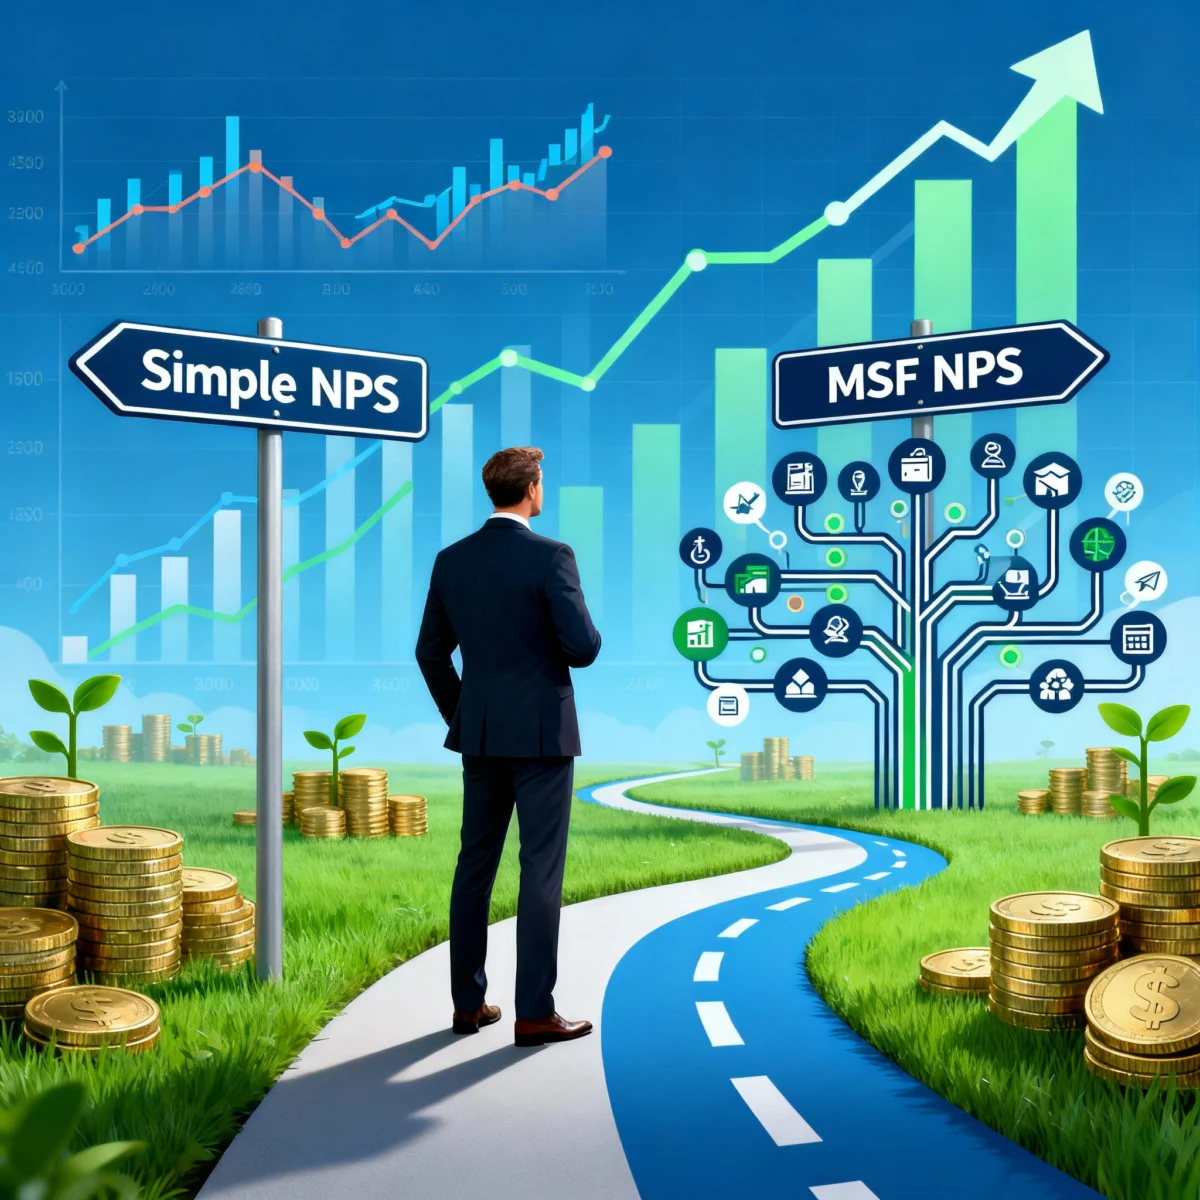
The National Pension System (NPS), long lauded for its simplicity and low cost, has historically struggled to capture the imagination of investors compared to more established products like mutual funds and insurance plans. In a significant strategic pivot, the Pension Fund Regulatory and Development Authority (PFRDA) has introduced the Multiple Scheme Framework (MSF), a move designed to inject greater choice and flexibility into the NPS ecosystem. While ostensibly a positive development promising a more tailored investment experience, questions linger: is this the evolutionary leap NPS needs, or a move that risks diluting its core strengths and introducing unnecessary complexity?
The Genesis of MSF: Addressing NPS’s Growth Conundrum
For years, NPS subscribers were largely confined to a binary choice: either an "Active Choice" or an "Auto Choice" scheme. These were often referred to as common schemes. Under the Active Choice, investors could manually allocate their funds across equity (E), government bonds (G), and corporate bonds (C), with a statutory cap on equity exposure at 75%. The Auto Choice, conversely, offered a pre-determined asset allocation strategy that adjusted automatically based on the investor’s age, following predefined lifecycle fund models. While straightforward and cost-effective, this limited flexibility often failed to resonate with a diverse investor base seeking more nuanced investment pathways.
The PFRDA’s introduction of the MSF framework signals a departure from this rigid structure. Under MSF, Pension Fund Managers (PFMs) – entities like ICICI Prudential, HDFC Pension, SBI Pension Funds, UTI Retirement Solutions, and Kotak Pension Fund – are empowered to design and launch their own bespoke schemes. This opens a vista of possibilities beyond the traditional Active and Auto choices, allowing for greater personalization and catering to specific investor segments.
Unpacking the Multiple Scheme Framework: A New Era of Customization
The core of the MSF lies in its ability to offer subscribers a more diverse and adaptable investment landscape. Here are the key differentiators and features of the new framework:
Enhanced Equity Exposure:
A significant departure from the existing structure, MSF schemes allow for equity exposure to be ramped up to a maximum of 100%. This contrasts sharply with the 75% cap prevalent in the Active and Auto choice schemes. This increased equity allocation is designed to cater to investors with a higher risk appetite seeking potentially greater capital appreciation, particularly in their younger years.
Multi-Scheme Investment Capability:
Perhaps the most transformative aspect of MSF is the ability for subscribers to invest in more than one scheme concurrently. This breaks the previous one-scheme-per-subscriber limitation. Furthermore, investors can even hold a combination of MSF schemes and the legacy common schemes (Active/Auto) simultaneously, offering an unprecedented level of portfolio diversification within the NPS umbrella.
Targeted Scheme Design by PFMs:
The MSF provides PFMs with a "blank canvas," subject to PFRDA approval, to create schemes tailored to specific investor profiles. This includes:
- Age-Based Segmentation: PFMs can design schemes specifically for different age cohorts, such as young earners (e.g., 25-40 years), middle-aged individuals (e.g., 40-55 years), and those nearing retirement.
- Occupational and Segment-Specific Schemes: The framework allows for the creation of schemes targeted at particular professions or employment types, such as gig workers, the self-employed, entrepreneurs, and consultants. This acknowledges the unique financial planning needs of these dynamic segments.
- Risk Profile Variants: For each scheme launched, PFMs are mandated to offer both high-risk and moderate-risk variants. The option to introduce a low-risk variant is also available, further refining the risk-return spectrum for investors.
Flexible Vesting Periods and Exit Options:
A crucial innovation under MSF is the introduction of a minimum vesting period of 15 years. This is a significant departure from the traditional NPS structure where regular exit is typically linked to reaching the age of 60 or superannuation.
- Regular Exit Under MSF: With MSF, a regular exit can be availed after the completion of the 15-year vesting period, irrespective of the subscriber’s age. This means an individual who starts investing at 30 could potentially access their funds at 45, aligning with other life goals such as children’s education or home purchases, in addition to retirement planning.
- Premature Exit Rules: The rules governing premature exits remain largely consistent across both common and MSF schemes. In such scenarios, at least 80% of the corpus must be used for purchasing an annuity, with the remaining 20% available for lump-sum withdrawal.
- Proposed Changes to Withdrawal Norms: PFRDA has put forth a proposal to significantly alter the withdrawal norms for regular exits. The suggested changes include hiking the lump-sum withdrawal limit from the current 60% to a substantial 80%, consequently reducing the mandatory annuity purchase from 40% to a mere 20%. While this proposal is still under consideration, its likely approval suggests a move towards greater liquidity for NPS investors.
Tax Implications Remain Consistent (for now):
Despite the proposed changes in withdrawal percentages, the tax treatment of lump-sum withdrawals under Section 10(12A) of the Income Tax Act remains unchanged for now. This section exempts up to 60% of the accumulated corpus from taxation. Therefore, even if the lump-sum withdrawal limit increases to 80%, the excess 20% would likely be taxed at the individual’s applicable income tax slab rate, unless the government simultaneously revises the tax-exempt limit.
Expense Ratio Adjustments:
While the common schemes maintain their expense ratio cap at 0.1% per annum, MSF schemes will operate under a slightly higher cap of 0.3% per annum. While this is still considerably lower than the expense ratios often associated with actively managed mutual funds, it represents an increase for those opting for MSF products.
A Chronology of Change: The Evolution of NPS Investment Options
To fully appreciate the significance of the MSF, it’s helpful to trace the evolution of NPS investment choices:
- Pre-MSF Era (Focus on Simplicity and Low Cost): NPS was established with a core philosophy of being a simple, low-cost retirement savings vehicle. Investment options were limited to two broad categories: Active Choice and Auto Choice. Each PFM offered a limited set of common funds (E, G, C) under the Active Choice, and a set of age-based lifecycle funds under the Auto Choice. The emphasis was on a unified and straightforward approach.
- The Need for Greater Appeal: Despite its merits, NPS struggled to attract the same level of investment as mutual funds or insurance products. This led to a PFRDA introspection on how to make NPS more competitive and appealing to a wider audience.
- Introduction of MSF (2023 onwards): The PFRDA’s launch of the Multiple Scheme Framework marks a deliberate attempt to inject more choice, customization, and potential for earlier access to funds. This move is aimed at making NPS a more attractive proposition for diverse investor segments and potentially increasing its market share.
Supporting Data and PFM Initiatives
The rationale behind MSF is underscored by the proactive steps taken by PFMs to align with the new framework. Leading PFMs have already begun outlining their strategies and introducing new schemes under the MSF. For instance:
- UTI Retirement Solutions and HDFC Pension Fund Managers have published detailed explanations of the MSF on their respective platforms, showcasing their preparedness and outlining the enhanced investment avenues available to subscribers. These resources often provide illustrative examples of how MSF schemes can be structured to cater to different risk appetites and investment horizons.
The table below summarizes the key differences between the existing NPS structure and the MSF framework:
| Feature | Existing NPS (Common Schemes) | NPS with MSF |
|---|---|---|
| Number of Schemes | Limited to one scheme per subscriber | Can hold multiple schemes; can also hold MSF and common schemes concurrently. |
| Equity Exposure Cap | Maximum 75% | Up to 100% in high-risk schemes. |
| Vesting Period | Age 60 or superannuation | Minimum 15 years vesting period (can be higher). |
| Switching Funds | Between Active and Auto schemes | Within MSF schemes post-vesting; MSF to common scheme permitted before vesting completion. |
| Expense Ratio | Capped at 0.1% p.a. | Capped at 0.3% p.a. for MSF schemes; 0.1% p.a. for common schemes. |
| Investor Segmentation | Generalized schemes | PFMs can launch schemes for specific age groups, professions, and risk profiles. |
| Mandatory Annuity | 40% for regular exit; 80% for premature exit. | Same as above. PFRDA has proposed reducing regular exit annuity to 20%. |
| Tax Implications | Up to 60% tax-exempt under Sec 10(12A). | Same tax rules apply for now. |
| Flexibility & Complexity | Simple, easy to understand | More choice, but increased complexity. |
Official Responses and PFRDA’s Strategic Vision
PFRDA’s introduction of MSF is a calculated move aimed at addressing several perceived shortcomings of the NPS. The regulator’s quandary is clear: NPS, despite its inherent strengths like low costs and tax benefits, has not achieved the market penetration envisioned.
PFRDA’s stated objectives with MSF appear to be multi-pronged:
- Enhancing Investor Attractiveness: By offering greater choice and flexibility, PFRDA aims to make NPS more appealing to a wider spectrum of investors, potentially drawing them away from competing products.
- Catering to Diverse Needs: The ability to design schemes for specific age groups, professions, and risk profiles acknowledges that a one-size-fits-all approach is no longer sufficient in today’s dynamic financial landscape.
- Facilitating Early Access to Funds: The 15-year vesting period and the proposed changes to withdrawal norms aim to make NPS a more versatile financial tool, capable of supporting goals beyond retirement. This is particularly relevant for segments like freelancers and the self-employed who may require earlier access to their savings.
- Addressing Competition: It’s plausible that the PFRDA is also keen to counter the growing appeal of other investment products and potentially address subscriber attrition to schemes like the Unified Pension Scheme (UPS).
In essence, PFRDA seeks to "kill multiple birds with a single arrow" by revitalizing NPS, making it more adaptable, and ultimately, more successful in attracting and retaining investors. The proposed changes to exit and withdrawal rules are further evidence of this intent, aiming to alleviate long-standing concerns about liquidity.
Implications and the Debate on Simplicity vs. Complexity
The introduction of MSF brings a host of implications, both positive and potentially negative:
Positive Implications:
- Greater Customization: Investors can now build portfolios that align precisely with their risk tolerance, investment horizon, and specific financial goals.
- Enhanced Growth Potential: The 100% equity exposure option offers the potential for higher returns, albeit with increased risk.
- Improved Liquidity for Non-Retirement Goals: The 15-year vesting period and proposed withdrawal changes can make NPS a viable tool for medium-term financial planning, not just long-term retirement.
- Inclusion of Under-served Segments: Tailored schemes can better serve the unique needs of freelancers, entrepreneurs, and other non-traditional workforce segments.
Potential Drawbacks and Concerns:
- Erosion of Simplicity: The core appeal of NPS has been its straightforward nature. The introduction of multiple scheme options, each with its own nuances and investment strategies, risks transforming NPS into a complex product, mirroring the intricacies of mutual fund selection. This can be daunting for the average investor who might have been attracted to NPS precisely for its ease of understanding.
- Increased Complexity in Selection: Choosing the right MSF scheme, or a combination of schemes, will require a deeper understanding of investment products and risk assessment. This could lead to confusion and potentially suboptimal investment decisions for less-informed investors.
- Higher Expense Ratios: While still competitive, the increased expense ratio cap for MSF schemes (0.3% vs. 0.1%) means a slightly higher cost for investors opting for these more flexible options.
- Questioning the Tax Advantage: A pertinent question arises: if NPS begins to offer the liquidity and flexibility akin to mutual funds, does it still warrant the tax benefits that mutual funds do not typically receive? This could lead to a broader debate on the differential tax treatment of various investment products.
The author of the original article expresses a significant concern that MSF might be "ruining a perfectly good investment product" by sacrificing its core simplicity. The argument is that NPS was already a decent product, and the addition of MSF, while understandable from PFRDA’s perspective of needing to boost growth, might be an overcorrection. The voluntary nature of MSF offers a silver lining, allowing existing investors to continue with their current strategy if they prefer.
What Should You Do About NPS MSF?
For existing NPS subscribers, the introduction of MSF presents a clear choice:
- Continue with the Status Quo: If you are comfortable with the simplicity and cost-effectiveness of the existing Active or Auto choice schemes, there is no immediate need to switch or explore MSF. Your current investment strategy remains valid.
- Evaluate Your Needs: If you find the limitations of the current NPS structure restrictive, or if you believe the new MSF options align better with your financial goals, it is worth exploring.
- Understand the Schemes: Thoroughly research the new MSF schemes being launched by PFMs. Pay close attention to their investment objectives, asset allocation strategies, risk profiles, vesting periods, and expense ratios.
- Assess Your Risk Appetite: Determine if the higher equity exposure and diversified fund options offered under MSF are suitable for your risk tolerance.
- Consider Your Life Goals: Evaluate if the potential for earlier access to funds under MSF aligns with any medium-term financial goals you may have.
- Seek Professional Advice: If you are unsure about how MSF impacts your investment strategy or which schemes to choose, consult a qualified financial advisor. They can help you assess your individual circumstances and make informed decisions.
The MSF represents a significant evolution in the NPS landscape. While it offers a promising path towards greater investor choice and customization, it also necessitates a careful consideration of the trade-offs between simplicity and complexity. As PFRDA continues to refine the NPS ecosystem, investors will need to stay informed and make choices that best serve their long-term financial well-being.