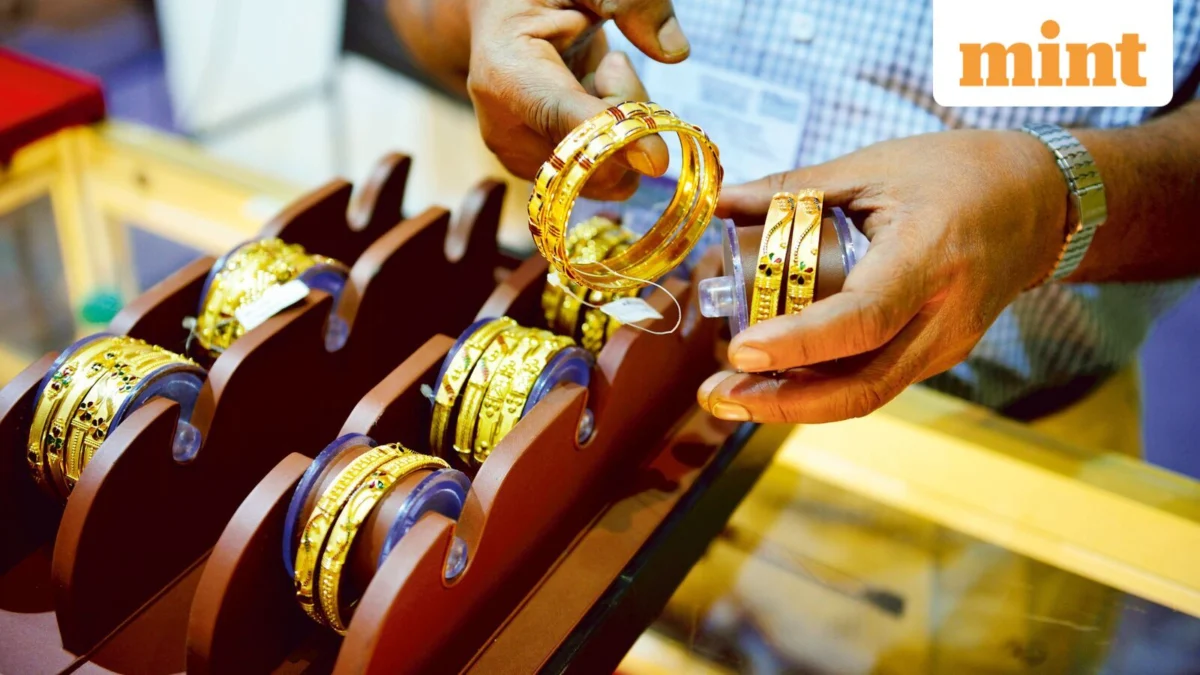
As the festive season descends upon India, the allure of gold—an asset class deeply woven into the nation’s cultural and spiritual fabric—reaches its annual peak. From the auspicious days of Dhanteras to the celebratory spirit of Akshaya Tritiya, households across the country flock to jewellery showrooms to acquire gold in the form of ornaments, bars, and coins.
However, amidst the glitter and the tradition, there lies a complex framework of tax regulations and compliance requirements. While the act of buying gold is a personal choice, the manner in which one transacts—specifically regarding cash payments and documentation—is governed by stringent Income-tax laws. As you prepare your budget for this year’s festivities, it is imperative to understand the legal boundaries that protect both the buyer and the seller.
The Cultural Significance vs. Legal Reality
In India, gold is more than just an investment; it is a store of value, a hedge against inflation, and a symbol of prosperity. Historically, it has served as the primary financial safety net for families. Because of this, many consumers remain unaware of the regulatory scrutiny that accompanies high-value transactions.
The primary objective of the government’s current regulations is not to discourage the purchase of gold, but to ensure that the source of funds used for these purchases is transparent and accounted for. As authorities move toward a more digitized economy, the "under-the-table" cash transactions that were once common in the jewellery trade are being systematically phased out through legislative mandates.
Understanding the Cash Transaction Limit: Section 269ST
One of the most frequently misunderstood aspects of gold purchasing is the limitation on cash payments. Many consumers believe that as long as they pay in cash, the transaction remains "off the books." This is a dangerous misconception.
Under Section 269ST of the Income-tax Act, the law explicitly prohibits any person from receiving an amount of ₹2 lakh or more in cash:
- In aggregate from a single person in a single day;
- In respect of a single transaction; or
- In respect of transactions relating to one event or occasion.
The Burden of Compliance
It is vital to note that the burden of this compliance lies primarily with the jeweller (the recipient). If a customer attempts to pay ₹2 lakh or more in cash for a piece of jewellery, the jeweller is legally obligated to refuse the payment. If a jeweller accepts such a payment, they face a penalty under Section 271DA, which equates to the entire amount received in violation of the rule.
This creates a self-regulating mechanism where reputable jewellers will strictly insist on digital payment methods—such as NEFT, RTGS, IMPS, UPI, or credit/debit cards—for any purchase exceeding the ₹2 lakh threshold. Attempting to bypass this by splitting payments across multiple invoices or days for the same purchase is a direct violation of the law and can lead to severe tax scrutiny for both the buyer and the seller.
The Role of the PAN Card in Jewellery Purchases
For transactions exceeding ₹2 lakh, the production of a Permanent Account Number (PAN) is mandatory. This is a standard Know Your Customer (KYC) requirement designed to create an audit trail for high-value purchases.
Documentation Requirements
- PAN Requirement: When the transaction value crosses the ₹2 lakh mark, the jeweller is legally required to record the buyer’s PAN. This information is reported to the Income Tax Department as part of the Annual Information Statement (AIS).
- Form 97 and Form 60: For individuals who do not possess a PAN, there are specific declaration requirements. As of April 1, 2026, Form 97 has replaced the older Form 60 for certain categories of individuals.
- KYC and Anti-Money Laundering (AML): Beyond the PAN requirement, jewellers are often mandated to follow AML regulations. Depending on the risk profile and the nature of the transaction, you may be asked to provide additional identity verification, such as an Aadhar card or a passport, to ensure compliance with the Prevention of Money Laundering Act (PMLA).
How Much Gold Can You Legally Keep at Home?
Perhaps the most common myth surrounding gold ownership is that there is a specific, hard limit on how much gold a family can store in their home locker.
In December 2016, the Ministry of Finance provided a definitive clarification to address public anxiety regarding tax raids. The government stated clearly that there is no limit on the amount of gold jewellery or ornaments a person can possess, provided the gold has been acquired through known and explained sources of income.

The "Safe Limit" for Seizure
While there is no limit on ownership, there are "safe" limits regarding what tax authorities will not seize during a search or raid:
- Married Women: Up to 500 grams of gold jewellery.
- Unmarried Women: Up to 250 grams.
- Men: Up to 100 grams.
It is crucial to understand that these figures are not "caps" on ownership; they are merely guidelines for tax officers during a search. If you hold more than these amounts, it does not mean your gold is illegal or subject to automatic seizure.
Proving Your Ownership
If your gold holdings exceed these guidelines, you must be prepared to substantiate your ownership. The burden of proof lies on the taxpayer. To protect your assets from being categorized as "unexplained income," you should maintain a systematic file containing:
- Purchase Invoices: Always retain original bills for all jewellery, bars, and coins.
- Inheritance Records: If the gold was passed down through generations, keep a record of the Will or family settlement documents.
- Gift Deeds: If you received gold as a gift, maintain a formal gift deed or documentation from the donor.
- Bank Withdrawal Records: If you made large purchases, keeping copies of bank statements that show the withdrawal or transfer of funds can serve as strong evidence.
Implications for the Modern Investor
The regulatory environment is shifting toward total transparency. For the festive buyer, this means the days of "no-questions-asked" cash purchases are effectively over.
1. Transparency is Your Best Defense
When you buy gold, view it as an investment that requires documentation. Even if a jeweller does not insist on a PAN for a transaction just below the ₹2 lakh mark, it is advisable to maintain the bill and keep a digital copy of the payment.
2. The Impact of Digital Payments
With the rise of UPI and net banking, the audit trail for gold purchases has become instantaneous. This is beneficial for the consumer; digital transactions provide an irrefutable record of the date, time, and amount, which can be presented to tax authorities if ever required.
3. Understanding "Explained Sources"
The key phrase in all tax-related gold queries is "explained sources of income." Whether you are buying gold with your salary, business profits, or inheritance, ensure that these funds are reflected in your tax filings. If your gold purchase is commensurate with your declared income, you have nothing to fear from authorities.
Conclusion: Celebrating Responsibly
Dhanteras and the broader festive season remain a time of joy and cultural continuity. While the tax rules and compliance requirements might seem daunting, they are fundamentally designed to integrate the gold trade into the formal economy.
By adhering to the ₹2 lakh cash limit, ensuring your PAN is readily available for large purchases, and meticulously maintaining documentation for your jewellery, you can enjoy your festive acquisitions with complete peace of mind. As India’s financial landscape evolves, the smart investor is one who treats their gold not just as a precious metal, but as a documented asset, fully aligned with the nation’s legal framework.
This festive season, as you prepare to bring home the glitter of gold, remember: the most valuable thing you can possess alongside your ornaments is the clarity of your records.